Every financial pundit on television repeats the exact same bedtime story. They look at a trillion-dollar market cap, point at a slick presentation slide of a humanoid robot, and declare that Tesla is an unstoppable artificial intelligence juggernaut leaving legacy automakers and tech giants in the dust.
That narrative is lazy consensus built on vaporware, creative accounting, and a fundamental misunderstanding of how real-world AI actually scales.
Tesla is not winning the AI race. They are fighting a war of attrition on two fronts—consumer automotive hardware and embodied robotics—while entrenched hyperscalers and specialized autonomy firms quietly eat their lunch on unit economics, regulatory approval, and foundational compute. If you are an investor, an engineer, or a competitor benchmarking your strategy against Elon Musk’s keynote timelines, you are optimizing for the wrong metrics entirely.
The Compute Mirage and the Hardware Trap
Let’s look at the engineering reality underneath the hype. For years, the bull thesis rested on a simple premise: millions of customer vehicles on the road acting as a decentralized data-collection fleet, feeding video clips back to Dojo, Tesla’s custom supercomputer, to train end-to-end neural networks.
The logic sounds airtight on a podcast. In practice, it is an operational bottleneck.
First, collecting petabytes of edge-case driving video is useless if your labeling, simulation, and validation pipelines choke on the noise. While Tesla spent billions building out Nvidia H100 and H200 clusters alongside its proprietary Dojo silicon, competitors took a radically different architectural path. Waymo, backed by Alphabet’s decades-long dominance in custom TPUs and foundational research from Google DeepMind, bypassed the consumer-fleet trap altogether. They built high-precision, multi-modal sensor suites—combining LiDAR, radar, and high-resolution cameras—paired with deterministic safety guardrails and massive cloud-based world models.
Tesla’s dogmatic refusal to use LiDAR and radar in its mass-market vehicles was never a visionary AI breakthrough. It was a bill-of-materials cost-cutting measure disguised as a first-principles engineering philosophy.
Cameras are passive sensors. They measure reflected photons. When physics gets ugly—driving directly into a low winter sun, navigating blinding torrential rain, or parsing unlit black-on-black obstacles at highway speeds—a camera-only vision system is forced to hallucinate depth and intent from degraded 2D pixels. Solving that problem strictly through neural network inference requires orders of magnitude more compute and training data just to reach the baseline safety floor that sensor fusion achieves out of the box.
I have watched hardware startups burn through hundred-million-dollar Series B rounds trying to pull off this exact same software-over-sensors magic trick. They convince themselves that enough transformer layers can compensate for cheap, noisy inputs. Every single time, they hit the asymptotic wall of the "long tail." Getting a neural network to drive 99% of the time is a solved undergraduate project. Getting it to survive the remaining 0.0001% without killing a pedestrian requires hardware redundancy that software simply cannot synthesize out of thin air.
The Autonomy Shell Game
To understand why rivals are not actually "racing to keep up," look at commercial deployment metrics rather than demo videos.
In the autonomous vehicle sector, the only metric that matters is rider-only paid miles without a safety driver. Not "supervised" miles. Not intervention rates self-reported by enthusiasts on social media. Commercial, driverless liability assumed by the corporation.
Waymo is already executing hundreds of thousands of paid, fully driverless trips every single week across dense, chaotic urban grids like San Francisco, Phoenix, and Los Angeles. Baidu’s Apollo Go is doing massive volume across Wuhan and major Chinese metropolises. Meanwhile, Tesla’s Full Self-Driving (FSD) remains legally classified as a Level 2 driver-assistance system. The human in the driver's seat holds 100% of the legal and financial liability when the car makes a mistake.
The leap from Level 2 supervision to Level 4 commercial autonomy is not a linear software update. It is a chasm of liability, teleoperations infrastructure, fleet maintenance, and regulatory compliance.
When you transition from selling cars to operating a robotaxi network, your business model inverts overnight. You are no longer collecting high-margin upfront hardware revenue from retail buyers; you are managing depreciating physical assets on your own balance sheet, paying for commercial insurance, cleaning vomit out of backseats at 3:00 AM, and absorbing downtime during off-peak hours. Rivals like Waymo and Zoox engineered their vehicles and unit economics around this brutal operational reality from day one. Tesla is trying to retrofit a retail consumer sedan business into a utility-scale transit operator while simultaneously watching its core automotive gross margins compress under global price wars.
What People Get Wrong About the "Data Advantage"
A common question among retail investors is: Doesn't Tesla's massive fleet give them an insurmountable data moat?
The premise of that question is flawed. Data volume does not equal data quality.
Ninety-nine percent of highway driving is completely redundant—straight lines, clear lane markings, predictable traffic flow. Feeding a model another ten million hours of sunny California freeway cruising adds zero marginal intelligence. What actually improves an autonomous policy is high-entropy edge cases: a construction worker waving a hand-painted sign while a fire truck approaches against traffic in heavy fog.
You do not need two million customer cars to capture or train on those scenarios. Modern generative world models and photorealistic neural rendering engines (like NeRFs and Gaussian splatting) allow AI labs to take one real-world edge case and synthetically generate ten thousand variations of lighting, weather, and actor trajectories in hours. Companies like Wayve, Waabi, and Nvidia with its Omniverse platform are proving that simulation-first training with targeted, high-precision sensor data beats brute-force fleet scraping on both capital efficiency and safety validation.
Optimus and the Embodied AI Illusion
When the autonomous timeline slips, the narrative conveniently pivots to humanoid robotics. We are told that Optimus will eventually be worth more than the entire automotive business, turning Tesla into a multi-trillion-dollar labor monopoly.
Let’s dissect the engineering reality of bipedal robotics.
Building a humanoid robot that can walk across a flat factory floor, pick up a standardized battery cell, and place it in a tray is impressive mechanical engineering. It is not general-purpose artificial intelligence.
In industrial manufacturing, specialized robotic arms bolted to the floor already perform pick-and-place tasks faster, cheaper, and with sub-millimeter precision that a bipedal humanoid will never match. Why would a factory owner pay for a complex, battery-powered, two-legged machine with dozens of expensive actuators and balance sensors just to stand in one spot and sort parts? They wouldn't. Humanoids only make economic sense in unstructured human environments—homes, construction sites, hospitals, and dynamic warehouses—where the robot must navigate stairs, clutter, fragile objects, and unpredictable human coworkers.
And in those unstructured environments, the bottleneck is not mechanical hardware; it is generalizable manipulation and common-sense reasoning.
Right now, robotics foundation models suffer from severe data scarcity. Unlike Large Language Models, which trained on the entire digitized text of human civilization scraped from the internet for free, there is no "internet of physical touch." Every trajectory of a robotic hand grasping a slippery ceramic mug, folding a crumpled towel, or applying just enough torque to turn a stripped screw has to be collected through painstaking teleoperation or brittle physics simulations.
Look at who is actually pushing the boundaries of embodied reasoning and manipulation:
- Figure AI and Physical Intelligence (Pi) are building hardware-agnostic vision-language-action (VLA) models designed to work across diverse robotic morphologies.
- Boston Dynamics has spent decades mastering dynamic control theory and hydraulic-to-electric actuation, partnering directly with Toyota Research Institute to integrate large behavior models.
- Nvidia is positioning itself as the picks-and-shovels kingmaker of the entire sector with Project GR00T and Isaac Lab, ensuring that regardless of which robot hardware wins, Nvidia captures the compute margin.
Tesla is treating robotics as an extension of its automotive manufacturing playbook. That works when you are stamping sheet metal and casting aluminum gigapressings. It falls apart when the core problem is dexterous tactile intelligence that no company on earth has solved at commercial scale.
The Real AI Heavyweights Are Eating the Stack
While media headlines obsess over flashy demos, the actual power dynamics of the artificial intelligence industry are solidifying around three layers: foundational frontier models, sovereign-scale compute infrastructure, and enterprise workflow integration. Tesla is a minor player in all three.
- Frontier Reasoning: OpenAI, Anthropic, Google DeepMind, and Meta are training multimodal models that do not just recognize objects in a video frame—they reason across code, mathematics, physics, and long-horizon planning. Tesla’s in-house AI team is laser-focused on narrow spatial-temporal inference for driving and basic kinematics. They are not competing at the frontier of general reasoning, nor does Elon Musk’s separate venture, xAI, automatically accrue value to Tesla shareholders. In fact, xAI represents a massive governance conflict, competing directly with Tesla for top AI researchers, Nvidia GPU allocations, and executive attention.
- Silicon Economics: Nvidia commands roughly 80% to 90% of the AI training and inference accelerator market, backed by the CUDA software ecosystem that locks in developers. Cloud hyperscalers like AWS (Trainium), Google (TPU), and Microsoft (Maia) are deploying custom silicon at a scale that dwarfs Dojo. Building custom AI chips is a brutal, capital-intensive treadmill; if your internal silicon cannot beat Nvidia’s next-generation architecture on performance-per-watt by the time it tapes out, you just burned billions of dollars on obsolete sand.
- Distribution and Cash Flow: Microsoft, Alphabet, and Meta fund their $50 billion to $80 billion annual AI capital expenditures out of high-margin, recurring software and advertising cash flows. Tesla funds its AI ambitions out of a capital-intensive, cyclical manufacturing business where vehicle price cuts directly cannibalize the free cash flow needed to buy more GPUs.
Where the Contrarian Thesis Could Break
Intellectual honesty requires admitting where this argument is vulnerable. Dismissal is just as dangerous as blind hype.
Tesla possesses two structural advantages that no traditional automaker and few pure-play AI startups can replicate: vertically integrated manufacturing velocity and unmatched retail brand gravity.
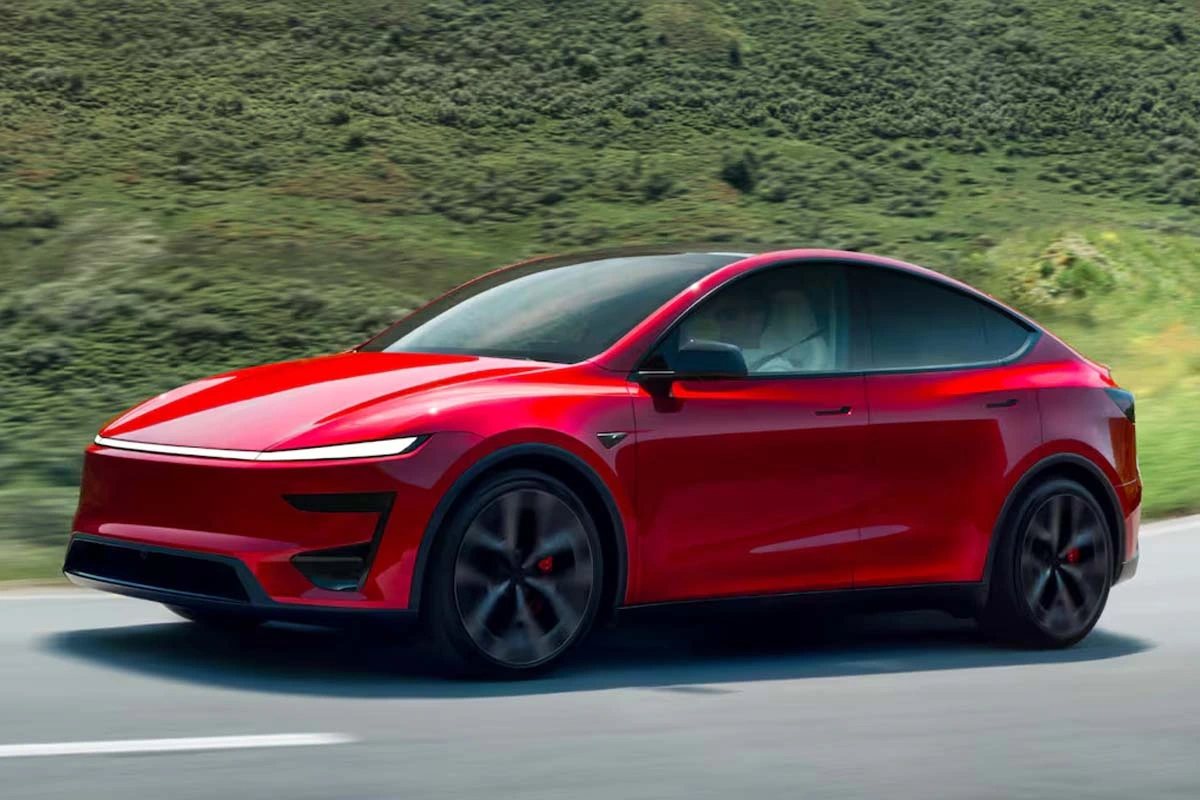
If—and this is a massive conditional—end-to-end neural networks trained purely on video eventually solve generalized spatial reasoning without needing LiDAR or high-definition maps, Tesla’s cost structure becomes lethal. While competitors spend $80,000 to $150,000 per vehicle outfitting custom sensor pods, Tesla can roll a Cybercab or Model Y off the assembly line for a fraction of that cost. In a commodity transit market, the lowest-cost producer always wins once the safety threshold is met.
Similarly, in humanoid robotics, the hardest part after solving the AI is scaling production from a hundred prototypes to a million units at an affordable price point. Most robotics startups will die in "production hell" trying to source actuators, batteries, and harmonic drives at scale. Tesla already owns the supply chain relationships, battery manufacturing, and high-volume assembly expertise to flood the market the moment the software becomes minimally viable.
How to Actually Navigate This Market
If you are building, investing, or competing in the physical AI space, stop reacting to press releases and start filtering out the noise with three hard rules:
- Separate R&D demos from unit economics. Never value a technology based on a curated keynote video. Demand to see unedited, continuous operational logs, mean time between failures, and fully burdened cost per mile or per task.
- Bet on the picks and shovels, not the hype cycles. Whether autonomous vehicles or humanoids take three years or fifteen years to reach mass adoption, every single player in the race must pay taxes to the foundational compute, simulation, and sensor infrastructure providers.
- Watch capital allocation, not rhetoric. Follow where the best engineers go and where the free cash flow actually lands. When a company splits its AI talent across multiple corporate entities while simultaneously slashing prices on its core cash-cow product, treat its valuation multiples with extreme skepticism.
Rivals are not scrambling to catch up to Tesla. They are deliberately refusing to play a game where the timelines are fictional, the regulatory liabilities are ignored, and the hardware margins are shrinking. Stop grading the AI race by who makes the loudest promises on stage, and start grading it by who actually delivers reliable, profitable autonomy in the real world without a human safety net.