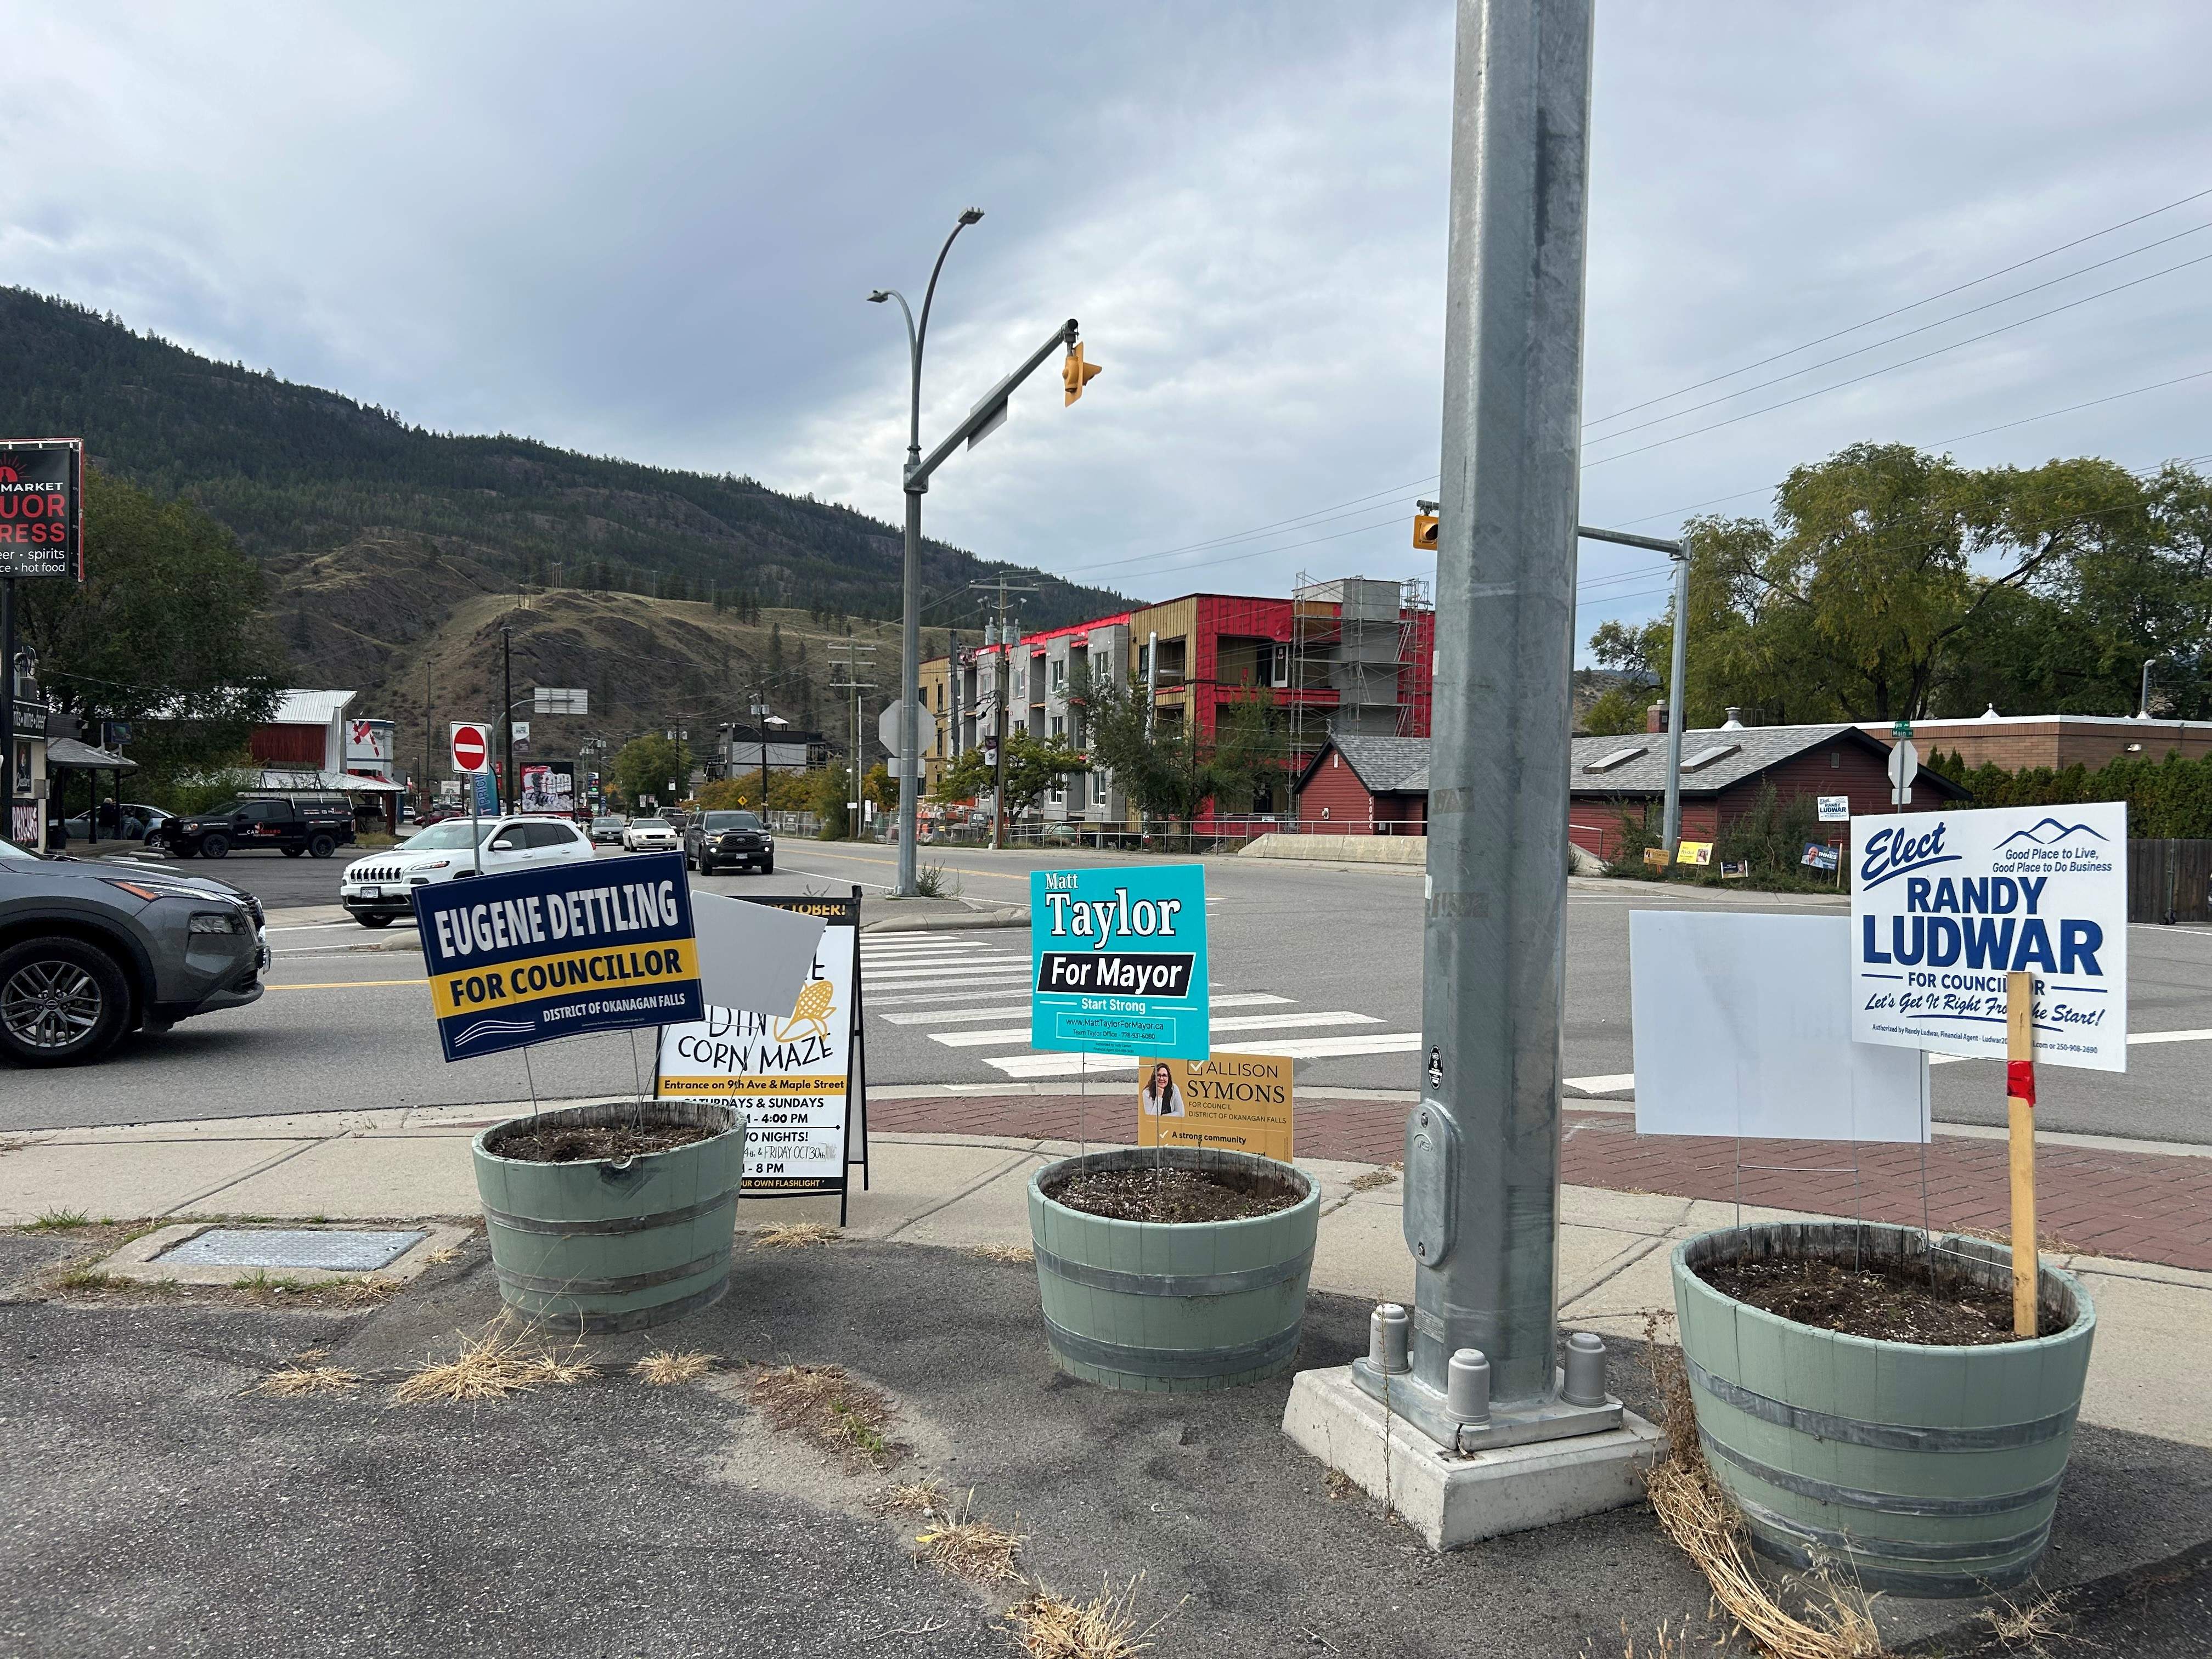
When a community transitions from an unincorporated electoral area governed by a regional district to an autonomous municipality, the structural change requires a complete rewiring of public finance, administrative overhead, and local governance accountability. The inaugural municipal election in Okanagan Falls, British Columbia, following its historic incorporation vote, illustrates the complex mechanics of institutional birth. Shifting from regional district representation to a dedicated local council changes the tax burden distribution, service delivery models, and the speed of capital allocation.
The Fiscal Architecture of Transition
The core challenge of any municipal incorporation lies in untangling assets, liabilities, and service agreements from the parent regional district—in this case, the Regional District of Okanagan-Similkameen (RDOS). Under unincorporated governance, residents pay regional property taxes for specific services while relying on the regional body for broad planning frameworks.
Incorporation forces the newly formed municipality to internalize the fixed costs of governance that were previously distributed across a larger administrative base.
- The Administrative Overhead Ratio: A small municipal entity must immediately establish core administrative functions, including a chief administrative officer, a corporate officer, and financial management infrastructure. These fixed personnel costs do not scale linearly with population size, creating a high initial cost floor for small tax bases.
- Service Disentanglement: Fire protection, water infrastructure, zoning authority, and local road maintenance must be formally transferred or re-negotiated. Each transferred asset carries a deferred maintenance liability that the new council inherits on day one.
- The Assessment Base Constraint: Okanagan Falls possesses a finite commercial and residential property tax assessment base. Without the industrial tax anchors found in larger municipalities, capital projects rely heavily on residential property taxation or conditional provincial and federal grants.
The Governance Deficit and Representative Density
Moving from an electoral area director model to a mayor-and-council structure alters representative density. In a regional district, a single area director often acts as the sole voice at a board table dominated by urban municipalities. A dedicated municipal council introduces a localized legislative body where policy decisions require direct majority consensus among local representatives who live adjacent to the constituents they tax.
This proximity creates an immediate operational tension. Citizens accustomed to regional service delivery expectations suddenly gain direct access to elected officials for localized grievances, such as pothole repair, zoning variances, and local policing priorities. The governance framework must transition from passive administration to active municipal asset management.
The Economic Implications of Local Autonomy
The primary economic justification for municipal incorporation is local control over land use planning and economic development. When land use decisions are made by a regional board, rural priorities often overshadow localized commercial densification.
By establishing an autonomous municipal council, Okanagan Falls gains the direct legal authority to zone for commercial and light industrial growth without appealing to a regional consensus. However, this authority introduces immediate financial exposure.
- Capital Expenditure Sequencing: Water and sewer infrastructure upgrades are capital-intensive. An incorporated municipality cannot defer infrastructure deficits indefinitely without violating provincial environmental standards or risking asset failure.
- Grantsmanship Dependency: Newly incorporated entities often rely on transition grants from the provincial government to absorb initial administrative shocks. The long-term solvency of the municipality depends on its ability to shift from grant dependency to organic tax base growth through strategic development.
Strategic Execution for Inaugural Administrations
The immediate operational priority for the incoming Okanagan Falls council is establishing a transparent baseline audit of municipal assets and liabilities. Councils entering office post-incorporation frequently encounter underestimated maintenance backlogs hidden within regional district ledgers.
- Ring-Fence Capital Reserves: Allocate incoming municipal restructuring funds strictly toward deferred infrastructure liabilities rather than operational expansion.
- Rationalize Regulatory Bylaws: Adopt interim regional bylaws while systematically rewriting zoning codes to match the specific economic density targets of the community.
- Establish Service Level Agreements: Audit every shared service inherited from the regional district to determine whether internal delivery or contracted continuation yields a lower cost function over a five-year horizon.
The long-term viability of Okanagan Falls as an autonomous entity depends entirely on disciplined capital allocation during its first legislative term. Failure to contain administrative bloat while assuming inherited infrastructure debt will compress the tax base, forcing steep property tax adjustments that undermine the original economic rationale for municipal independence.