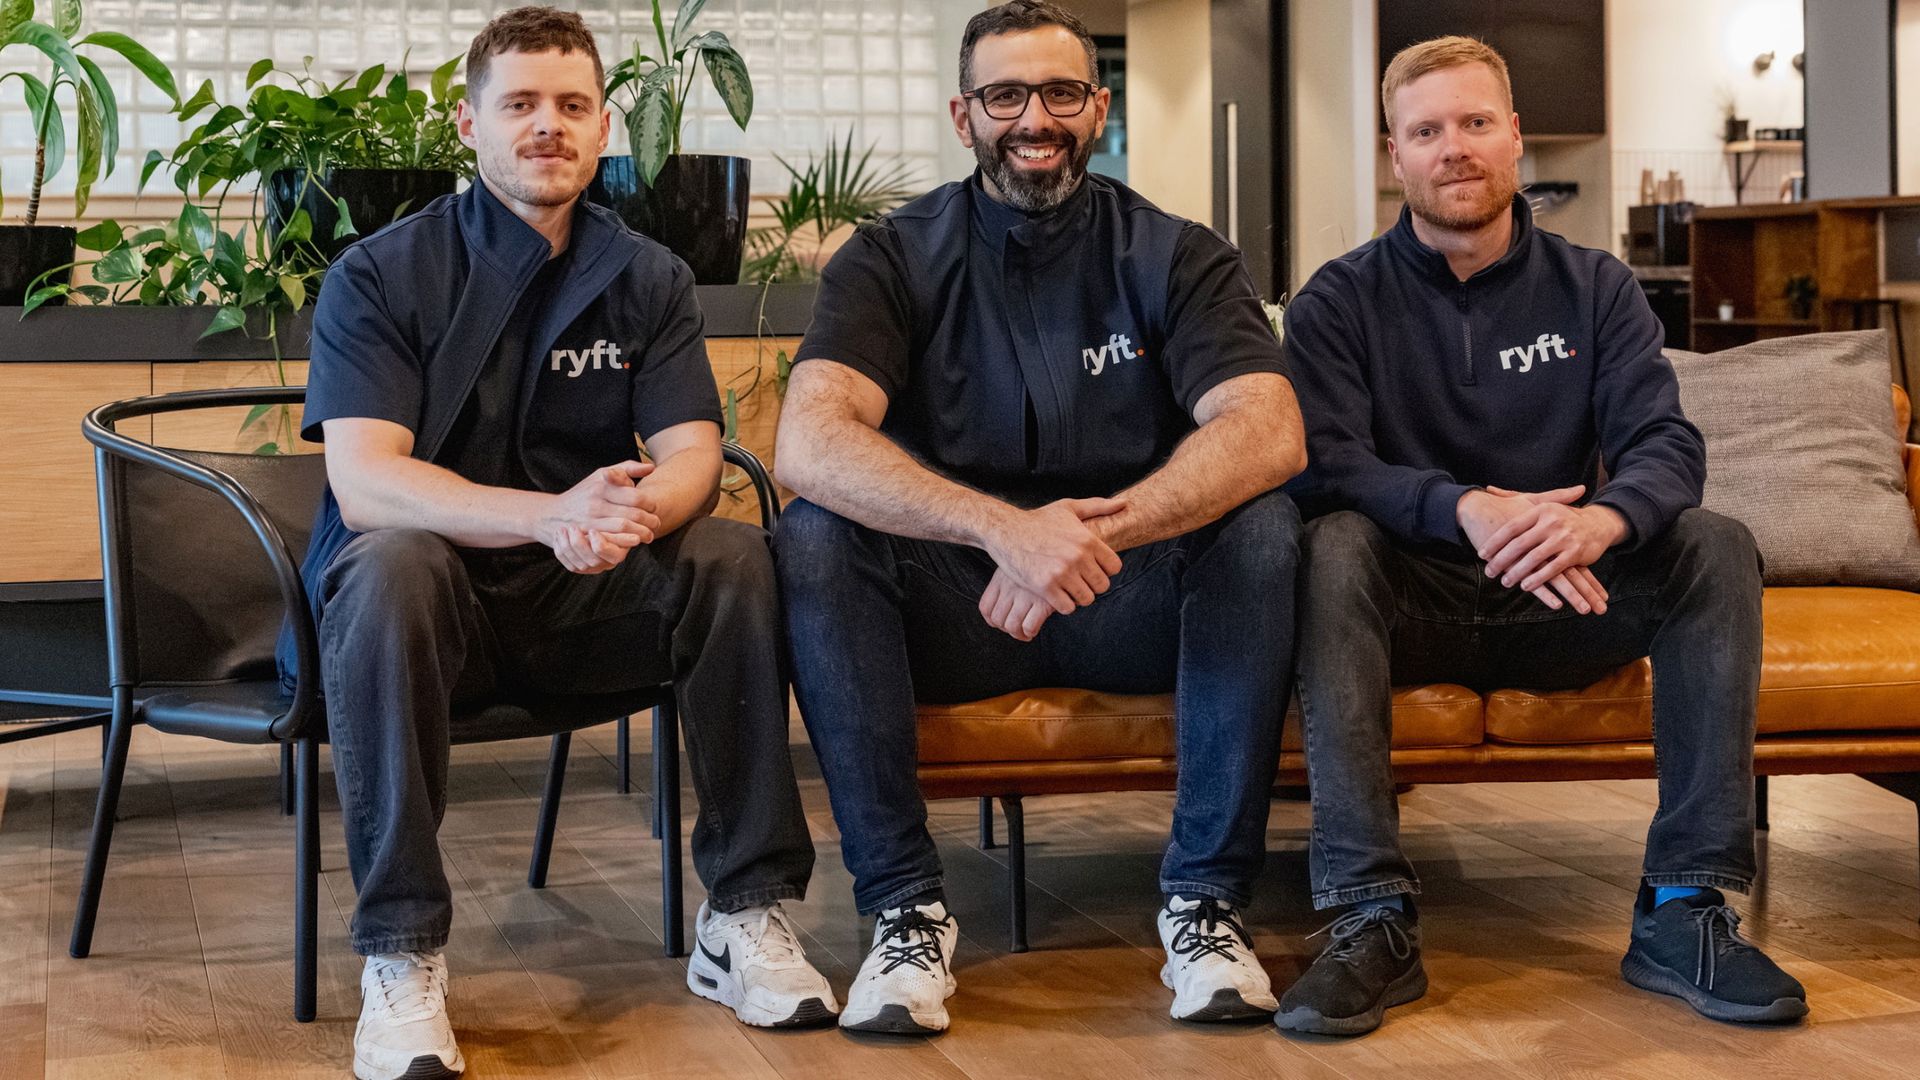
Capital allocation within European fintech has undergone a quiet rotation. Venture capital has largely retreated from low-margin consumer lending, concentrating instead on deep infrastructure plays capable of capturing transaction flow. The closed £20 million Series B funding round secured by Manchester-based payments platform Ryft, led by Gresham House Ventures alongside institutional backers like the Northern Powerhouse Investment Fund II, highlights an aggressive market bet: that traditional payment gateways are structurally ill-equipped to handle multi-party commerce.
To understand why a regional processor commands a multi-million-pound war chest to fund expansion into the European Economic Area and the United States, one must deconstruct the mechanics of modern digital marketplaces, automated vendor payouts, and the underlying unit economics of payment routing.
The Economic Friction of Traditional Payment Architecture
Legacy payment gateways were engineered for a bilateral economy. A consumer purchases a good from a single merchant, funds flow into an acquiring bank account, and settlement occurs after standard clearing delays. This architecture breaks down under the weight of multi-party commerce, where a single transaction must be dynamically split among numerous sub-merchants, creators, or service providers instantly.
When marketplaces rely on legacy aggregators, they face three structural penalties:
- The Working Capital Trap: Funds are pooled into a central master account held by the platform before manual or batch payouts occur. This introduces legal and regulatory exposure under safeguarding requirements, transforming the software platform into an unintended regulated financial institution.
- The Double-Processing Cost Bottleneck: Traditional setups require taking a payment and subsequently initiating a secondary payout. Each leg incurs independent interchange and processing fees, compounding margin erosion on low-ticket, high-frequency transactions.
- Geographic Compliance Fragmentation: Cross-border expansion forces companies to stitch together multiple regional acquirers, each with disparate API standards, fraud scoring rules, and dispute resolution workflows.
Ryft’s market positioning targets this exact friction point by embedding automated splitting directly into the initial transaction authorization layer. By routing funds to multiple beneficiaries at the point of capture, the architecture removes the platform from the regulated money-transmission loop while eliminating secondary payout fees.
The Cost Function of International Scale
Expanding payments infrastructure across jurisdictions is constrained by regulatory capture and licensing friction. Ryft's concurrent application for a full electronic money or payment institution licence via the Malta Financial Services Authority is not merely a bureaucratic checkbox; it is a calculated play for passporting rights across the European Economic Area.
Obtaining direct regulatory authorization alters a scaleup's unit economics by replacing wholesale white-label partner fees with direct access to clearing schemes. However, this strategy introduces a distinct operational risk profile:
- Compliance Overhead: Maintaining multi-jurisdictional compliance requires localized Anti-Money Laundering and Know Your Customer frameworks that scale linearly with transaction volume unless automated.
- Acquiring Concentration: Dependence on underlying scheme partners like Visa, Mastercard, and American Express creates a margin ceiling. True independence requires direct integration into domestic instant payment rails, a capital-intensive milestone for any expanding firm.
Strategic Execution and the Upmarket Pivot
The decision to deploy fresh capital toward an enterprise upmarket pivot reflects a broader truth about B2B financial technology: volume concentration yields margin stability. Serving over 6,500 SMBs provides robust baseline transaction data, but scaling up requires capturing enterprise-grade platforms processing millions of pounds monthly.
Enterprise clients do not buy software features; they buy risk mitigation and checkout optimization. Every basis point recovered on authorization rates or shaved off cross-border settlement times directly impacts a marketplace's bottom line.
Targeting the United States introduces an entirely different operating environment. Unlike the fragmented regulatory landscape of Europe, the US market is dominated by complex interchange fee structures and entrenched domestic processors. Winning market share there requires offering a deeply differentiated developer experience or a structural cost advantage on multi-party settlement that domestic incumbents cannot easily replicate.
Operational Playbook for Cross-Border Infrastructure
- Decouple Tech Stack from Local Licensing: Scale internationally by partnering with localized acquiring rails before committing capital to standalone regulatory applications in secondary markets.
- Automate Sub-Merchant Onboarding: Reduce compliance drop-off rates by embedding programmatic verification directly into the merchant sign-up flow.
- Optimize Interchange Routing: Implement dynamic routing engines that evaluate card type, issuing country, and historical authorization trends in real time to minimize failed payments.
Focus capital expenditure on direct scheme connectivity and regulatory passporting while maintaining lean operational overhead in non-core administrative functions.