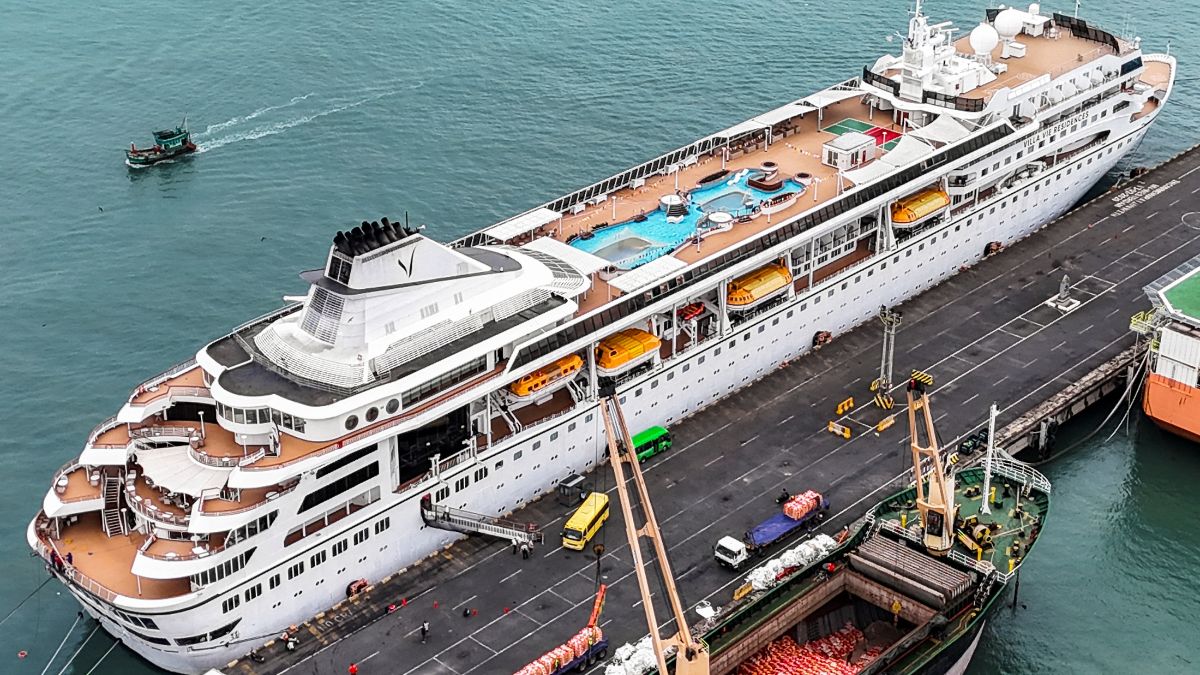
Mainstream travel coverage loves a simple villain. When a US luxury cruise ship aborts a global voyage and leaves wealthy retirees cooling their heels in Cambodia, the lazy headline writes itself: soaring fuel costs killed the trip.
That narrative is convenient, dramatic, and completely misses how maritime finance actually operates.
Blaming bunker fuel for an aborted world cruise is like blaming a $6 latte for a bankrupt tech startup. Fuel is volatile, loud, and visible on a balance sheet, making it the perfect scapegoat for executives who mismanaged working capital, failed to hedge operating expenses, or sold cabins at a steep discount just to keep cash flowing in the door.
If you look past the press releases and examine the mechanics of luxury expedition and residential cruising, a different story emerges. Passengers are not stranded in Sihanoukville because diesel got expensive overnight. They are stranded because small-scale operators run razor-thin liquidity models disguised as ultra-luxury experiences—and travelers keep falling for the illusion.
The Bunker Fuel Scapegoat
Every maritime analyst knows bunker fuel—specifically Very Low Sulfur Fuel Oil (VLSFO) and Marine Gas Oil (MGO)—makes up a massive chunk of a vessel’s daily burn rate. Depending on hull design, speed, and itinerary, fuel typically accounts for 15% to 25% of a cruise line’s operating costs.
When geopolitical shocks or supply bottlenecks spike crude prices, margins compress. Nobody disputes that.
What the mainstream coverage ignores is how competent operators manage that risk. Major lines like Royal Caribbean Group, Carnival Corporation, and Norwegian Cruise Line Holdings use structured fuel hedging programs, long-term supply contracts, and itinerary optimization—like slow steaming—to absorb price swings without canceling voyages mid-stream. Even when unhedged exposure hits earnings, publicly traded lines draw on revolving credit facilities or raise capital rather than abandoning a ship full of paying customers in Southeast Asia.
When a boutique or independent cruise operator halts a world tour over "fuel costs," translation is required. What they actually mean is: we ran out of cash, and our marine fuel suppliers demanded payment upfront.
Bunker suppliers are notoriously unsentimental. Unlike hotel vendors or shore excursion operators who might extend net-30 or net-60 payment terms, marine fuel brokers watch vessel credit ratings like hawks. The moment an operator misses a payment or shows signs of distress, suppliers cut off credit and demand wire transfers before a single drop of fuel enters the tanks. No wire, no bunker. No bunker, no sailing.
Why Boutique World Cruises Are Financial Tightropes
I have watched independent maritime ventures burn through tens of millions of dollars before their ships even cleared dry dock. The pattern is always identical.
An ambitious startup or niche operator acquires an older, mid-sized vessel—often 20 to 30 years old—with plans to rebrand it as an intimate, ultra-luxury world cruiser. They pitch a dream: no mega-ship crowds, bespoke ports, months at sea, and all-inclusive pricing. To fill the cabins quickly, they offer aggressive early-bird discounts or lifetime residential leases, collecting cash upfront to fund refurbishment and initial operations.
Here is the fatal flaw in that math: unearned revenue is not profit, yet struggling operators spend it like free cash flow.
When you collect $50,000 to $250,000 per cabin a year before departure and use that money to pay shipyard bills, crew back-pay, and marketing agencies, you create a working capital deficit before the anchor even lifts. Once the ship sails, every nautical mile burns cash—crew wages, port fees, provisioning, insurance, and yes, fuel—while almost no new revenue comes aboard because everyone already paid upfront.
If occupancy falls 10% short of projections, or if fuel rises 15% above baseline estimates, there is no buffer. The company has already spent the ticket money.
The Structural Differences Nobody Checks Before Booking
Travelers routinely spend $80,000 on a world cruise without doing five minutes of balance-sheet due diligence. They compare thread counts and wine lists while ignoring the only metric that determines whether they will actually make it home: financial capitalization.
| Risk Factor | Major Public Cruise Lines | Niche / Independent World Cruisers |
|---|---|---|
| Fuel Risk Management | Active hedging, bulk purchasing contracts, slow-steaming algorithms | Spot-market purchasing, zero hedging, immediate cash vulnerability |
| Liquidity Buffer | Multi-billion-dollar credit revolvers and institutional debt access | Reliant on ongoing ticket deposits to fund current voyages |
| Fleet Maintenance | Continuous dry-dock schedules and strict classification compliance | Aging tonnage prone to unscheduled mechanical delays and port state detentions |
| Passenger Protection | Federal Maritime Commission (FMC) bonding for US embarkations, established rebooking networks | Minimal bonding if embarking abroad, limited charter capacity for repatriation |
Look closely at that last row.
Under US law, the Federal Maritime Commission requires passenger vessel operators embarking from US ports to maintain financial responsibility coverage—typically capped at $32 million—to reimburse passengers if a voyage is canceled. However, many world cruises and niche expeditions bypass US embarkation entirely, starting in Europe, South America, or Asia. When a foreign-flagged vessel operated by a thinly capitalized shell company stalls in Cambodia, US consumer protections rarely reach the pier.
Answering the Questions Stranded Passengers Actually Ask
When a voyage collapses mid-itinerary, the internet fills up with frantic searches from booked guests and their families. Most travel blogs answer these questions with useless platitudes about "reading the fine print." Here is the blunt reality.
Will travel insurance cover a cruise canceled due to fuel costs?
Almost never—unless you bought a specific, expensive rider before the operator went under.
Standard trip cancellation and interruption policies cover named perils: severe weather, medical emergencies, jury duty, or sudden death in the family. Financial default of a travel supplier is routinely excluded from basic plans. Even when a policy includes "financial default" coverage, insurers enforce strict conditions:
- You must purchase the policy within 10 to 21 days of your initial trip deposit.
- The operator must formally file for bankruptcy or cease all operations—simply pausing an itinerary to "restructure" or negotiate fuel bills often traps claims in bureaucratic limbo.
- Many insurers maintain an explicit blacklist of troubled cruise lines and tour operators they refuse to cover under any circumstances.
If you skipped Cancel For Any Reason (CFAR) coverage—which typically reimburses 50% to 75% of non-refundable costs and adds 40% to 50% to your premium—you are likely fighting an uphill battle.
Can you get your money back through a credit card chargeback?
Yes, and it is often your strongest weapon, provided you paid with a credit card rather than a wire transfer or ACH debit.
Under the Fair Credit Billing Act in the US, consumers can dispute charges for services paid for but not rendered. If you paid $100,000 for a 120-day voyage and the ship halted on day 40, you have a legitimate claim for the undelivered portion of the trip.
The catch is timing and payment method. Many luxury cruise operators push buyers toward wire transfers by offering a 3% to 5% "cash discount." Never take that bait on a boutique operator. Once a wire clears, your leverage vanishes.
Why didn't the cruise line just add a fuel surcharge?
Because adding a surcharge mid-voyage triggers contract disputes and destroys brand trust, and more importantly, surcharges do not solve an immediate liquidity crisis.
Back in 2008, when crude oil topped $140 a barrel, major cruise lines slapped $5 to $10 per-day fuel supplements onto bookings. Regulators pushed back, forcing lines to clarify rules around retroactive fees on already-paid fares. Even if an operator legally reserves the right in its Ticket Contract to levy an emergency fuel surcharge, collecting an extra $1,000 per cabin from angry passengers in Cambodia takes weeks—while the bunker barge waiting outside Sihanoukville demands $500,000 by Friday afternoon.
The Contrarian Case Against the "Anti-Mega-Ship" Snobbery
There is a downside to dismissing small, independent operators: mega-ships genuinely lack the intimacy and off-the-beaten-path access that seasoned travelers crave. A 5,000-passenger floating resort cannot dock in boutique river ports or navigate narrow fjords, and nobody wants to spend four months eating mass-produced banquet food.
But travel snobbery has blinded wealthy consumers to basic risk management.
In their rush to avoid mainstream cruise brands, luxury travelers routinely hand six-figure sums to unproven operators running 30-year-old ships with no public financial filings. Meanwhile, the ultra-luxury divisions of major conglomerates—lines like Seabourn (Carnival), Silversea (Royal Caribbean), and Regent Seven Seas (Norwegian)—deliver small-ship intimacy backed by multi-billion-dollar balance sheets.
You get the 400-passenger yacht feel, the Michelin-caliber dining, and the expedition Zodiacs, with one massive difference: if marine fuel spikes 30% tomorrow, a corporate treasury department in Miami absorbs the hit while you order another espresso on the lido deck.
How to Audit a Cruise Operator Before Wiring Six Figures
If you are planning to book a world cruise, residential ship, or extended expedition, stop reading glossy brochures and start acting like a credit analyst.
- Check the vessel’s port state control record. Look up the ship’s IMO number on public databases like Equasis or the Tokyo MOU and Paris MOU inspection registries. Frequent detentions for safety, firefighting, or engine maintenance deficiencies are a flashing red light for cash starvation.
- Verify who actually owns and manages the ship. Boutique brands frequently charter vessels from third-party owners. If the marketing company selling you the ticket does not own the hull, find out how long the charter agreement lasts and what happens if charter payments lapse.
- Refuse wire transfer discounts. Always pay with a high-limit credit card that carries strong dispute protections, even if it costs you an extra 3%. Treat that 3% as cheap catastrophe insurance.
- Demand proof of financial protection. Ask directly whether the operator holds a Federal Maritime Commission Performance Certificate or an equivalent European insolvency bond—and verify the certificate number directly with the regulator, not via a PDF sent by a salesperson.
Fuel prices rise and fall every quarter. Ships keep sailing through all of them—unless the company running the bridge was already running on fumes before the voyage began.