Headline risk is a retail trap. A tanker gets hit. Tehran threatens a new operational plan. Traders scramble to buy crude before the opening bell. Two hours later, half the spike fades because physical barrels keep moving and margin desks start trimming risk.
I have watched desks blow up chasing headlines like "Iran says it has a 'new operational plan' if the U.S. resumes attacks, as shipping vessels report strikes." The lazy consensus is simple: escalating military friction in or around key transit corridors equals an immediate, sustained supply shock, which equals higher oil prices and a weaker U.S. dollar or risk-off FX move.
That consensus is lazy because it confuses threat velocity with supply depletion. A threat can move in seconds on a wire feed. Removing millions of barrels per day from global balances—or permanently severing maritime insurance and transit—takes physical reality, time, and enforcement that rarely match the first wire report.
When traders treat every reported strike on a shipping vessel as a replay of a full-scale blockade, they overpay for volatility at the exact moment liquidity thins out. Worse, they ask the wrong question. They ask whether the U.S. will resume strikes or whether Tehran's new operational plan will trigger a spike. They should be asking how much spare capacity, floating storage, and insurance capacity actually stand between a localized strike and a true balance-sheet deficit.
The Lazy Consensus vs. Physical Market Mechanics
Standard retail and financial-wire commentary treats geopolitical escalations like light switches. Flip them on, and crude rockets; flip them off, and it drops. Real energy and currency markets behave more like shock absorbers with varying degrees of damping.
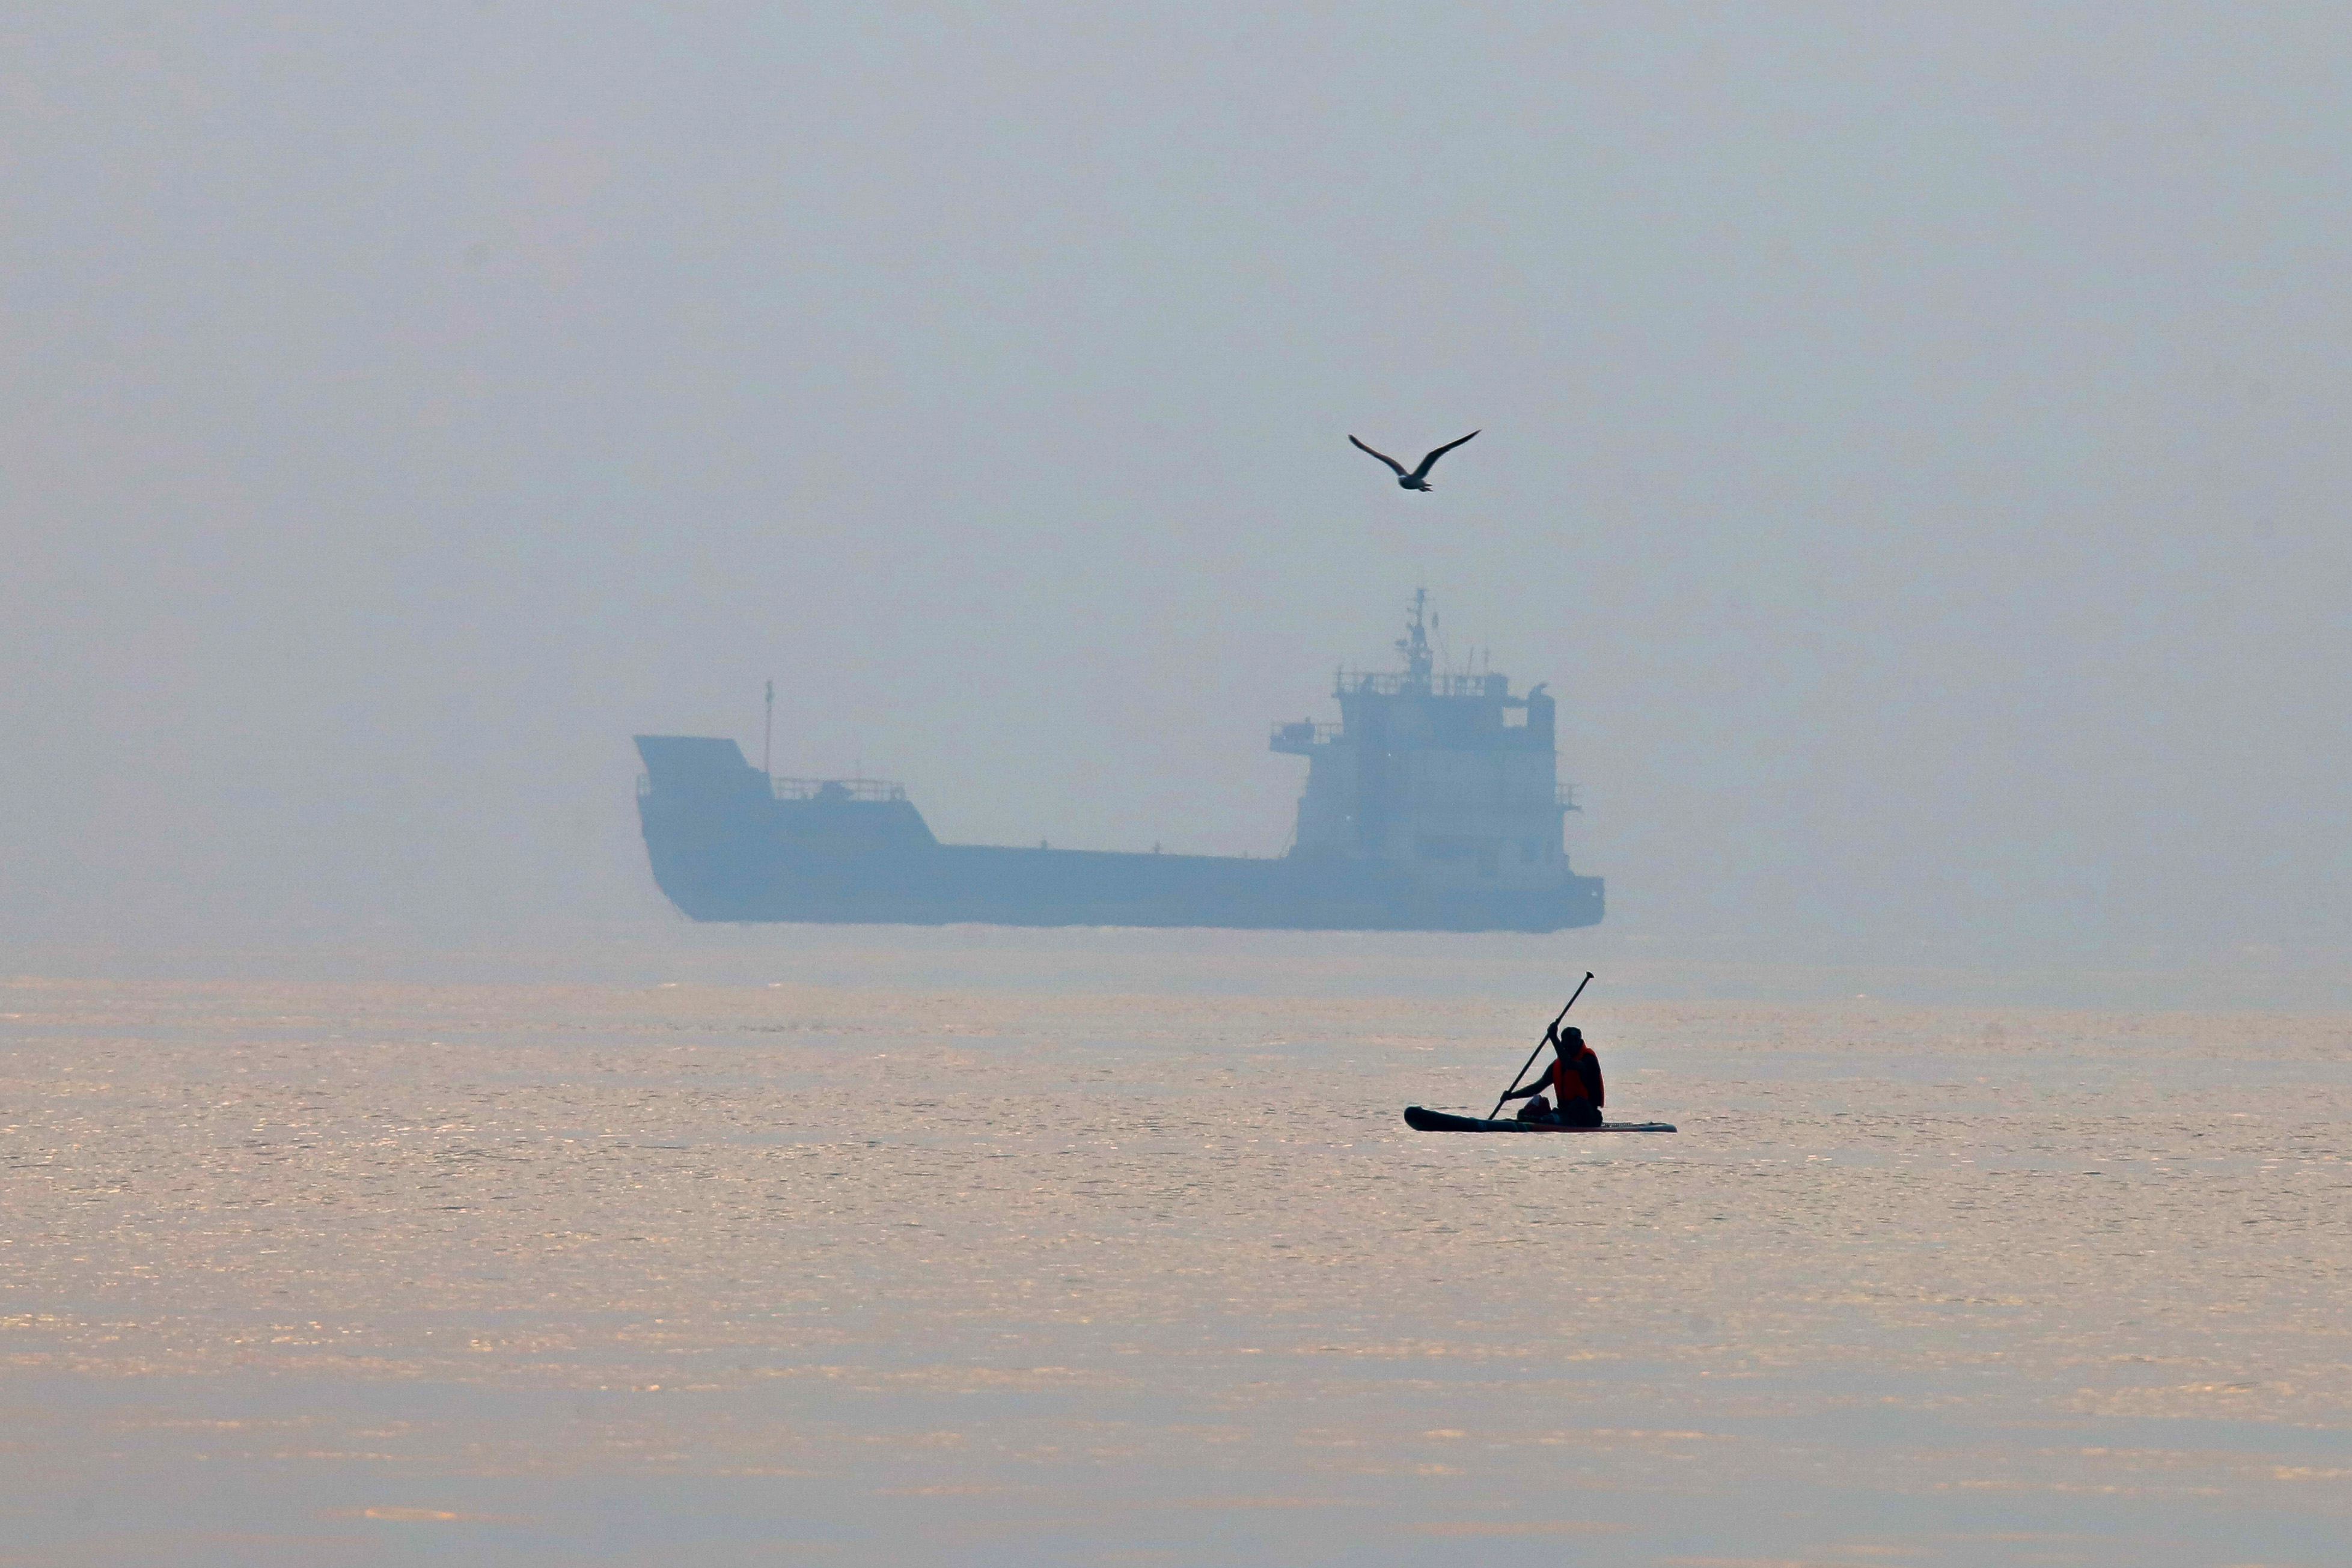
A report that shipping vessels suffered strikes creates immediate fear around transit chokepoints, especially in the Persian Gulf and surrounding waters. In the Strait of Hormuz, roughly a fifth of the world's petroleum liquids trade normally passes through a narrow channel flanked by coastal defenses, naval craft, and radar coverage. Anyone who has traded energy knows that even a single incident near that corridor makes charterers nervous.
Yet nervousness is not scarcity. Before price sustains a structural repricing, several physical checks have to fail at once:
- Sustained interdiction: Isolated hits, near-misses, or harassment of specific vessels differ sharply from a continuous, multi-week closure that stops laden tankers from exiting loading terminals.
- Inability to reroute: Pipelines—such as Saudi Arabia's East-West pipeline to Yanbu on the Red Sea and the UAE's Habshan-Fujairah pipeline to the Gulf of Oman—can bypass portions of Gulf chokepoints, though their spare capacity has practical limits and cannot absorb every barrel overnight.
- Demand destruction or refinery bottlenecks: Higher freight rates and war-risk premiums raise landed costs, which can squeeze refining margins just as easily as they lift headline crude.
In my years watching macro and commodity desks, the biggest losses rarely come from missing the first headline. They come from buying the third headline after liquidity providers have already widened spreads and raised margin requirements. You do not get a medal for being first into a crowded, illiquid order book.
What Tehran's "New Operational Plan" Actually Signals
When officials in Tehran announce a new operational plan contingent on renewed U.S. attacks, market participants often read it as a blueprint for instant, total closure. That reading misses how asymmetric posture works in practice.
States facing superior conventional air and naval power rarely advertise their exact tactical sequence in advance unless deterrence and signaling are part of the plan. Announcing a revised operational posture serves three distinct functions at once:
- Deterrence and cost imposition: It raises the perceived cost of renewed strikes by signaling dispersed, mobile, or multi-domain responses rather than a predictable single-point retaliation.
- Domestic and regional signaling: It projects resolve to internal constituencies and regional partners while keeping adversaries guessing about thresholds and targets.
- Ambiguity management: Keeping the specifics vague preserves flexibility—whether that means maritime harassment, drone or missile strikes, cyber disruption, or pressure through regional proxies—without locking leadership into an all-or-nothing move before shots are fired.
None of this means the risk is fake. Shipping vessels reporting strikes is a concrete operational event, not mere rhetoric. If commercial crews refuse voyages or underwriters yank coverage, physical flows slow down even without a formal blockade declaration.
Still, traders who treat a vague operational announcement as a guaranteed supply cutoff are pricing a worst-case scenario at near-certainty odds. When the actual response turns out to be calibrated, localized, or delayed, front-month spikes often bleed off faster than late buyers expect.
Addressing the Questions Traders Keep Getting Wrong
"Will shipping strikes automatically send oil prices soaring?"
No. They send volatility soaring first, and price only follows if physical supply tightens or freight and insurance costs become prohibitive for enough cargoes.
A strike on a vessel can spike prompt futures and war-risk insurance quotes within minutes. If no major export terminals go offline and tankers continue loading and transiting—even with rerouting, escorts, or higher premiums—the market often transitions from panic to repricing the actual barrel count lost. If the barrel count lost is small or temporary, algorithms and momentum traders who chased the breakout frequently get trapped when physical buyers refuse to chase.
"How should currency and macro traders read this alongside commodities?"
Stop treating every Middle East flare-up as a simple "buy crude, sell USD" or "buy USD, sell crude" trade. Those correlations break down depending on which transmission channel dominates:
- Inflationary supply shock: If energy prices stay elevated long enough to threaten headline inflation and central bank rate cuts, bond yields and rate differentials can support the U.S. dollar even while risk assets wobble.
- Safe-haven vs. energy-exporter dynamics: Currencies of net energy importers face terms-of-trade pressure when energy spikes, whereas major exporters and reserve currencies react to shifting global growth and rate expectations.
- Positioning unwinds: Often the sharpest intraday move comes not from new macro data, but from leveraged funds cutting cross-asset exposure when implied volatility jumps.
"Is there a clean way to trade geopolitical shipping risk?"
Clean is an illusion in war-risk markets. Spreads widen, gaps happen over weekends, and liquidity vanishes right when you want an exit.
If you insist on participating rather than sitting on your hands, size down dramatically compared to normal technical setups. Use defined-risk structures or smaller notional size that lets you survive a 3% to 5% gap against you without blowing up your account. Better yet, wait for the initial emotional impulse to clear and watch how calendar spreads (front-month versus later-month contracts) behave. A true physical shortage tightens prompt spreads; a pure headline scare often leaves deferred months much calmer.
What Heavyweights Watch While Everyone Else Watches Wires
Seasoned energy economists and institutional commodity veterans—the kind who have lived through Gulf crises, OPEC+ quota battles, and sanctions regimes—look past press statements to hard logistics. Think of figures like Daniel Yergin on historical energy security shocks, or the analytical frameworks used by the International Energy Agency and major physical trading houses: they anchor on inventories, refinery runs, tanker day-rates, and transit times, not cable-news drama.
Imagine a scenario where two merchant vessels report strikes in a key shipping lane on a Tuesday morning, and by Thursday afternoon no major export terminal has halted loading, while tanker rates jump 40% and several operators pause night transits. In that scenario, logistics get messier and costlier, yet global crude inventories do not evaporate overnight. A trader who bought front-month calls at the peak of Tuesday's panic can still lose money if time decay and fading immediate fear crush implied volatility by Friday.
Conversely, imagine a scenario where attacks escalate systematically against port infrastructure or escort operations, forcing sustained rerouting and multi-week delays across tens of millions of barrels of seaborne trade. That is a different animal altogether—one where physical tightness feeds into term structures and refining economics. Telling those two regimes apart early is the whole game.
The Blind Spots of a Contrarian Stance
Being contrarian about geopolitical hype is not a free lunch. It carries real hazards that you have to own upfront:
- Tail risk is nonlinear: A localized incident can snowball into broader regional escalation faster than a sober fundamental model predicts. Being "right on average" does not protect you from an unhedged tail event.
- Timing can hurt even when your thesis is right: Markets can stay irrational and headline-driven longer than a tight stop-loss or margin cushion allows.
- Information lag: Early reports on vessel strikes are frequently incomplete, contradictory, or delayed. Treating early silence as proof that nothing happened is just as dangerous as treating every rumor as Armageddon.
I have seen smart traders get wiped out not because they ignored risk, but because they mocked the market's fear right before the fear became justified. Respect the tail. Respect your position size.
Actionable Rules When Strikes Hit the Tape
Do not trade on adrenaline. Trade on a checklist that forces discipline when everyone else is screaming:
- Check front-to-back spreads before entering outrights: Confirm whether prompt physical tightness is actually building or whether only front-month headline hype is moving.
- Cut leverage before the open or weekend: Gap risk around military announcements punishes over-leveraged accounts immediately.
- Separate vessel incidents from terminal outages: One ship hit is a security and insurance story; sustained export halts are a supply balance story.
- Let the first spike exhaust itself: Chasing vertical candles driven by breaking-news alerts usually puts you at the worst fill price of the session.
The market does not care about your conviction or your political opinions. It only cares about physical barrels, real money, and forced liquidations. Trade what is actually moving—not what the loudest headline wants you to fear.