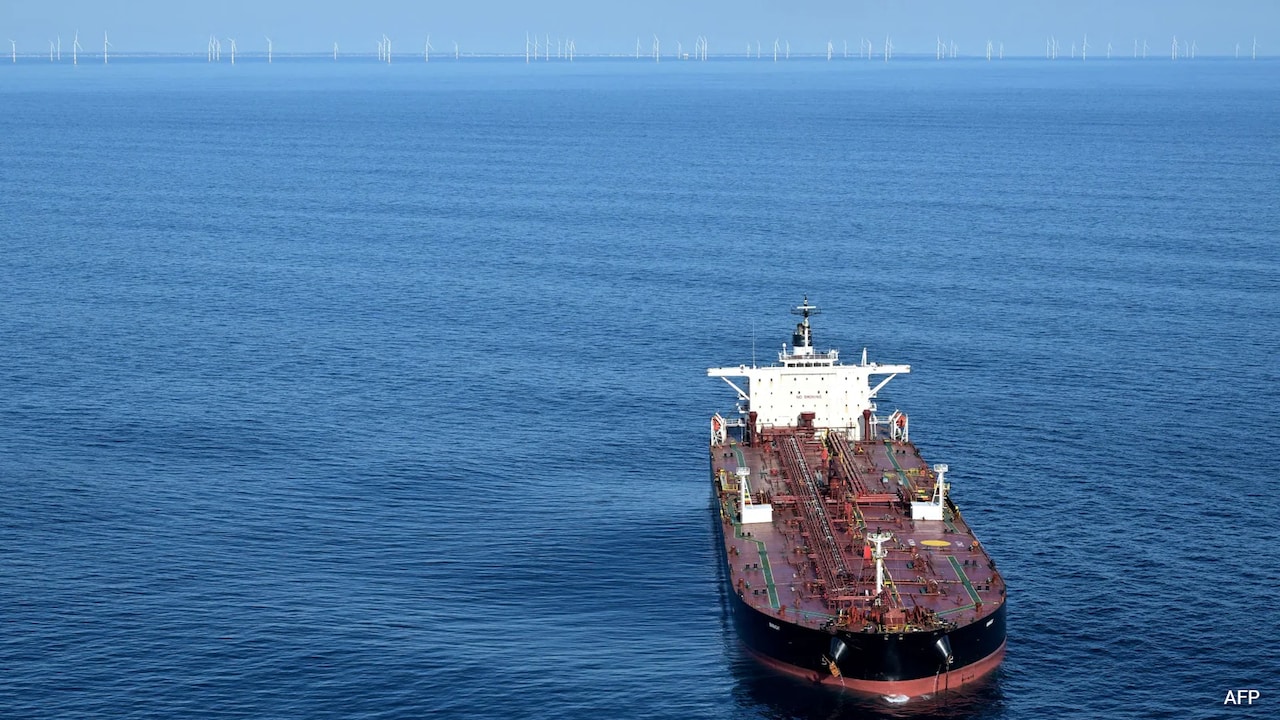
Announcing a bilateral diesel supply deal does not make a refinery cargo discharge at a U.S. terminal. When Washington moved in October 2026 to ease restrictions on Russian diesel following talks between Donald Trump and Vladimir Putin, maritime data quickly exposed a gap between executive policy and commercial execution. Tankers departing Russian ports such as Primorsk faced legal ambiguity, state-level resistance, and reputational exposure—leaving promised U.S.-bound shipments stalled offshore or diverted toward markets like Brazil and Egypt.
To evaluate why a headline supply arrangement stalls on the water, analysts must separate four operational layers: executive authorization vs. statutory and allied sanctions, vessel-level compliance, domestic consumption scale, and reputational risk pricing. Understanding these mechanics explains why a political reversal on fuel imports struggles to move physical barrels into the American supply chain.
Deconstructing the Competitor Narrative
Surface-level coverage of the first Russian diesel tanker heading toward the United States typically frames the story as a binary clash between a political reversal and market outrage. That framing captures the drama, yet it leaves three analytical blind spots unexamined.
The first blind spot is legal layering. An executive waiver or Treasury license covering Russian diesel transactions does not automatically erase statutory prohibitions enacted by Congress, state-level port warnings, or sanctions imposed by the European Union and the United Kingdom on specific tankers. A commercial buyer evaluating a cargo faces overlapping compliance regimes rather than a single green light.
The second blind spot is flow versus stock scale. Headlines treat an initial tanker cargo as a direct antidote to elevated retail diesel prices. In global refined products trading, prices respond to marginal supply balances, refinery runs, and regional inventories across the Atlantic Basin—not to a single vessel whose volume represents a tiny fraction of daily U.S. distillate demand.
The third blind spot is buyer self-rationing. Even when a transaction is legally permissible under a specific exemption, refiners, traders, and port operators price in secondary consequences. Avoiding headline backlash, political scrutiny, and future policy reversals can outweigh a narrow arbitrage discount on a single cargo.
The Four Friction Layers of Cross-Sanctions Fuel Trade
Moving refined petroleum from a sanctioned exporter into a high-compliance importing market requires clearing four distinct hurdles in sequence. A failure at any single layer stops or reroutes the ship.
1. Statutory Overhang and Multi-Jurisdictional Rules
Executive action on energy trade operates inside a dense web of prior legislation, administrative guidance, and foreign sanctions lists. Even when the U.S. government issues an authorization or waiver for diesel shipments, market participants examine whether underlying statutory bans, secondary sanctions risks, or European and British designations on individual ships create exposure.
In maritime logistics, compliance officers rarely rely on verbal assurances or broad political announcements. Legal departments audit charter parties, insurance coverage, banking rails, and vessel histories before committing capital. Where legal ambiguity persists—especially when lawmakers challenge the policy or state officials warn against accepting disputed cargoes—risk-averse counterparties pause.
2. Vessel-Specific Taint and Rerouting Economics
A cargo is only as movable as the hull carrying it. Even if a commodity is permitted under a targeted exemption, a tanker that carries U.S., EU, or U.K. sanctions—or has an opaque ownership and trading history—triggers immediate friction with Western insurers, classification societies, banks, and terminal operators.
Consider a practical trading example. Suppose a trader loads roughly 40,000 metric tons of diesel at a Baltic export terminal for a U.S. East Coast discharge. As the vessel approaches the Atlantic seaboard, terminal operators and buyers weigh legal and political exposure against alternative buyers elsewhere. If a U.S. port or refiner declines the parcel, the ship faces two choices: loiter in transit while awaiting orders, or divert to a market where Russian energy trade faces less domestic political friction, such as Brazil or Egypt.
Rerouting changes the economics immediately:
- Demurrage and waiting costs: Every day a tanker spends drifting or holding off a coast accrues vessel operating and charter costs without generating discharge revenue.
- Freight and voyage adjustments: Shifting from an Atlantic crossing to South America or the Mediterranean alters voyage duration, bunker fuel burn, and laycan scheduling.
- Destination discounting: A cargo rejected by high-compliance buyers often must clear at a steeper discount in a more receptive market to compensate the final buyer for logistical and geopolitical risk.
3. Distillate Market Scale vs. Headline Volumes
Diesel is the workhorse fuel of freight trucking, rail, agriculture, and industrial manufacturing. Because U.S. distillate consumption is massive on a daily basis, individual tanker loads—typically tens of thousands of metric tons—are small relative to domestic throughput.
In refined products markets, retail and wholesale prices are governed by broader structural drivers:
- Crude oil benchmarks and geopolitical risk premiums: Disruptions involving major oil producers or shipping chokepoints lift the underlying cost of crude feedstock across the entire barrel.
- Refinery utilization and maintenance: Planned turnarounds, unplanned outages, and complex hydrocracking or hydrotreating capacity dictate how much ultra-low-sulfur diesel refineries can produce locally.
- Regional inventory levels: Stock builds or draws along the U.S. Atlantic Coast and Gulf Coast determine whether local markets are tight or well-supplied.
A few tankers on the water can shift localized trade flows or signal policy intent, but a single shipment cannot single-handedly reset national pump prices when broader supply constraints remain intact.
4. Reputational Beta and Domestic Political Pushback
Energy trading is not purely an engineering and pricing exercise; it is a visible corporate decision. Refiners, fuel marketers, and port authorities operate under intense public and political scrutiny whenever a transaction touches the war in Ukraine or Russia's export revenues.
When elected officials criticize an import arrangement and civic groups track every departing tanker, the reputational beta of the trade rises. Even if a refiner can capture a temporary margin advantage on a discounted parcel, executives must weigh consumer backlash, brand damage, and the risk that sanctions rules tighten again later. That asymmetry—modest upside on one cargo versus lasting reputational harm—explains why commercial buyers step back even after a federal exemption is announced.
Facts Versus Analytical Hypotheses
Separating verified mechanics from unproven claims keeps any supply-chain assessment grounded.
Known facts include the structural reality that political announcements and sanctions exemptions do not guarantee port acceptance, that individual vessels can face overlapping sanctions designations or state-level pushback, and that tankers can stall offshore or divert to non-U.S. destinations such as Brazil and Egypt while buyers weigh legal and political exposure. It is also established that single tanker shipments represent a small fraction of daily U.S. diesel consumption and that broader market drivers—such as crude oil shocks and refinery balances—exert far greater influence over retail fuel prices.
Educated hypotheses include expecting persistent buyer hesitation on direct U.S. discharges as long as statutory ambiguities, allied sanctions on specific hulls, and domestic political opposition remain unresolved. Another plausible hypothesis is that Russian diesel linked to these flows is more likely to clear through third-country trade channels or alternative importing nations than through high-visibility U.S. East Coast terminals, while U.S. distillate prices remain anchored primarily to broader crude and refining fundamentals.
Limits of This Analytical Framework
No analytical model captures every variable in wartime commodity logistics. AIS ship-tracking signals can be delayed, spoofed, or switched off, and ownership structures can be obscured behind complex registries or mid-voyage transfers. In addition, legal interpretations and regulatory guidance can shift rapidly when executives, lawmakers, or foreign partners react to a specific shipment. Treating trade-flow observations as directional indicators of friction—rather than complete proof of a buyer's internal legal file—prevents overinterpreting a single vessel's track.
Strategic Play for Supply-Chain and Market Leaders
Energy buyers, commodity analysts, and policy teams should treat headline diplomatic breakthroughs on sanctioned fuels as conditional policy signals, not immediate physical supply. Before underwriting or pricing cargoes tied to a bilateral energy deal, map the exact legal status of the specific vessel, verify whether state or allied restrictions still constrain discharge, and benchmark any potential volume against daily regional distillate demand rather than political promises. For commercial operators seeking relief from tight diesel markets, durable margin and supply stability will come from tracking refinery availability, crude risk premiums, and non-sanctioned Atlantic supply routes rather than betting on politically contested cargoes that can reverse course mid-ocean.