Cold rain hits the glass facade of the Eurotower in Frankfurt like gravel thrown by an impatient hand. Inside, high above the River Main, the air smells faintly of espresso, damp wool, and the quiet, suffocating pressure of three hundred and fifty million lives.
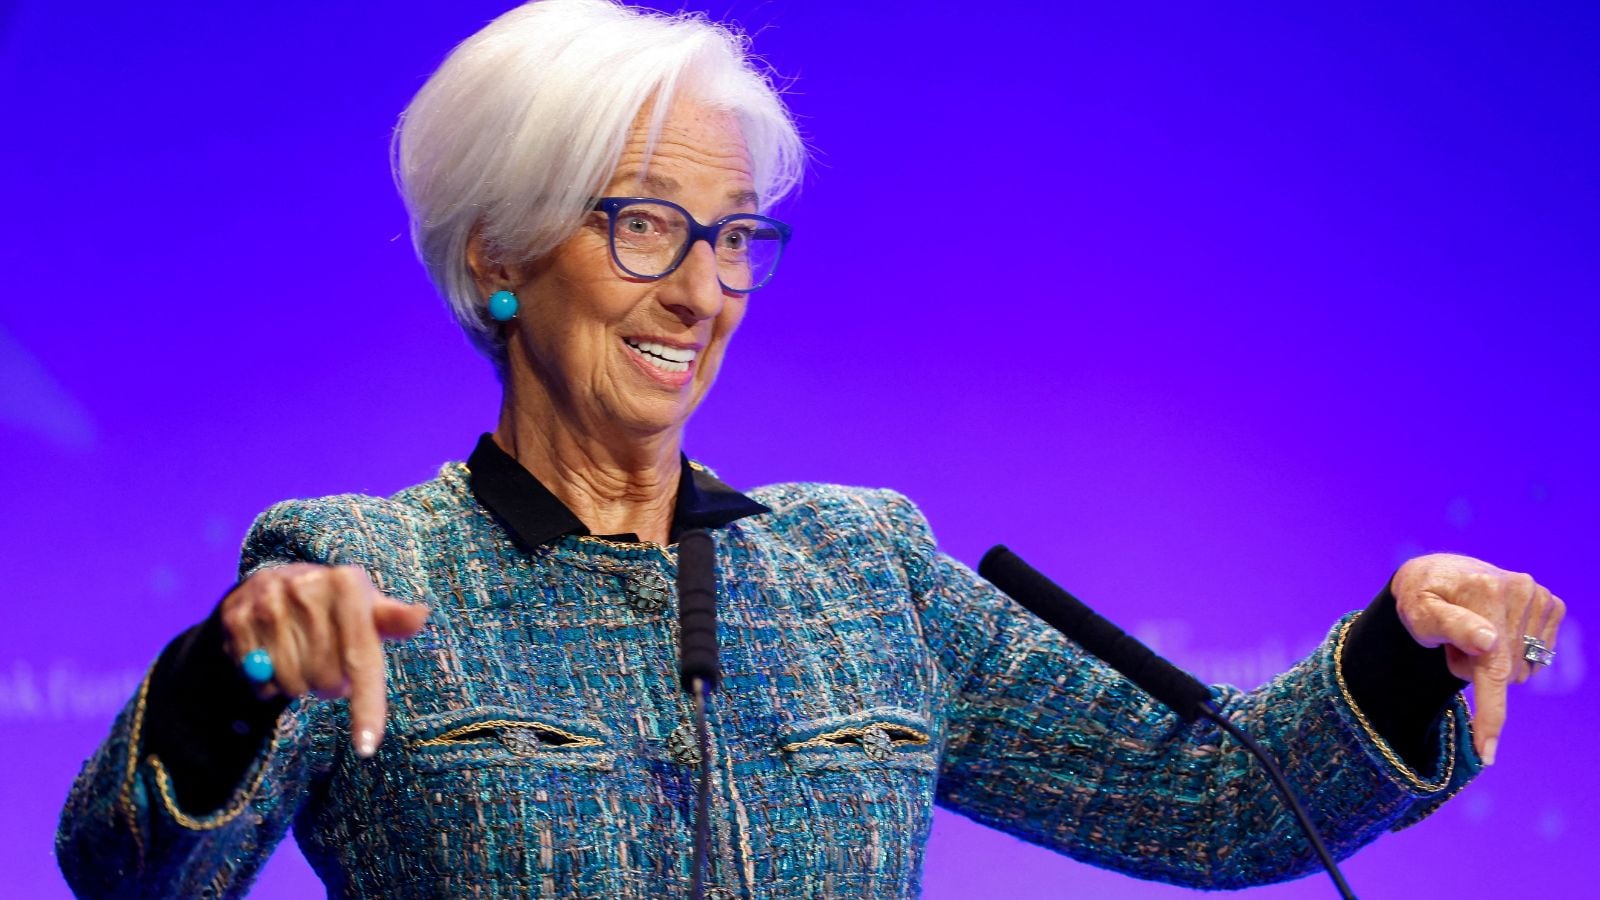
For seven years, Christine Lagarde has stood at the center of that glass room, trying to hold a continent together with words, basis points, and sheer force of personality. Now, a calendar date sits quietly on the desks of finance ministers from Lisbon to Tallinn.
February 7, 2027.
To the trading floors in London and New York, it is just another headline scrolling across a terminal in sterile amber text. ECB President Lagarde to step down on 7 February 2027. Algorithms digest the syntax in milliseconds. Bond yields twitch by a fraction of a percent. Analysts adjust their spreadsheets, pour another cup of coffee, and move on to the next data release.
They treat it like a scheduled maintenance window on a machine.
They are wrong. When the person who guards the value of your money decides to walk away early, the tremor doesn't stay inside the marble lobbies of central banks. It travels down into the soil of everyday life, showing up months later in the price of a loaf of sourdough in Lyon, the interest rate on a starter home in Madrid, and the quiet panic of a small business owner in Stuttgart staring at a loan renewal notice.
The Architecture of a Departure
To understand why February 7, 2027, carries such a heavy, unspoken charge, you first have to look at the clock. Christine Lagarde’s eight-year non-renewable term at the European Central Bank was originally meant to run until October 31, 2027. Leaving in February shaves nearly nine months off the end of her mandate.
In the hyper-ritualized world of central banking, nobody leaves nine months early without a reason. Central bankers are creatures of predictability; they view surprise as a virus. When Mario Draghi left in 2019, he stayed until the very last second of his term, handing over the gavel on Halloween night. Jean-Claude Trichet did the same in 2011.
Why break the rhythm now?
Consider a hypothetical character—let us call him Lukas, a forty-two-year-old toolmaker in southern Germany. Lukas doesn't read the minutes of the ECB Governing Council. He doesn't care about the nuances of the Transmission Protection Instrument. What Lukas cares about is the forty-five employees on his payroll and the credit line he uses to buy steel from northern Italy.
When Lukas hears that the head of the European Central Bank is stepping down ahead of schedule, his stomach tightens. Not because he loves Lagarde’s monetary policy—in fact, he cursed her name through the brutal rate hikes of 2022 and 2023—but because an early exit in Frankfurt rarely happens in a vacuum. It smells like political choreography.
Look at the European political calendar for 2027. In the spring of that year, France goes to the polls for a presidential election that promises to be one of the most volatile in the Fifth Republic's history. If Lagarde had stayed until October 2027, the race to replace her would have collided head-on with a potentially fractured French government and a paralyzed European Council. By stepping aside in February, she opens the window for current European leaders—including Emmanuel Macron, before his own term expires—to negotiate her successor while the political plumbing still works.
It is a strategic retreat designed to prevent a vacuum. Yet, in trying to shield the institution from future chaos, the early exit inadvertently exposes just how fragile the European project still feels beneath its polished surface.
Seven Years in the Eye of the Storm
I remember sitting in a cramped café in Athens back in 2015, watching people line up outside ATM machines under a merciless July sun. You could smell the fear in the street—a sharp, metallic tang that comes when people realize the plastic card in their wallet might suddenly stop working. At the time, Lagarde was running the International Monetary Fund in Washington, dressed in immaculate Chanel jackets, speaking in that measured, velvety cadence that made even the harshest austerity demands sound like reasonable advice from a stern aunt.
Many Europeans never forgave her for those years. When she arrived in Frankfurt in November 2019 to take over the ECB, critics immediately pointed out a glaring anomaly. She was not an economist. She had never published a paper on monetary velocity or inflation targeting. She was a lawyer, a former corporate litigator in Chicago, and a politician.
"She's a diplomat, not a technician," the skeptics muttered in the financial press.
Then the world caught fire.
Four months after she unpacked her boxes in Frankfurt, a novel coronavirus shut down northern Italy, then Spain, then the entire continent. Factories went silent. Borders slammed shut. Markets went into freefall, threatening to tear the eurozone apart at the seams just as the sovereign debt crisis had nearly done a decade earlier.
Lagarde stumbled at first. In March 2020, during a press conference that still makes central bank communications officers wince, she remarked offhandedly that the ECB was not there to "close spreads" between German and Italian borrowing costs. Italian bond yields exploded upward within minutes. It was a rookie mistake, the kind of unscripted candor that sends tremors through trillions of euros in debt.
She learned fast. Within days, the ECB unleashed the Pandemic Emergency Purchase Programme, a massive wall of liquidity that bought European governments the breathing room they needed to keep hospitals running and workers paid.
And then, just as the pandemic fog began to lift, Russian tanks rolled into Ukraine. Energy prices went vertical. Inflation, which Europe had spent a decade trying to coax above two percent, suddenly roared past ten percent.
Imagine trying to steer a twenty-car train down a mountain pass when half the cars are on fire and the other half have frozen brakes. That is the ECB Governing Council. On one side sat the northern hawks from Germany, the Netherlands, and Austria, demanding aggressive interest rate hikes to crush inflation before it became permanent. On the other sat the southern doves from Italy, Spain, and Greece, terrified that rapid rate hikes would bankrupt their heavily indebted governments and throw millions out of work.
Lagarde’s real job was never about running regressions on a computer. It was about locking twenty-six strong-willed central bank governors in a room and refusing to let them leave until they agreed on a single number. She brought a lawyer's patience to a room full of warring economists. Between July 2022 and September 2023, she engineered ten consecutive interest rate increases, taking the deposit rate from negative territory up to four percent—the fastest tightening cycle in the bank's history.
It hurt. Every single tick upward meant less money in the pockets of families with variable-rate mortgages in Dublin and Madrid. It meant delayed investments for small manufacturers like our hypothetical toolmaker Lukas. Yet, slowly, painfully, inflation came back down toward the two percent target without shattering the single currency.
The Invisible Hand on Your Kitchen Table
Why does the identity of the person sitting in that Frankfurt office matter so much to someone who never trades currencies or bonds?
Think of a central bank as the thermostat in an old, poorly insulated house. In a normal house, one thermostat controls the temperature for every room. In the eurozone, twenty-one different countries share the exact same thermostat, even though some rooms have drafty windows, some sit directly over the furnace, and nobody agrees on whether sixty-eight degrees is freezing or comfortable.
If the person adjusting the dial turns it up too fast, the people near the windows freeze. Turn it down too low, and the people over the furnace suffocate.
When Lagarde steps down on February 7, 2027, the battle over who gets to touch that dial next will become fierce, personal, and deeply political.
Consider what happens next. For the past fifteen years, the ECB has been led by figures who favored flexibility—first Mario Draghi, who promised to do "whatever it takes," and then Lagarde, who built consensus around massive bond-buying programs whenever crises struck.
Now, the northern countries believe it is their turn. Names like Joachim Nagel, the president of Germany’s Bundesbank, or Klaas Knot, the seasoned Dutch central banker, linger in the hallways of Brussels and Berlin. Alternatively, figures like Pablo Hernández de Cos of Spain or Fabio Panetta of Italy represent a continuation of the pragmatic, growth-conscious school.
If a strict monetary hawk takes the chair in February 2027, the entire atmosphere in Frankfurt shifts overnight. The tolerance for high government debt shrinks. The willingness to rescue struggling bond markets tightens. For a young couple in Lisbon trying to buy their first apartment, or an entrepreneur in Milan looking for financing to expand a workshop, that shift in tone translates directly into higher monthly payments and stricter bank lending standards.
Conversely, if the next president leans too heavily toward accommodating government spending, the specter of inflation—that silent thief that erodes savings accounts and pensions while you sleep—begins creeping back toward the door.
The Vulnerability Behind the Podium
There is a human truth we rarely admit when we talk about economics: nobody actually knows for sure if the machine will hold together until the next crisis tests it.
Economics often masquerades as physics, dressed up in Greek letters and stochastic calculus, pretending that human fear and greed can be neatly boxed into equations. They cannot. At its core, money is nothing more than a shared hallucination—a collective agreement that a piece of paper or a digital entry in a ledger holds value because we trust the institution standing behind it.
Lagarde understood that theater is half the job. Watch footage of her press conferences. Notice the deliberate pause before she answers a hostile question. Notice the way she uses her hands, the careful, almost hypnotic repetition of key phrases like "data-dependent" and "meeting-by-meeting." She was projecting calm in a room where everyone knew the margin for error was razor-thin.
Yet even the best theater has limits. By 2026, the cracks in Europe's economic model had become impossible to paper over with clever phrasing. Structural stagnation in Germany, yawning debt deficits in France and Italy, an aging workforce, and relentless industrial competition from the United States and China have left the continent squeezed from every direction.
A central bank cannot fix broken pension systems. It cannot build semiconductor factories, lower energy costs permanently, or resolve political deadlocks in Paris and Berlin. Lagarde spent years pleading with European governments to pass structural reforms, warning them again and again that monetary policy could only buy them time—it could not buy them a future.
Mostly, they ignored her. They took the low interest rates she provided during the crisis years and spent the money on short-term political survival rather than long-term renewal.
Leaving in February 2027 feels, in some quiet, unspoken way, like an admission of that reality. You can only hold the roof up with your bare hands for so long before someone else has to take a turn, or the walls themselves have to be rebuilt.
The Last Days in Frankfurt
Picture the Eurotower on a crisp morning in early February 2027.
Outside, the winter mist clings to the skyscrapers of Frankfurt's banking district, blurring the sharp edges of glass and steel. Inside the executive suite on the fortieth floor, boxes are packed. The framed photographs, the heavy legal volumes, the small mementos from Washington and Paris are cleared from the shelves.
Down on the trading floors of London, Paris, and Singapore, screens flicker with fresh headlines about whoever has been chosen to take her seat. Analysts write thousands of words dissecting the newcomer’s past speeches, searching for clues about whether the euro will rise or fall, whether bond yields will steepen or flatten.
And far away from the terminals, in a cramped workshop in southern Germany, Lukas unlocks his front door at six in the morning, switches on the fluorescent lights, and listens to the low hum of his machines warming up for the day. He checks the price of steel on his computer. He checks the balance in his business account. He wonders, just for a second, if the new voice coming out of Frankfurt will make his life a little easier or a little harder this year.
He doesn't know the name of the person who will sit in that chair tomorrow. He only knows that when the weather changes in Frankfurt, the rain always reaches his roof eventually.