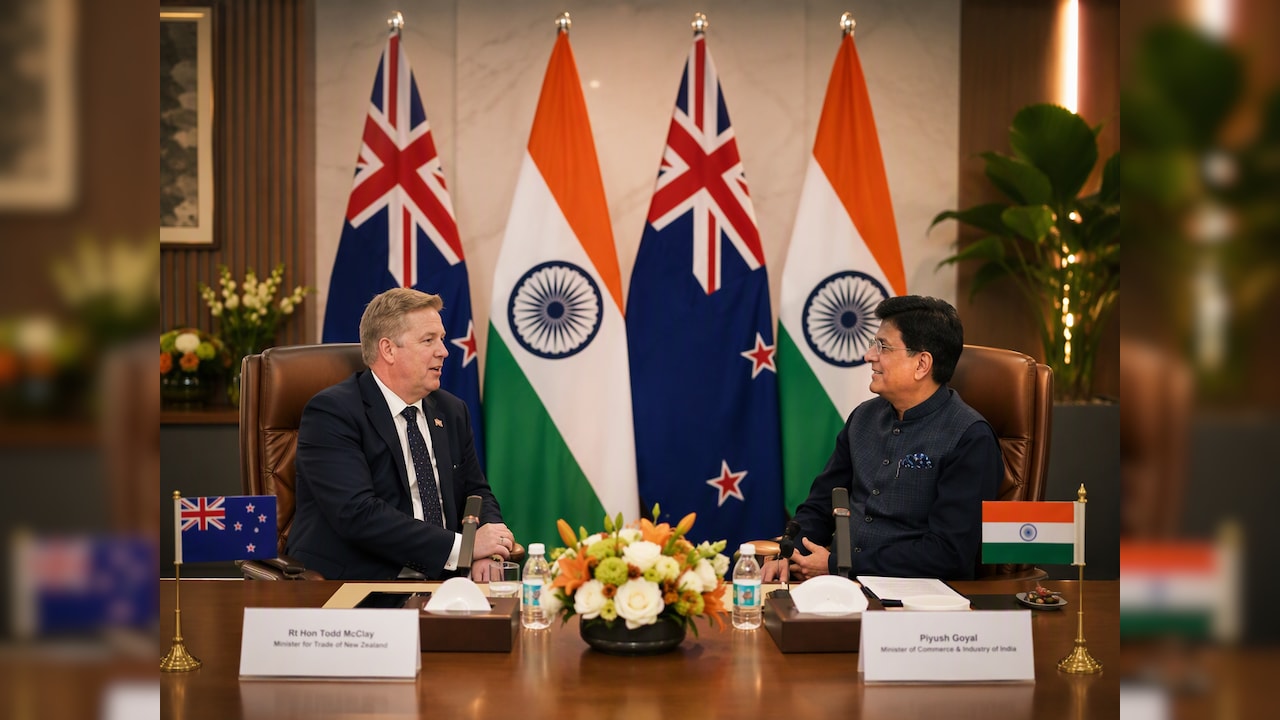
Headline coverage of the Jio Platforms initial public offering frames the listing as a binary showdown: a ~$108 billion valuation test against Elon Musk's public push to bring Starlink into India. That framing gets the drama right and the economics backward. The real tension does not sit inside a headline clash between Mukesh Ambani and Musk. It sits inside the gap between a ~33x to 34x earnings multiple priced on terrestrial scale and a capital-intensive orbital competitor trying to enter a market where mobile data costs roughly eight cents per gigabyte.
Competitor commentary on the listing generally relies on three loose claims: that the ~$108 billion offer valuation proves market faith in India's digital pivot, that Musk's public complaints about regulatory delays threaten Jio's moat, and that low-cost pricing will decide who wins connectivity. None of those claims separate balance-sheet mechanics from competitive physics. A rigorous analysis has to map the underlying logic of that coverage, expose where cause and effect break down, and re-evaluate the listing through unit economics, spectrum and orbital physics, and regulatory chokepoints.
Deconstructing the Competitor Narrative
Standard coverage of the Jio Platforms IPO organizes the story around a single narrative arc: an incumbent telecom giant lists at a record valuation while a global disruptor knocks on the door. Translated into analytical components, that narrative rests on three pillars:
- The Valuation-as-Faith Pillar: Treating the ~$108 billion IPO valuation (around ₹10.3 lakh crore at the ₹1,119 issue price) and the subsequent ~21% listing jump toward ₹1,358 as a direct vote of confidence in India's digital economy and Reliance's pivot away from traditional energy.
- The Rivalry-as-Threat Pillar: Treating Musk's public criticism over licensing and clearance delays—and his pledge to price Starlink affordably—as an immediate commercial threat to Jio's core business.
- The Price-War Pillar: Assuming that because Jio disrupted Indian telecom with ultra-cheap data and Musk has lowered prices in select markets, a head-to-head price war over everyday connectivity is inevitable.
The first analytical flaw in that logic is treating an IPO price as proof of future returns rather than a clearing price set by supply, demand, and allocation structure. Jio Platforms reported FY26 revenue from operations of ₹1,46,885 crore and net profit of ₹30,049 crore, putting the ₹10.3 lakh crore offer valuation at roughly 33.6x to 34.3x earnings—and pushing higher on first-day trading. A high multiple does not validate the thesis by itself; it transfers the burden of proof onto multi-year earnings compounding.
The second flaw is confusing noise in public disputes with direct revenue substitution. Even when Starlink secures final clearances, satellite broadband and cellular/fiber networks do not operate on identical cost curves or capacity limits. Treating every sharp exchange on social media as a direct hit to Jio's 533.3 million subscriber base skips the intermediate operational steps required to win an Indian household or mobile user.
The Cost Function of Terrestrial Scale vs. Orbital Broadband
Comparing Jio Platforms and Starlink requires separating two fundamentally different cost functions. Jio's economics are governed by high upfront fixed network density paired with low marginal cost per gigabyte across massive user volume. Once fiber, towers, and spectrum are deployed in dense urban and semi-urban clusters, serving additional bytes across hundreds of millions of connections scales cheaply, supporting Indian mobile data pricing around eight cents per gigabyte.
Starlink's economics run on a different physics constraint: orbital capacity density and user-terminal hardware. Low-Earth-orbit satellites excel at reaching remote, underserved, or hard-to-wire locations where laying fiber or erecting dense cellular sites is slow or uneconomic. In dense cities, however, orbital beam capacity is shared across a finite geographic footprint. If too many high-bandwidth users cluster in the same cell, throughput per user drops unless gateway capacity, spectrum, and satellite density scale faster than local demand.
Pricing highlights that structural divide. Starlink reported an average revenue per user (ARPU) of $66 per month in Q2 2026 while carrying heavy capital spending—about $18.4 billion in that quarter, largely directed toward AI compute—and a net loss of $541 million. Management has indicated that entering lower-income or emerging markets could pull ARPU down over time while relying on subscriber growth to offset lower per-user realization. Yet even an aggressive discount from a $66 baseline sits in a completely different tier from mass-market Indian mobile data.
The practical overlap is narrower than headline rivalry suggests. Starlink's sharpest collision with Jio is not mass-market mobile voice and data; it is fixed and 5G fixed-wireless home broadband, where Jio holds 42.6% of fixed lines and 77.5% of 5G home wireless. In dense metros, fiber and 5G fixed wireless hold a structural cost and capacity advantage. In low-density districts, enterprise backup, maritime/aviation links, and remote sites, satellite connectivity fills gaps that terrestrial wireline reaches slowly or not at all.
Why Capital Allocation and Regulation Shape the Real Battlefield
Public commentary often treats regulatory clearance as a simple finish line: once approved, competition begins. In practice, three structural mechanisms govern how fast value accrues to Jio or erodes toward rivals:
- Balance-Sheet De-leveraging via Fresh Equity: Jio's offering was structured as a fresh issue raising ₹30,213 crore, with up to ₹27,500 crore—roughly 91% of proceeds—earmarked to repay or prepay borrowings at Reliance Jio Infocomm. Lowering debt reduces interest drag and strengthens balance-sheet flexibility ahead of ongoing capital commitments, even as public shareholders absorb a ~34x earnings multiple.
- Sovereign Security and "Kill Switch" Governance: Satellite communications touch national security, lawful interception, and sovereign control. Rival incumbents, including Airtel chairman Sunil Bharti Mittal, have pointed to Ukraine—where SpaceX's military Starlink service was throttled for ten days in October—to argue that operational control or any "kill switch" authority must sit within India. Both SpaceX and Reliance's own satellite ambitions face security and clearance gates, making regulatory sovereignty a central gating factor rather than a side note.
- Ecosystem Monetization Beyond Raw Connectivity: Telecom connectivity alone faces long-term margin pressure everywhere as data consumption rises faster than tariffs. The bull case for Jio's valuation rests on converting massive distribution across mobile and broadband into higher-margin digital, enterprise, and adjacent services—not merely defending commodity gigabytes.
The first limitation of a bull thesis on Jio is multiple compression risk. If earnings growth slows from recent ~18% annual expansion toward ~10% due to softer tariff hikes, higher capex, or stiffer competition, a market that paid ~34x earnings can re-rate the stock downward even if the company remains profitable and dominant.
The second limitation applies to the bear thesis built around Musk's entry. Even if Starlink wins clearance and prices aggressively relative to global norms, scaling dish logistics, customer support, and localized plans in India while managing multi-billion-dollar capex elsewhere limits how quickly it can dent Jio's core cash flows.
What Investors and Operators Should Watch Next
Several empirical signals will separate real fundamental shifts from posturing over the coming quarters:
- ARPU and Tariff Trajectory: Track whether Jio expands average revenue per user through plan upgrades and enterprise/digital mix without triggering subscriber churn, and watch how quickly profit growth tracks against the ~18% baseline implied by FY24–FY26 performance.
- Home Broadband Share in Urban vs. Rural Pockets: Monitor Jio's share of fixed and 5G home wireless connections alongside any eventual commercial rollout of satellite terminals in non-metro areas.
- Security Clearance Terms and Local Control Rules: Look closely at the exact compliance conditions attached to satellite approvals—specifically data localization, lawful interception, and sovereign override mechanisms—rather than headlines about who complained loudest.
For institutional investors pricing Jio after its listing surge, the disciplined play is to treat the ~$108 billion-plus valuation as a growth-and-execution contract, not a finished verdict. Underwrite positions against conservative earnings growth and lower terminal multiples rather than assuming orbital competition will either collapse Jio's moat overnight or fail to carve out a profitable niche at the high end and in underserved geographies.