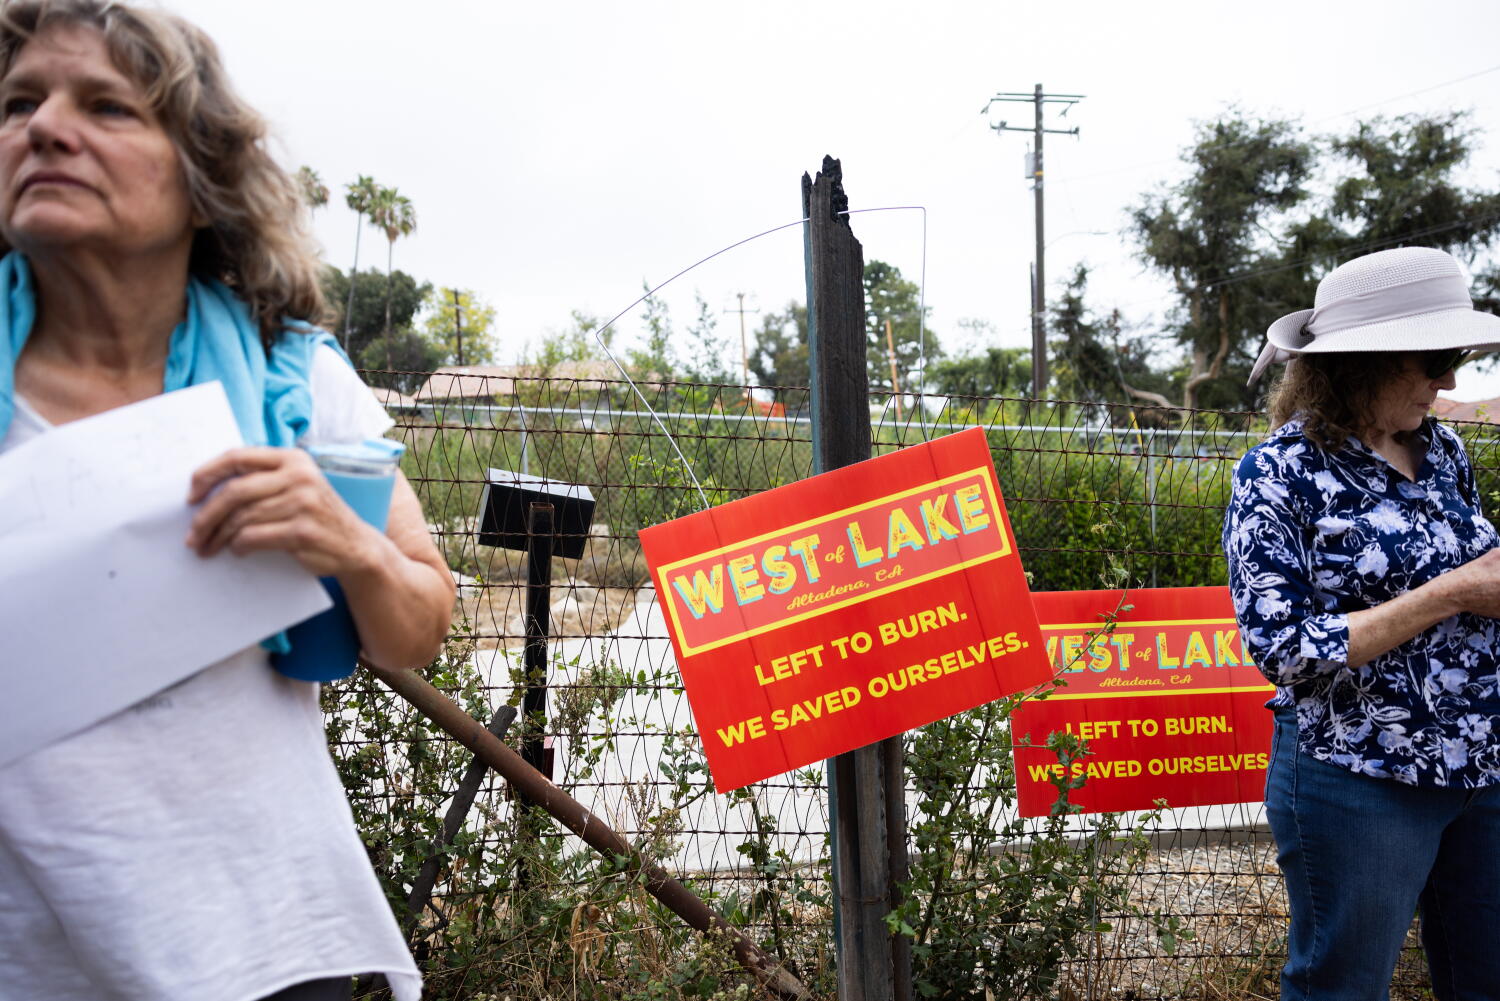
You fight for months to get an insurer to cut a check after your home burns down, and then your mortgage lender locks the money in a vault. That is the gut punch hitting hundreds of Los Angeles wildfire survivors right now.
In mid-October 2026, California's Business, Consumer Services and Housing Agency and the Department of Financial Protection and Innovation (DFPI) ordered roughly 800 mortgage lenders and servicers to account for how they've handled insurance proceeds for survivors of the devastating January 2025 wildfires. Regulators demanded specific numbers covering payouts received, amounts released, disbursement timing, and reasons for funds still withheld as of September 30, 2026. Meanwhile, you can read other stories here: The Phantom Discount at the Pump.
Here is the core issue behind the crackdown. When a mortgaged home is damaged or destroyed, insurers typically make checks payable to both the homeowner and the lender—or route funds into a lender-controlled loss draft or escrow account—so the lender can protect its collateral during repairs or rebuilding. In theory, that protects everyone. In practice, survivors say endless paperwork loops, contractor inspection disputes, and unexplained freezes on L.A. wildfire insurance payouts have stalled rebuilding across neighborhoods scorched by the Palisades and Eaton fires.
How Mortgage Lenders Control L.A. Wildfire Insurance Payouts
Most homeowners don't realize how much leverage a mortgage servicer holds once a catastrophe hits until they try to pay a contractor. Even when an insurer approves a claim, the check doesn't just drop cleanly into a family's checking account to start framing a new house. To see the full picture, check out the excellent report by The Economist.
When your mortgage contract requires lender oversight of insurance proceeds, the servicer usually places large claim disbursements into a restricted loss draft or escrow account. From there, money is typically dribbled out in draws as work progresses. Sounds reasonable on paper. Yet when a home is wiped out completely or requires heavy structural work, draw-based bottlenecks collide with brutal realities: contractors demand upfront deposits or milestone payments, municipal permits take time, and lenders often question contractor invoices or progress percentages.
Joy Chen, executive director of Every Fire Survivor's Network—a nonprofit led by survivors of the January 2025 Los Angeles-area fires—put the frustration plainly: "Every day that they wait to pay us, they're collecting interest. And that interest really belongs to us." Annie Barbour, a recovery coordinator with United Policyholders, pointed out the human toll of those bottlenecks, noting that the longer families stay out of their homes, the longer the emotional turmoil drags on.
And let's be honest: part of the confusion comes from how complicated recovery paperwork gets. A homeowner might be dealing with an insurer's lowball estimate on one track while fighting a mortgage servicer over releasing money that has already been paid on another. Mixing those two battles up in a single email thread is a classic mistake that slows everything down.
What California Regulators Are Actually Investigating
The October 2026 reporting order didn't come out of nowhere. DFPI had already logged more than 160 complaints about payment delays or related issues since January 2025, following earlier pressure from Governor Gavin Newsom over slow disbursements. DFPI Commissioner KC Mohseni warned that the agency can pursue enforcement—including potential fines—against banks, credit unions, and lenders that unnecessarily stand in the way of rebuilding homeowners.
According to legal analyses of the directive, state officials targeted three specific trouble spots in how institutions handle escrowed or held insurance funds:
- Slow releases after conditions are met: Institutions failing to release proceeds within 10 business days of a request once mortgage conditions are satisfied.
- Missing fast-track reviews: Lenders lacking expedited appeal pathways when borrowers dispute a hold or draw rejection.
- Excessive retention relative to loan balances: Firms holding escrowed insurance proceeds that exceed the remaining unpaid mortgage balance.
Notice how sharp that third point is. When a lender holds huge sums well above what's even owed on the note, "protecting collateral" starts looking a lot like hoarding cash at the borrower's expense. That said, a regulatory probe isn't the same thing as a court ruling against a specific bank, and individual loan agreements still set baseline terms around inspections and disbursements.
Interest Rules, AB 493, and Rebuilding Financing Gaps
If your payout sat frozen with a lender, interest is one of the first things to check. Governor Newsom signed Assembly Bill 493 into law on August 29, 2025, as urgency legislation taking immediate effect. Under AB 493, covered financial institutions holding hazard insurance proceeds in loss draft accounts for one- to four-unit residential properties in California must pay borrowers at least 2% simple annual interest on those funds, credited at least annually or when the account closes, without fee gimmicks that eat that rate down.
There are important nuances here that trip people up:
- Start dates matter: For funds already held when the law took effect on August 29, 2025, interest accrual starts from that effective date rather than automatically running back to the day of the fire.
- Exemptions exist: Certain statutory rules and account structures—such as non-bank financial institutions required to use non-interest-bearing trust accounts—have specific exemptions or parameters, so you shouldn't assume every servicer operates under identical rules.
- Interest isn't a magic deadline: Earning 2% doesn't automatically force a lender to approve a construction draw tomorrow.
At the same time, cash flow on a rebuild involves more than just unlocking old policy checks. California also rolled out state-backed rebuilding support—such as California Housing Finance Agency (CalHFA) construction financing tools where reservations opened in September 2026 for eligible qualifying disasters—designed to help bridge construction lending gaps for qualifying primary residences. Still, financing programs and insurance payout releases solve different pieces of the puzzle. Even with construction credit available, a borrower still needs clear visibility into what insurance money is sitting in escrow, when draw milestones trigger, and how much new debt the finished project will require.
Practical Steps If Your Lender Is Holding Payouts
If you're dealing with a lender-held insurance check or stalled draw right now, don't rely on vague phone calls with general customer service reps. They're rarely the ones with authority to fix a disbursement bottleneck.
Start by separating your insurer file from your lender file. Pull the insurer's written payment breakdown showing exact dollar amounts, coverage categories (dwelling, contents, additional living expenses), payees, and issue dates. An adjuster's estimate isn't proof a check was cut, and a check isn't proof the lender posted or released it.
Next, get your mortgage servicer's complete transaction log and written draw/release checklist. Whenever you submit a contractor invoice, permit, or inspection request, send it in writing and log the exact date sent, who asked for it, and any pushback you get. Keep separate records of real financial fallout—like a contractor putting your project on hold in writing or extra temporary housing bills—without lumping unspent future estimates in with money already out of pocket.
Finally, ask your servicer in writing for an accounting of your loss draft or escrow balance, how any required AB 493 interest is being calculated, and the exact reason any funds remain held. If you hit a wall or suspect improper delays, filing a complaint with California's DFPI puts your experience on the regulatory record—just keep in mind that a state investigation looks at systemic practices and doesn't automatically replace individual legal or contract remedies for your specific loan.
Take a hard look at your lender's last written payout ledger today, flag any unverified hold or missing interest credit, and put your next release demand in writing with exact dates attached.