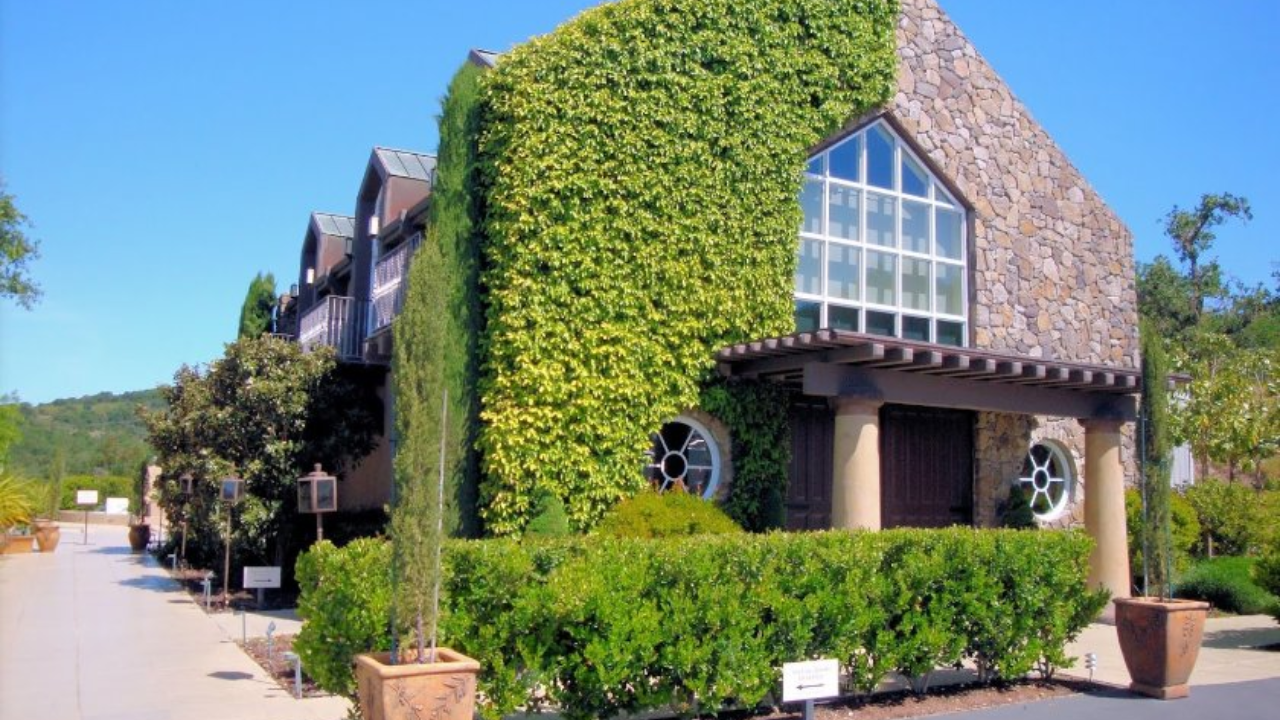
Everyone loves a romantic story about a family pulling themselves from the ashes. The media adores the narrative of multi-generational vintners rebuilding their estate after a catastrophe, pouring thirty million dollars into a state of the art hospitality palace, only to get crushed by thirty-seven million dollars in debt a decade later. It makes for tragic headlines. It triggers sympathy. It plays right into the lazy consensus that climate volatility and predatory lenders are destroying the heritage of wine country.
It is complete nonsense. Read more on a connected topic: this related article.
The story of that Napa winery is not a tragedy of bad luck. It is a masterclass in financial delusion. I have watched boutique estate owners burn through capital for two decades because they treat agriculture like a luxury lifestyle brand while pretending their balance sheet runs on hope. When you sink thirty million dollars of uninsured or under-insured capital replacement cost into a high fire-risk zone without factoring carrying costs, you are not preserving a legacy. You are playing Russian roulette with a thirty-year interest rate cycle.
Let us dismantle the comforting lies people tell themselves about agricultural debt, property values, and the fatal math of modern wine estates. More reporting by Forbes delves into comparable views on this issue.
The Valuation Mirage That Fools Estate Owners
The fundamental failure of the modern winery business model is a profound misunderstanding of asset-rich and cash-poor realities. Vintners look at their land value surging to half a million dollars an acre and assume they are wealthy. They treat paper appreciation as a substitute for operational cash flow.
When a wildfire turns a winery to charcoal, insurance payouts rarely match replacement costs once local building codes, modern seismic mandates, and environmental mitigation requirements are factored into the architectural footprint. Vintners take out massive construction loans assuming that tourism bounce-back will cover ballooning debt service. They build thirty-thousand-square-foot limestone Taj Mahals to sell fifty-dollar cabernet tastings, expecting tasting room traffic to service nine-figure leverage.
That math stopped working twenty years ago.
Consumer preferences have shifted. Direct-to-consumer sales are flatlining for mid-tier luxury labels because millennials and Gen Z do not drink massive, heavily oaked cabernet the way their parents did. They want low-intervention wine, alternative packaging, or they are simply drinking less alcohol altogether. Yet, legacy estates keep doubling down on structural overhead, treating marble tasting bars and commercial kitchens as fixed costs that will magically pay for themselves.
When a winery racks up thirty-seven million dollars in debt against a distressed asset, the lenders are not villains for calling the notes. The owners are the architects of their own destruction for building a business model that required perpetual economic tailwinds just to break even.
The Flawed Logic of Rebuilding Identical Footprints
Another sacred cow in agricultural finance is the compulsion to rebuild exactly what was lost, only bigger and shinier. When a facility burns down, the emotional response overrides economic rationality. The family wants to honor the ancestors. They want the new visitor center to be a monument to resilience.
This is commercial suicide.
Resilience in agriculture does not mean pouring concrete into the exact same path of a wildfire corridor. True risk management requires contraction, diversification, and minimalist infrastructure. If you are operating in a high-hazard zone, your capital expenditure should prioritize fire-hardening, defensible space, remote-storage production facilities, and lean supply chains.
Instead, prestige estates spend millions on aesthetic vanity projects designed to impress wine-club members who care more about Instagram backdrops than the actual fermentation vessel. They over-build processing capacity, finance custom stainless-steel tanks they only use three months out of the year, and load up on debt to fund hospitality experiences that lose money on every pour once labor and overhead are calculated.
When the market corrects—and agricultural luxury markets always correct—the fixed overhead crushes them. The thirty-seven million dollar debt figure is merely the symptom. The disease is hubris disguised as heritage.
The Dangerous Myth of Government and Lender Bailouts
There is a pervasive entitlement running through wine country that assumes prime agricultural land is too culturally significant to fail. Estate owners frequently lobby for special tax relief, low-interest state-backed disaster loans, and regulatory exemptions that allow them to kick the can down the road.
This creates a moral hazard. It encourages operators to ignore fundamental risk modeling because they believe someone will catch them when they fall.
Lenders are finally waking up to this delusion. Commercial banks are tightening underwriting standards for vineyard properties in designated high-risk fire zones. Insurance carriers are either pulling out of California entirely or pricing policies so aggressively that premiums equal a second mortgage.
This is not a conspiracy against agriculture. This is reality reasserting itself after decades of artificially suppressed risk pricing. If an insurance carrier refuses to underwrite your property at an economically viable rate, it is the market telling you that human habitation and heavy industrial hospitality infrastructure do not belong in that specific geographic location. Ignoring that signal by taking on private equity debt or high-interest bridge loans is not bravery. It is financial illiteracy.
What Real Survival Looks In Wine Country
If you want to survive the next decade in the wine business, you have to strip away the romance and look at the ledger like an industrial manufacturer.
Cut your physical footprint in half. Move your hospitality off-site to urban tasting rooms or digital-first models that do not require million-dollar rural real estate to function. Stop treating your production facility as a country club. Renegotiate your debt structures before the bank does it for you, even if that means selling off parcels of land to de-leverage.
The romantic era of the self-indulgent family estate living on prestige and debt is over. The ashes are cold, and the banks are done funding nostalgia.