Donald Trump pitched conditional cash payouts—most prominently a $5,000 "Trump dividend" for American adults alongside targeted checks and regulatory or administrative relief—tied directly to Republican control of Congress in the 2026 midterms, yet the fiscal math, legal hurdles, and ballot-box outcome exposed a wide gap between campaign theater and governable policy.
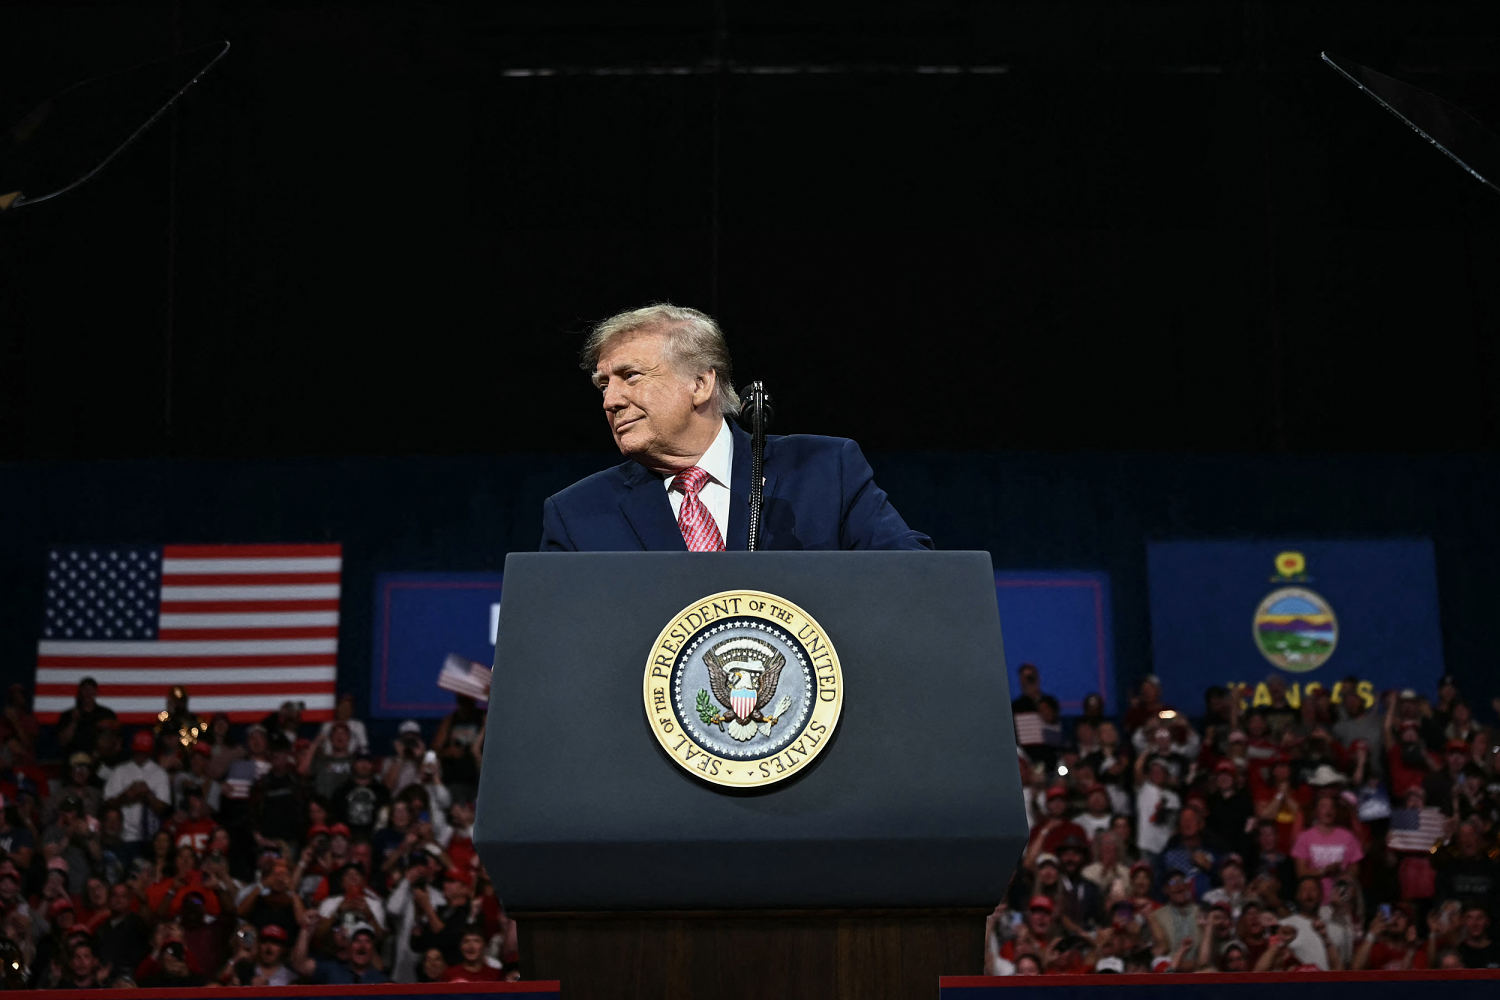
Watch enough midterm cycles from the press pen and a pattern emerges. When voters feel squeezed on prices and candidates face stiff headwinds, promises get louder and numbers get rounder. During the September 2026 Republican National Midterm Convention in Dallas, Trump told the crowd that holding both the House and Senate would unlock a $5,000 check for every adult citizen, subject to spending the money inside the United States. Around the same stretch of the campaign, administration figures and allies floated other financial and policy sweeteners—ranging from healthcare-related rebates and earlier unfulfilled tariff check pledges to rolling back federal rules and fee mandates—while voters weighed whether any of it would ever materialize.
By early November, the voters delivered their answer on the ballot, and Republicans suffered steep losses across competitive races. Even before the votes were tallied, though, the real story wasn't whether a rally crowd cheered the idea of a windfall. The real story was how conditional payouts work as a political instrument, why the budget arithmetic buckled under scrutiny, and how federal waivers and administrative carve-outs operate when legislative gridlock or court rulings block sweeping spending.
Why Conditional Cash Became a Midterm Lifeline
Midterm elections are notoriously unforgiving for the sitting president's party. Voters treat them as a referendum on cost of living, interest rates, and executive overreach. When economic approval slides, traditional party messaging about long-term structural reform rarely moves persuadable voters in three weeks.
Cash is simple. A five-thousand-dollar figure doesn't require a white paper to understand. It lands immediately in a voter's mental ledger alongside grocery bills, utility statements, and borrowing costs.
Framing federal money as a "dividend" borrows the language of corporate share buybacks and payouts—turning taxpayers into shareholders collecting a return on national prosperity rather than borrowers adding to a tab.
Still, timing and conditionality matter just as much as the dollar amount. Pledging money after a midterm victory creates a built-in incentive structure: voters are asked to supply the congressional majority first, and trust that the checks will follow later. Yet skepticism ran high in autumn polling, with large majorities questioning both the wisdom of sending out more cash and the likelihood that the promise would be kept.
That skepticism didn't come out of nowhere. In November 2025, Trump had floated $2,000 tariff-backed payments to Americans, yet those checks never went out, and the Supreme Court struck down his emergency tariffs—leaving the government facing refund obligations to importing businesses rather than distributing windfalls to households. Voters who have heard promises of checks before tend to discount new ones unless they see concrete funding and legislative mechanics.
The Trillion-Dollar Math Behind the Payouts
Campaign promises travel light; federal budgets do not. Multiplying $5,000 across roughly 240 million U.S. adults points to a price tag right around $1.2 trillion. Even if eligibility were narrowed or phased out—a distinction Vice President JD Vance suggested when hinting at means-testing—the scale remains staggering against a national debt that crossed $40 trillion in August 2026.
Fiscal hawks across the political spectrum pointed to an uncomfortable reality on the bond market. With Treasury yields elevated and federal interest payments consuming vast sums relative to major programs, pumping another trillion dollars of deficit-financed cash into the economy risks reigniting inflation or pushing borrowing costs even higher. Rep. Chip Roy, a Texas Republican, bluntly questioned how the cost would be covered, echoing budget analysts who noted that projected tariff revenues fell far short of funding universal checks of that size.
Commerce Secretary Howard Lutnick argued in September 2026 that the payouts wouldn't rely on standard tax revenue and suggested hundreds of billions could come from a new visa program. Even if a new program generated substantial receipts, matching a one-time or recurring multi-hundred-billion-dollar outlay to hypothetical future inflows is a classic Washington stretch. When a proposal depends on optimistic revenue projections and future congressional votes all breaking one way, "guaranteed" quickly turns into "negotiable."
| Funding Mechanism | Stated Pitch | Practical & Legal Reality |
|---|---|---|
| Tariff Revenue | Framed in prior pledges and commentary as a windfall source for checks. | Supreme Court rulings against emergency tariffs and independent estimates show insufficient or reversed inflows. |
| New Visa Program | Suggested by administration officials as a non-tax funding pillar for part of the cost. | Requires operational execution and faces steep scale hurdles against a roughly $1.2 trillion headline figure. |
| Deficit Borrowing | Easiest short-term way to issue checks without immediate tax hikes. | Adds to a national debt above $40 trillion amid high interest costs and inflation concerns. |
| Congressional Appropriation | Required under U.S. law to authorize broad new federal spending. | Demands votes across factions with competing fiscal priorities—and is far harder without unified GOP control. |
Consider a hypothetical example to see how a household experiences the gap between a headline check and the broader economy. Suppose a family of two adults receives $10,000 combined in hypothetical stimulus checks, but higher government borrowing nudges mortgage, auto loan, or credit card rates up and keeps everyday prices sticky. Over twelve to twenty-four months, higher debt service and persistent inflation can quietly eat up far more than a one-time lump sum—especially for households carrying variable-rate balances or renting in tight markets.
Where Waivers and Deregulation Fit In
Cash isn't the only currency in modern campaigning. Waivers, exemptions, and regulatory rollbacks play a quieter, more technical role—and often carry less obvious sticker shock on day one.
When presidents talk about waivers in an economic or governing context, they usually mean suspending a federal rule, easing a compliance requirement, or exempting certain actors from a mandate. In the broader federal toolkit, agencies can sometimes grant waivers under existing statutory authority, withdraw pending rules, or scale back enforcement priorities without passing a brand-new appropriation bill.
That approach appeals to constituencies tired of paperwork, fines, or federal mandates. We have already seen the administration's deregulatory push play out in areas like transportation, where the Department of Transportation formally scrapped a late-Biden-era proposal that would have required airlines to pay cash compensation and cover lodging and meals for major airline-caused delays—a move welcomed by major carriers seeking lighter federal mandates.
Yet waivers have sharp limits, particularly around elections and spending. A president cannot unilaterally waive the Constitution or override clear statutory caps on federal funds. Nor can executive action simply rewrite state election administration rules; courts have repeatedly pushed back against unilateral executive attempts to alter voting procedures, underscoring that states run elections and Congress controls the purse.
There is also a distributional catch with regulatory waivers. Relief from a compliance rule often helps specific industries, states, or operators immediately, while leaving ordinary consumers exposed to the underlying friction—such as paying out of pocket or relying on voluntary customer-service policies when travel goes sideways. A waiver can lower a business's cost of doing business without putting cash into a worker's checking account.
The Post-Midterm Reality Check for Both Parties
Promises made in September look very different in late November. With the 2026 midterm results now in and Democrats making major gains in Congress, the path for a partisan "Trump dividend" bill is dramatically narrower than it was on a convention stage.
Even when Republicans held majorities in both chambers heading into the election, passing a massive universal payout wasn't automatic. Some GOP lawmakers voiced skepticism over the price tag, while others signaled readiness to draft legislation. Now, divided or shifting leverage in Congress guarantees that any sweeping check proposal would face steep resistance, horse-trading, or outright gridlock.
For voters and business leaders watching Washington, the lesson isn't complicated. Always separate three things whenever a politician dangles checks or waivers before an election:
- Authority: Does the executive branch actually have legal power to do this alone, or does it require an act of Congress or state cooperation?
- Financing: Is there real, durable money backing the number, or is it relying on unverified projections and more debt?
- Timing: Will relief arrive immediately as a clear rule change, or is it conditioned on a future election outcome that may never happen?
Campaigns are designed to sell momentum, not balance sheets. When the applause fades and the legislative math takes over, the promises that survive are the ones that didn't need a miracle to pencil out in the first place.