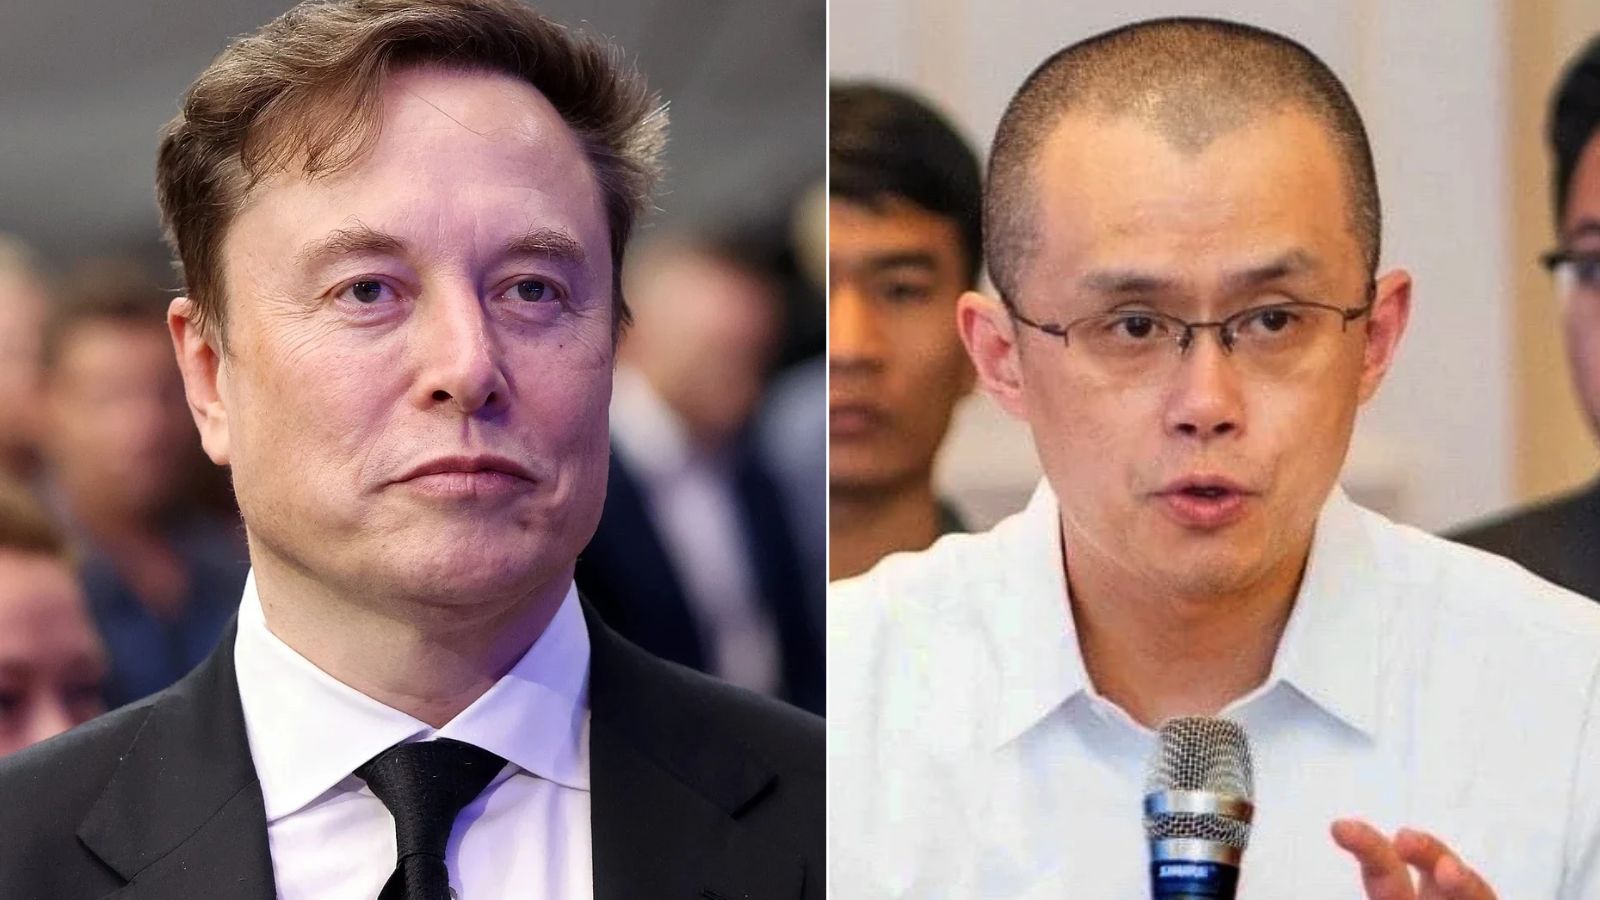
When Changpeng Zhao, the founder of cryptocurrency exchange Binance, reminded Elon Musk of his $500 million equity commitment to the acquisition of Twitter, the exchange was far more than a passing social media spat. It was a public receipt. In May 2022, when Musk was scrambling to assemble the $44 billion required to take Twitter private, Binance quietly wired half a billion dollars into the deal, making the world’s largest crypto exchange one of the most significant outside backers of the platform now known as X. When Musk subsequently mocked aspects of the crypto industry or engaged in public trolling that rattled digital asset markets, Zhao’s pointed reminder served as a stark warning about institutional leverage, overlapping financial interests, and the fragile alliances holding Silicon Valley’s boldest buyout together.
To understand why a single reply on X carried so much weight, you have to look at the mechanics of a leveraged buyout and the desperate financial engineering that birthed X Corp. Acquisitions of that scale are rarely funded by a single billionaire’s liquid cash. They are built on syndicates, debt tranches, and quiet favors called in during the eleventh hour.
The Anatomy of a $44 Billion Syndicate
In the spring of 2022, Elon Musk faced a liquidity problem. Although his net worth on paper exceeded $200 billion, almost all of it was tied up in Tesla and SpaceX stock. Selling tens of billions of dollars in Tesla shares would have triggered a catastrophic market sell-off and a massive tax bill. To close the Twitter acquisition without obliterating his primary asset, Musk needed outside equity investors to share the burden alongside $13 billion in bank loans led by Morgan Stanley.
Enter the co-investors. Alongside traditional Silicon Valley venture firms like Sequoia Capital and Andreessen Horowitz, and sovereign wealth funds like the Qatar Investment Authority, sat Binance.
At the time, Binance was riding the tail end of a historic cryptocurrency bull run. Its daily trading volumes dwarfed those of the New York Stock Exchange, and Zhao was actively looking for ways to legitimize crypto within mainstream Web2 infrastructure. Investing $500 million into Twitter was not an act of charity. It was a strategic beachhead. By putting half a billion dollars on the table, Zhao bought himself a seat at the cap table of the world’s de facto public square.
For Musk, the cash was indispensable. Every dollar committed by an outside co-investor meant one less dollar of Tesla stock he had to dump on the open market. Yet taking money from a crypto giant came with implicit expectations—expectations that frequently collided with Musk’s erratic online persona.
Why Crypto Billions Bought Silence and Influence
When a venture firm or a strategic corporate partner puts $500 million into a private company, they do not get day-to-day operational control. They get preferred equity, periodic financial disclosures, and an unwritten understanding that the CEO will not actively undermine their core business model.
In the immediate aftermath of the buyout, Binance’s thesis appeared sound. The exchange announced the creation of an internal team dedicated to helping Twitter integrate blockchain technology, exploring everything from crypto-based tipping to decentralized identity verification and bot eradication via on-chain authentication. The synergy seemed obvious on paper, even if the technical execution remained murky.
The reality proved far messier. Musk’s relationship with cryptocurrency has always been volatile, oscillating between enthusiastic promotion of Dogecoin and sudden, market-moving skepticism toward Bitcoin and broader Web3 infrastructure. Whenever Musk posted a meme mocking crypto traders or questioning the utility of blockchain technology, the ripple effects hit Binance’s bottom line immediately. Retail trading volume—the lifeblood of Binance’s fee-based revenue model—is uniquely sensitive to social sentiment.
When Zhao publicly pushed back against Musk’s trolling, calling it a "bad time" to poke the bear, he was speaking the language of a major shareholder reminding an executive who helped pay for the building. In traditional corporate finance, those conversations happen in boardrooms or over encrypted phone calls. On X, they happen in the replies, stripped of corporate euphemisms and visible to millions of retail traders.
The Regulatory Crossfire
The timing of any friction between Musk and Zhao was never trivial because both men spent the years following the buyout navigating existential regulatory threats.
Binance found itself locked in a brutal multi-front war with United States regulators, including the Securities and Exchange Commission, the Commodity Futures Trading Commission, and the Department of Justice. By late 2023, that pressure culminated in a historic $4.3 billion settlement with the U.S. government, forcing Zhao to step down as CEO and plead guilty to anti-money laundering violations.
During that exact window, Musk was battling a collapsing advertising market at X. Major brands paused spending over content moderation concerns, sending the platform’s valuation plummeting. According to disclosures from fellow co-investor Fidelity, the value of equity stakes in X dropped by more than 70 percent within two years of the acquisition.
Consider what that meant for Binance’s $500 million stake. On paper, that half-billion-dollar investment had withered to roughly $140 million, all while Binance needed every dollar of liquid capital to pay federal fines and survive global regulatory scrutiny. Watching the CEO of a heavily discounted investment use his platform to alienate the exact demographic that funded Binance’s empire was a bitter pill to swallow.
The Myth of the All-Powerful Tech Founder
Public narratives around Silicon Valley often treat founders like Musk as absolute monarchs who answer to no one. Taking Twitter private reinforced that illusion. Without quarterly earnings calls, public activist investors, or SEC proxy battles, Musk appeared completely untethered.
That perception ignores the reality of private equity governance and debt covenants. Taking a company private does not eliminate accountability; it simply moves it behind closed doors.
Musk still answers to two powerful constituencies:
- The Debt Holders: The consortium of banks holding $13 billion in Twitter buyout debt collects roughly $1.2 billion in annual interest payments. If X fails to generate enough cash flow to service that debt, the banks hold senior claims over the company’s assets.
- The Equity Syndicate: Co-investors like Binance, Sequoia, and Kingdom Holding Company collectively poured more than $7 billion into the deal. While they cannot easily fire Musk, their reputational and financial backing is essential if X ever needs to raise a rescue round of capital, restructure its debt, or eventually return to the public markets via an IPO.
If Musk alienates his major co-investors, he poisons the well for future capital raises. In high finance, reputation is currency. Founders who burn their syndicate partners find that the phone stops ringing the next time they need half a billion dollars wired on short notice.
The Structural Vulnerability of Tokenized Loyalty
The friction between Musk and Zhao also exposes a deeper structural flaw in how the tech and crypto industries intersect. For years, crypto founders believed that buying into legacy Web2 platforms would accelerate mass adoption. They assumed that owning equity in a social media giant would naturally translate into native crypto integration.
It rarely works that way. Legacy social platforms are built on centralized databases, ad-tech auctions, and strict compliance with Apple and Google app store rules. Integrating native crypto rails—beyond basic fiat-to-crypto onramps or simple tipping buttons—introduces massive regulatory liability. If X became a full-fledged crypto exchange or payment processor without securing exhaustive state-by-state money transmitter licenses, federal regulators would shut down its financial arm overnight.
Musk’s vision for X as an "everything app" modeled on WeChat relies heavily on traditional banking rails, Visa and Mastercard partnerships, and regulatory approval from state banking departments. In that environment, proximity to a heavily scrutinized offshore crypto exchange becomes a compliance headache rather than a competitive advantage.
Zhao’s $500 million bought him equity, not product roadmap control. As X pursued traditional payment licenses across the United States, keeping crypto at arm’s length—and occasionally mocking it for engagement—aligned with Musk’s broader pivot toward mainstream financial compliance.
What Happens When Billionaires Clash in Public
When a major backer publicly checks a CEO on the CEO’s own platform, it signals a breakdown in backchannel diplomacy. Normally, investor relations teams smooth over these tensions long before they reach a public timeline. On X, where the CEO is also the platform’s most prolific user, traditional corporate guardrails do not exist.
This dynamic creates an asymmetric risk for co-investors. Institutional funds like Fidelity or sovereign wealth funds absorb paper losses quietly, writing down the asset in quarterly reports without issuing public statements. Crypto founders operate differently. Their businesses rely on public perception, community momentum, and constant visibility. Remaining silent while a high-profile partner undermines your industry looks like weakness to your user base.
Yet firing back carries its own danger. Publicly reminding a notoriously vindictive CEO of his financial debts risks turning a minor annoyance into an all-out feud. Once two billionaires lock horns in public, neither can easily back down without losing face in front of millions of followers.
The Real Cost of the $500 Million Bet
Looking at the trajectory of both X and Binance since 2022, that $500 million check stands as a monument to peak-market hubris. At the height of the zero-interest-rate era, capital flowed freely between tech titans based on shared grandiosity and handshake agreements. Due diligence took a back seat to ideological alignment—specifically, a shared desire to disrupt legacy media and financial gatekeepers.
When interest rates rose, ad revenue dried up, and regulators closed in, the honeymoon ended. The grand vision of a decentralized, blockchain-powered social network quietly evaporated, replaced by the gritty reality of debt restructuring, compliance audits, and plummeting equity valuations.
For Zhao, the investment became a stranded asset—illiquid, heavily marked down, and tied to a CEO whose priorities had shifted entirely toward artificial intelligence, SpaceX launches, and traditional fintech licensing. For Musk, the $500 million remained a permanent reminder that even the richest man in the world cannot buy a global communications network entirely on his own dime.
Every major investor on X’s cap table holds a piece of that leverage. They may not sit in the CEO’s chair, and they may not dictate the daily algorithm, but their capital built the foundation. When the market turns and the debt comes due, the people who wrote the checks always find a way to remind the person spending the money who actually owns the house.