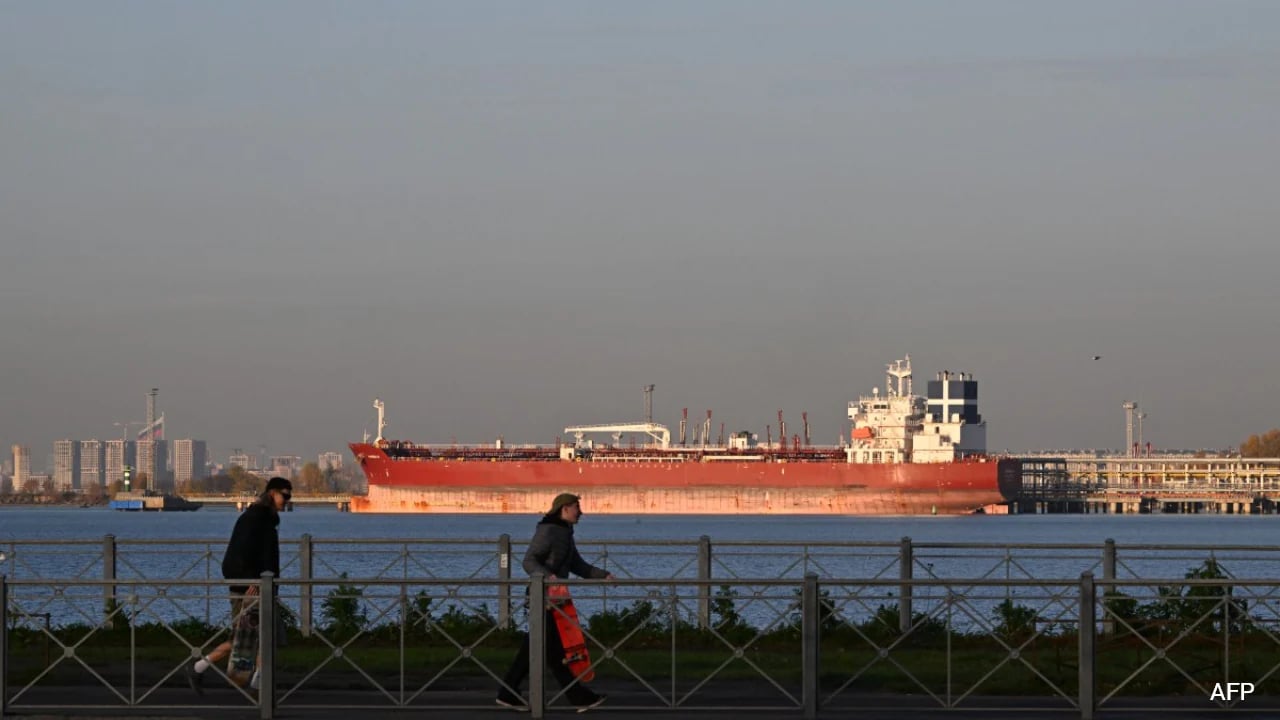
Everyone is losing their minds over a single Medium Range tanker hauling 300,000 barrels of ultra-low sulfur diesel across the Atlantic.
The mainstream press wants you to see a geopolitical earthquake. They frame this vessel—moving from a Baltic terminal toward the US East Coast under a newly brokered Washington-Moscow framework—as a sudden, shocking reversal of Western foreign policy. Pundits are screaming about diplomatic capitulation. Energy analysts on cable news are breathlessly tracking AIS transponder signals like it is the Cuban Missile Crisis on water.
They are looking at the wrong ship. Worse, they are pretending the cargo inside it hasn't been fueling American trucks, trains, and tugboats for the last three years.
The arrival of a direct-flagged or directly contracted Russian diesel cargo at a New York Harbor terminal isn't a radical shift in energy reality. It is simply the removal of an expensive, hypocritical middleman. For years, the global energy market operated under a convenient fiction: that you could ban a major producer's molecules from entering Western ports without actually removing those molecules from the global supply pool. You cannot. Liquids are fungible. Economics always beats ideology at the port gate.
If you want to understand what this tanker actually represents, stop listening to foreign policy theorists and start looking at crack spreads, Jones Act distortions, and the brutal math of Atlantic Basin refining.
The Laundromat Was Always Open
Let’s dismantle the primary myth first. The lazy consensus claims that until this recent diplomatic thaw, Russian refined products were successfully locked out of the American market.
That is factually laughable.
When the G7 and the European Union implemented the refined product price caps and import bans in early 2023, they didn't destroy Russian diesel exports. They merely forced those barrels to take a longer, dirtier, and vastly more profitable detour. Instead of sailing straight from Primorsk or Ust-Luga to Rotterdam or Newark, Russian diesel went to Jamnagar in India, Jubail in Saudi Arabia, or Fujairah in the UAE.
There, inside massive storage tank farms, Russian gasoil was blended with local distillates—sometimes at a 51-to-49 ratio, sometimes simply re-documented through ship-to-ship transfers in international waters off the coast of Greece or Malaysia. Once a certificate of origin was stamped in a third-party port, that exact same Russian molecule loaded onto a clean product tanker and sailed straight into the Amsterdam-Rotterdam-Antwerp hub or the US East Coast.
I have sat on physical trading desks in Houston and Geneva watching this exact shell game play out in real time. I watched charterers pay an extra $40 to $60 per metric ton in freight and blending fees just to wash the paperwork on cargoes everyone knew originated in a Rosneft or Lukoil refinery. American consumers paid for that moral theater at the pump. European industrial manufacturers paid for it with their competitiveness. Meanwhile, a shadow fleet of aging, under-insured tankers made hundreds of millions of dollars hauling oil twice as far as necessary, burning massive amounts of bunker fuel to satisfy Western politicians' need for a press release.
This new shipment isn't opening a closed door. It is just letting the cargo walk through the front entrance instead of climbing through the bathroom window.
Why the US East Coast Actually Needs These Barrels
To understand why Washington quietly welcomed—or at least tolerated—this trade resuming directly, you have to look at PADD 1.
In energy industry shorthand, PADD 1 is Petroleum Administration for Defense District 1, encompassing the entire US East Coast from Maine to Florida. It is the most densely populated, economically vital region in the United States, and it has a glaring structural vulnerability: it has almost no refining capacity left.
Over the past fifteen years, brutal regulatory compliance costs, aging infrastructure, and massive capital expenditure requirements wiped out East Coast refineries. The closure of the Philadelphia Energy Solutions complex in 2019—the largest refinery on the Eastern Seaboard—left a massive structural deficit in distillate supply.
You might ask: Why doesn't PADD 1 just get its diesel from Texas and Louisiana?
The US Gulf Coast (PADD 3) is a refining juggernaut, churning out millions of barrels of surplus diesel every single day. The problem isn't supply; it is a 1920s protectionist relic called the Merchant Marine Act, better known as the Jones Act.
Under the Jones Act, any goods moved by water between two US ports must be carried on ships that are:
- Built in the United States.
- Flagged under the United States.
- Owned by US citizens.
- Crewed predominantly by US citizens.
There are virtually no Jones Act-compliant clean product tankers available to move the sheer volume of diesel New York and New England require, and the ones that exist cost three to four times as much per day to charter as an international vessel. Furthermore, the Colonial Pipeline—the primary artery carrying refined products from Houston to Linden, New Jersey—runs chronically at full capacity.
Consequently, it is vastly cheaper and logistically simpler for a fuel distributor in Boston or Newark to buy a cargo of diesel from across the Atlantic Ocean than it is to buy it from Houston, Texas. Historically, that Atlantic supply came from European refineries running on Russian crude, or directly from Baltic export terminals. When those routes were artificially severed, PADD 1 distillate inventories plunged to multi-decade lows, sending heating oil and diesel futures into violent backwardation and threatening physical rationing every winter.
Dismantling the "Energy Independence" Fairy Tale
Whenever a story like this breaks, a predictable chorus of commentators demands to know why the "world's largest oil producer" is importing fuel from a geopolitical adversary.
This question exposes a fundamental illiteracy about how global oil markets work. "Energy independence" is a political slogan, not an operational reality.
Refineries are not magic boxes that turn any black liquid into gasoline and diesel. A refinery is a multi-billion-dollar chemistry set engineered to process a very specific grade of crude oil—measured by API gravity (light vs. heavy) and sulfur content (sweet vs. sour).
The shale revolution flooded the United States with light, sweet crude from the Permian Basin. However, the complex refineries built along the US Gulf Coast during the 1980s and 1990s were specifically engineered to process heavy, sour crude from Venezuela, Mexico, Canada, and the Middle East. You cannot simply dump light Permian crude into a coking unit designed for heavy bitumen without destroying yields and damaging equipment.
Therefore, the United States exports millions of barrels of light crude every day while simultaneously importing millions of barrels of heavy crude and specific refined blends to balance regional deficits.
Russian refineries produce a distinct grade of ultra-low sulfur gasoil with specific cold-flow properties—vital for winter operations in the American Northeast—that fits East Coast specifications like a glove. Pretending that American shale output makes Atlantic Basin distillate imports obsolete is like claiming a country that grows plenty of wheat shouldn't import yeast.
What Traders Are Actually Watching (And Why Pundits Miss It)
If you look past the political theater, the real story of this tanker isn't about diplomacy. It is about the violent compression of refining margins and freight rates.
Let’s look at the mechanics of what happens when direct Baltic-to-US East Coast trade lanes reopen, even partially:
- The Shadow Fleet Deflates: Over the last three years, hundreds of older tankers were bought up by opaque shell companies in Dubai, Hong Kong, and the Marshall Islands to haul sanctioned Russian barrels. Freight rates for clean MR (Medium Range) and LR2 (Long Range) tankers surged because ton-miles—the distance each barrel had to travel—skyrocketed. Direct Atlantic crossings slash voyage times from 45 days (via the Suez Canal or Cape of Good Hope to Asia and back) down to 12 days. That destroys artificial freight premiums overnight.
- Indian and Middle Eastern Refiners Lose Their Arbitrage: Reliance Industries in India and state-backed refiners in the Gulf made generational profits buying discounted Russian Urals crude, refining it into diesel, and selling it to the West at full market price. If Russian refined products can clear Western ports directly, that middleman margin evaporates.
- The NYMEX ULSD Curve Flattens: The New York Harbor Ultra-Low Sulfur Diesel (ULSD) futures contract is the global benchmark for distillates. Because PADD 1 has been starved of reliable physical resupply, that contract has suffered from extreme volatility and punitive spikes whenever winter weather hits. Reconnecting a major Atlantic supply valve injects immediate physical liquidity into the delivery point, crushing speculative short squeezes.
The Ugly Downside Nobody Wants to Admit
Before anyone celebrates this as a triumph of free-market pragmatism, we need to be brutally honest about the trap it sets.
There is a massive structural risk to welcoming Russian distillates back into Western supply chains without fixing domestic bottlenecks. Every time Washington or Brussels uses foreign supply deals to relieve consumer price pressure at the pump, they remove the political urgency required to fix broken domestic infrastructure.
Right now, the US East Coast remains entirely hostage to foreign waterborne imports because Congress refuses to touch the Jones Act and environmental permitting makes building new pipeline capacity or upgrading coastal refineries virtually impossible. Relying on a transactional deal between two leaders to keep New England homes warm and East Coast freight trucks moving is not an energy strategy. It is a vulnerability masquerading as a bargain.
Furthermore, physical trading houses that jump back into direct Russian liftings are walking across a minefield. Sanctions regimes built on executive orders and temporary waivers can be snapped back into place with a single social media post or diplomatic flare-up. Any bank financing a letter of credit for these cargoes, or any P&I club providing maritime insurance, knows they are one political mood swing away from holding a toxic, untradeable asset mid-ocean.
The compliance cost hasn't vanished; it has just shifted from maritime logistics back onto legal and credit departments.
How to Read the Next Twelve Months of Energy Headlines
If you are allocating capital, managing fuel procurement, or simply trying to understand where inflation is heading, stop reading geopolitical op-eds. Watch the physical spread indicators instead.
- Watch the Gasoil-to-ULSD Arbitrage: Keep your eyes on the price spread between ICE Low Sulphur Gasoil (the European benchmark) and NYMEX ULSD (the New York Harbor benchmark). When physical Russian barrels flow freely into the Atlantic Basin, this spread tightens dramatically. If it blows out again, it means the diplomatic corridor is choking and compliance departments are backing away from the trade.
- Track Clean Tanker Clean-Up Costs: Watch the daily time-charter equivalents for MR tankers operating in the Atlantic. A sustained drop in Atlantic clean freight rates tells you that ton-mile inefficiencies are unwinding faster than the market priced in.
- Ignore Official Import Statistics: Even with direct shipments resuming, official customs data will remain notoriously murky. Barrels blended in offshore ship-to-ship zones or routed through Caribbean storage terminals like St. Eustatius and the Bahamas will continue to blur the exact origin of East Coast supply. Look at total PADD 1 distillate inventory builds reported weekly by the Energy Information Administration (EIA)—the tanks don't lie, even when the bills of lading do.
The tanker crossing the Atlantic right now isn't carrying a new world order. It is carrying 300,000 barrels of cold, hard reality: you cannot sanction physics, you cannot legislate away geography, and in the end, the market always routes around the politicians.