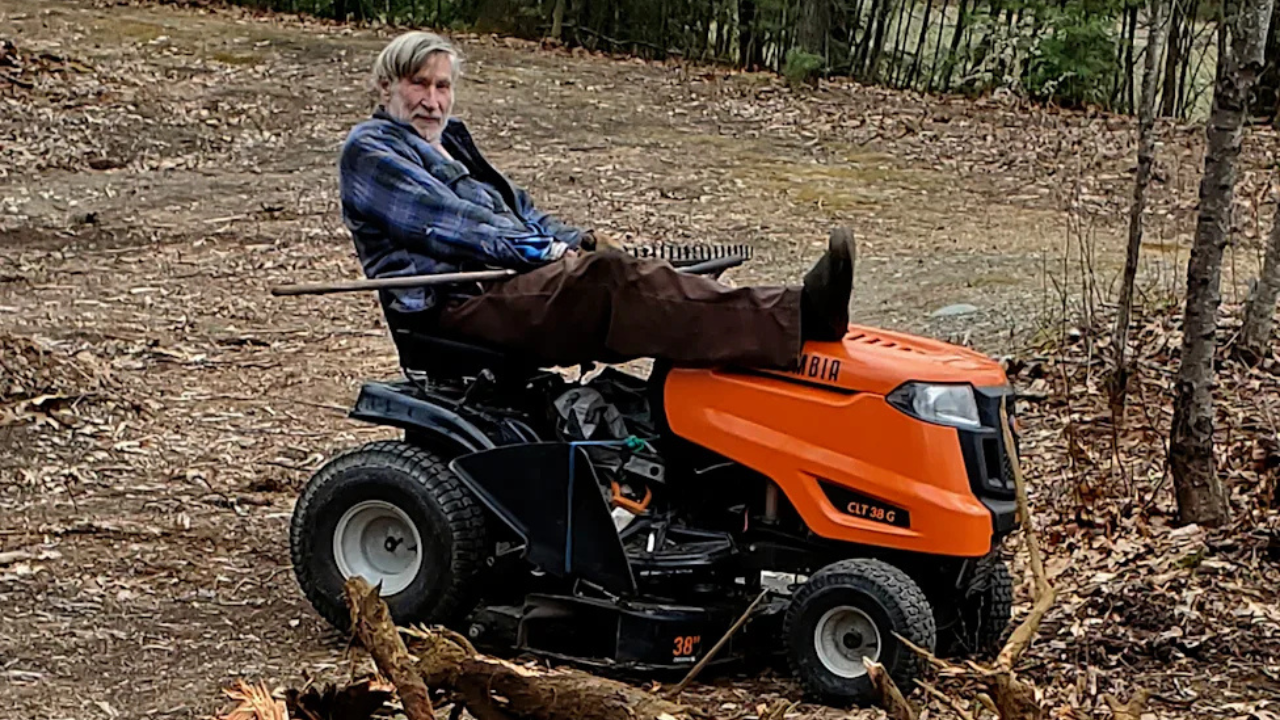
Geoffrey Hudson never bought a new car, eschewed conspicuous consumption, and worked as a groundskeeper in New Hampshire while quietly accumulating millions of dollars through disciplined equities investment. Upon his death, his estate of approximately 3.8 million dollars was bequeathed to the town of Jaffrey, designated for municipal and educational improvement. While mainstream media narratives frame this phenomenon as a heartwarming anomaly or a quaint human interest story, a rigorous financial and behavioral audit reveals a complex interaction between compounding returns, structural cost minimization, and asymmetric utility curves.
Examining cases like Hudson requires stripping away emotional commentary to analyze the underlying mechanics: capital accumulation through deliberate lifestyle inflation suppression, the mechanics of low-velocity index investing over multi-decade horizons, and the inefficiencies of municipal wealth absorption.
The Mechanics of Capital Accumulation via Expenditure Suppression
To understand how a modest wage earner accumulates multi-million dollar liquidity, one must examine the household balance sheet as a closed-loop system governed by the savings rate equation. Traditional financial planning models assume an income trajectory that dictates lifestyle expansion. Hudson operated on an inverted model where income velocity was decoupled from expenditure growth.
The core drivers of this accumulation model involve three structural variables:
- Fixed Cost Baselines: By keeping housing and transportation costs near absolute zero—often achieved through inherited property, outright ownership without leverage, or rural cost-of-living adjustments—discretionary cash flow approaches net income.
- The Marginal Propensity to Consume: As income or portfolio value increases, the standard economic agent exhibits a rising marginal propensity to consume luxury goods. Extreme accumulators maintain a flat or declining marginal propensity to consume, directing 90 percent or more of marginal capital gains and earnings back into productive assets.
- Opportunity Cost of Status Signaling: Consumer expenditure often functions as a signaling mechanism for social hierarchy. By opting out of status signaling entirely, the individual eliminates the depreciation drag associated with luxury assets, automobiles, and recreational real estate.
When surplus capital generated via zero-consumption strategies is deployed into broad-market equities over a forty-year timeframe, the mathematical outcome is predictable rather than miraculous. Assuming a baseline initial capital injection and consistent quarterly reinvestment of dividends into a total stock market index, compounding returns naturally scale the portfolio into the seven-figure range. The anomaly is not the portfolio size, but the psychological stamina required to maintain a zero-hedonic-adaptation lifestyle across shifting macroeconomic cycles.
The Cost Function of Posthumous Windfalls for Municipalities
When a municipality receives a multi-million dollar bequest from an unexpected source, public discourse treats the event as unalloyed positive stimulus. From a public finance perspective, however, large, unbudgeted capital injections into small local governments create friction, misallocation risks, and institutional inertia.
The integration of sudden capital into a town budget exposes structural vulnerabilities:
- Absorptive Capacity Constraints: Small municipal governments operate with limited project management bandwidth. Receiving a multi-million dollar check without an existing capital improvement framework leads to rushed procurement, inflated contractor bids, and pet projects that fail cost-benefit validation.
- Recurring Cost Trap: Capital outlays frequently generate ongoing operational expenditure obligations. A new municipal facility, park infrastructure, or technology upgrade funded by a one-time bequest requires perpetual maintenance budgets drawn from future local taxation. Without an endowment mechanism structured to yield only the real return, the principal erodes.
- Principal-Agent Alignment: Without strict donor intent codification or independent fiduciary oversight, municipal allocation committees are vulnerable to political capture, where funds are directed toward visible, short-term political wins rather than high-ROI infrastructure investments like water management or educational endowments.
To optimize a municipal bequest of this magnitude, standard fiduciary practice dictates the creation of a permanent charitable trust or endowment fund. By restricting disbursements to a conservative payout rate—such as four percent annually adjusted for inflation—the principal remains intact in perpetuity, transforming a single financial event into a generational revenue stream.
Behavioral Finance and the Utility Maximization Paradox
Standard microeconomic theory posits that individuals maximize utility through consumption over their lifecycle. The life-cycle hypothesis assumes that rational actors save during peak earning years to smooth consumption through retirement, ultimately dying with zero net worth to maximize lifetime utility.
Geoffrey Hudson and similar extreme savers violate this predictive model, operating instead under a utility function where wealth accumulation itself—or the absolute security derived from a massive liquidity buffer—provides higher marginal utility than consumption.
This behavior highlights two distinct psychological drivers:
- Risk Aversion as Asset Protection: For individuals from working-class backgrounds, financial volatility represents an existential threat. Extreme accumulation serves as a psychological hedge against macroeconomic shocks, medical emergencies, and systemic instability. The utility derived from financial safety dwarfs the utility derived from experiential consumption.
- The Legacy Motive: While outwardly solitary, accumulating capital without consumption implies a subconscious or conscious desire for posthumous agency. By directing millions to a specific municipality, the individual purchases immortality within the local civic record, redirecting decades of unspent personal labor into public goods.
Strategic Execution for Capital Preservation and Transfer
Analyzing the mechanics of this wealth transfer yields clear operational insights for estate planning, municipal finance, and personal wealth architecture:
- Automate Asset Retention: Eliminate lifestyle creep at the earliest possible career node. Design personal finance architecture where savings rates scale automatically with income, rendering conscious budgeting decisions obsolete.
- Institutionalize Bequests: When planning large-scale charitable or municipal transfers, bypass direct lump-sum disbursement. Mandate the establishment of a managed endowment fund with strict governance rules to prevent absorptive capacity failure and ensure perpetual yield generation.
- Align Asset Classes with Horizon: Deploy long-horizon, unspent capital exclusively into low-cost, tax-efficient equity indices or sovereign debt instruments depending on liquidity requirements, minimizing management fee drag that erodes multi-decade compounding.
The legacy of a New Hampshire groundskeeper is less a testament to financial wizardry than a masterclass in the mathematics of restraint. By refusing to participate in the consumer economy, individuals can redirect the entirety of their economic output into productive assets, reshaping local institutions through the sheer force of sustained capital retention.