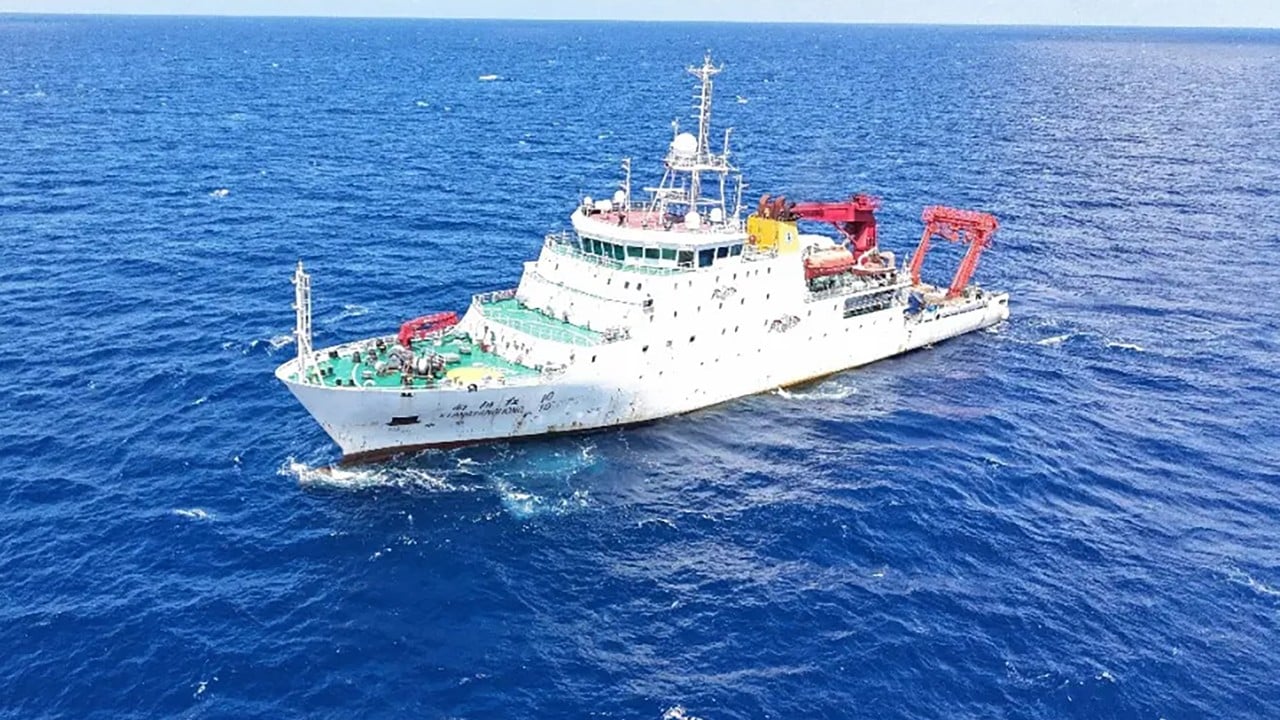
The recent discovery of high-value mineral concentrations beneath the Pacific Ocean highlights a recurring friction point between geological potential and economic viability. When researchers identify dense accumulations of precious and base metals in deep-water environments, public discourse frequently mistakes raw resource presence for commercially extractable wealth. Evaluating these announcements requires stripping away sensationalism and examining the underlying operational constraints, cost functions, and regulatory bottlenecks that dictate whether subsea deposits become active supply chains or remain permanently stranded assets.
The Mechanics of Subsea Resource Formation
Subsea mineral deposits typically form through hydrothermal vent activity or the accumulation of hydrogenetic crusts and polymetallic nodules over millions of years. In hydrothermal systems, superheated, mineral-rich fluids ascend from beneath the Earth's crust, collide with cold seawater, and precipitate solid metal sulfides onto the seabed. These structures frequently concentrate copper, zinc, gold, and silver in grades significantly higher than typical terrestrial ore bodies.
However, high ore grade does not equate to high net present value. Terrestrial mines benefit from economies of scale, established transport infrastructure, and stable atmospheric operating conditions. Deep-sea extraction operates under entirely different physical constraints. The environment is characterized by crushing hydrostatic pressure, absolute darkness, near-freezing temperatures, and extreme logistical isolation thousands of meters below the surface. Consequently, the ore grade must offset capital expenditures that scale exponentially with depth.
The Cost Function of Deep Ocean Extraction
Deploying heavy machinery to the abyssal plain or underwater volcanic arcs introduces a complex capital expenditure profile. The primary cost drivers fall into three distinct operational categories:
- Surface-to-Seabed Logistics: Operations require specialized dynamically positioned vessels capable of maintaining precise station-keeping in open ocean conditions regardless of surface weather. These vessels serve as the command center for heavy crawler units operating on the seafloor and vertical hydraulic lift systems designed to pump slurry thousands of meters upward.
- Mechanical Wear and Maintenance: Seawater combined with high-pressure, abrasive mineral slurry creates a hyper-corrosive and erosive environment. Equipment failure rates are exceptionally high, and maintenance windows require expensive retrieval operations to the surface deck.
- Environmental Mitigation and Monitoring Infrastructure: Unlike historical terrestrial mining where environmental compliance evolved reactively, deep-sea operations face stringent international scrutiny. Operators must deploy real-time acoustic, optical, and chemical monitoring arrays to track plume dispersion and benthic disruption, adding substantial overhead to the operating expense model.
These variables create a steep financial barrier. A project may command impressive estimated gross revenues based on current spot prices for gold and associated base metals, but the internal rate of return frequently collapses when factoring in the multi-decade capital amortization schedules required for unproven deep-water technologies.
Geopolitical and Regulatory Friction
Beyond engineering challenges, the regulatory framework governing international waters creates a complex risk matrix. Activities conducted beyond national jurisdictions fall under the purview of the International Seabed Authority, an organization tasked with balancing commercial exploitation with the mandate to protect the marine environment as the common heritage of mankind.
The absence of a finalized exploitation code creates regulatory uncertainty. Mining conglomerates cannot secure project financing without clear legal definitions regarding tenure security, royalty structures, and environmental liability. Furthermore, coastal states within the Pacific basin hold varying perspectives on the balance between economic diversification through resource extraction and the preservation of pristine marine ecosystems, leading to shifting national legislation and regional moratoria.
The Substitution and Demand Dynamics
Proponents of marine mining argue that terrestrial reserves of critical minerals are depleting, making ocean deposits an inevitable frontier for global supply chains. While long-term ore grades on land are indeed declining for certain commodities, the economic equation is constantly shifting due to technological substitution, recycling efficiencies, and geopolitical supply chain interventions.
Gold possesses unique market dynamics compared to industrial transition metals like copper, nickel, or cobalt. Because gold is primarily a store of value and an industrial component with high recovery rates from recycling, the global supply pipeline is less vulnerable to sudden structural deficits that might otherwise justify the extraordinary capital risk of deep-sea extraction.
Operational Realities and Strategic Forecast
Translating underwater geological discoveries into commercial output requires a fundamental shift from exploration geology to industrial systems engineering. The viability of Pacific gold and polymetallic deposits depends entirely on the compression of operating costs through automation, the maturation of riser lift technology, and the establishment of predictable regulatory frameworks. Until these variables align to lower the risk-adjusted cost of capital, deep-sea mineral finds will remain high-potential scientific indicators rather than active components of the global commodity supply.


