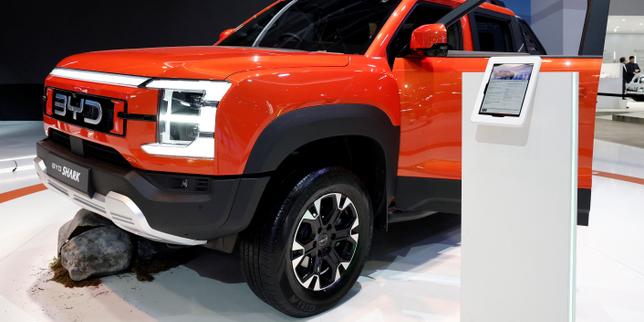
The arrival of Chinese automotive conglomerates at European exhibitions like the Mondial de l'Auto is often misread as a conventional export push. It is better understood as a margin-driven capital deployment phase designed to absorb domestic overcapacity while testing the resilience of legacy distribution frameworks. Understanding this dynamic requires stripping away marketing noise and examining the structural mechanics of how these firms operate, price, and scale across fragmented regulatory territories.
The Structural Drivers of Outbound Expansion
Domestic market saturation in China has created a severe supply-demand imbalance. State-backed production targets, combined with rapid scaling among battery-electric vehicle manufacturers, generated excess factory capacity that the domestic market cannot absorb without triggering destructive price wars. Read more on a connected subject: this related article.
Exporting is not merely a growth strategy; it is a balance sheet stabilization mechanism.
When a manufacturer achieves high factory utilization rates through domestic volume, incremental units shipped overseas at marginal cost can yield positive gross margins, even after accounting for logistics, localization, and emerging tariff barriers. This economic reality explains the speed of deployment. Firms are not waiting for optimal conditions; they are optimizing for asset turnover and fixed-cost amortization. More analysis by Forbes delves into similar perspectives on this issue.
Taxonomy of Market Entrants
Chinese automotive brands penetrating international markets are far from monolithic. They operate under distinct capital structures, governance models, and risk tolerances. Grouping them into a single category obscures their strategic intent.
The State-Backed Industrial Giants
Firms such as BYD, SAIC, and Chery operate with deep state linkages, secure supply chains, and massive balance sheets. Their advantage lies in vertical integration. By manufacturing proprietary batteries, semiconductors, and structural components, they insulate themselves from margin compression in ways legacy European manufacturers cannot easily replicate. Their entry playbook relies on multi-segment presence, rapid network scaling, and aggressive total cost of ownership propositions.
The Independent Digital-First Upstarts
Enterprises like NIO and Xpeng represent a different operational philosophy. Built around software-defined vehicle architectures, user ecosystems, and premium positioning, these firms enter foreign markets with higher initial unit costs and significant brand awareness deficits. Their strategy depends on proving technological superiority in infotainment, advanced driver assistance systems, and charging infrastructure integration to justify premium price points.
The Heritage-Acquisition Playmakers
Some brands leverage historical European marque acquisitions to bypass the trust barrier entirely. By utilizing dormant European brand equity combined with Chinese manufacturing execution and platform engineering, these entities minimize consumer friction during initial market penetration.
The Cost Function and Pricing Mechanics
Traditional automotive pricing is governed by a legacy cost-plus model: research and development, tier-one supplier margins, assembly labor, dealer network markups, and corporate overhead are tallied to establish a retail price. Chinese manufacturers frequently invert this function through target-costing and extreme supply chain consolidation.
By co-locating R&D with component fabrication clusters—particularly in battery chemistry and power electronics—these firms compress development cycles from five years to under thirty months. This speed reduces capital lock-up and accelerates technological iteration. When these vehicles land in Europe, their pricing reflects not a predatory loss-leader strategy in every case, but a structurally lower cost base achieved via localized supply chain density and high-volume component standardization.
Distribution and Regulatory Friction Points
The primary constraint facing Chinese automakers in Europe is not consumer acceptance of electric powertrains, but the friction of distribution and regulatory compliance.
Legacy auto relies on independent dealer networks that control local service, maintenance, and consumer trust. Direct-to-consumer models pioneered by digital upstarts face high capital expenditure requirements for service center buildouts. Consequently, many entrants are adopting hybrid franchise models, partnering with established European dealer groups to solve the service bottleneck.
Concurrently, regulatory scrutiny regarding data security, cybersecurity standards, and countervailing duty investigations creates compliance hurdles. These hurdles do not halt expansion; instead, they alter the speed and localization requirements. Manufacturers are forced to establish regional R&D hubs and localized assembly plants to preempt tariff escalation and meet stringent data residency mandates.
Long-Term Capital Allocation and Strategic Forecast
The presence of Chinese marques at major European auto shows signals a permanent structural shift in global automotive asset allocation. Western incumbents face a compressed timeline to restructure their cost bases, modularize their software architectures, and streamline their supplier ecosystems.
The differentiator moving forward will not be brand heritage or styling alone, but the velocity of engineering iteration and supply chain resilience. Manufacturers unable to match the speed of platform updates and cost discipline demonstrated by top-tier Chinese conglomerates will experience chronic margin erosion, regardless of their domestic market protection measures. Capital will continue to flow toward operational agility, forcing a convergence where global automotive manufacturing operates under a unified standard of digital integration and supply chain efficiency.


