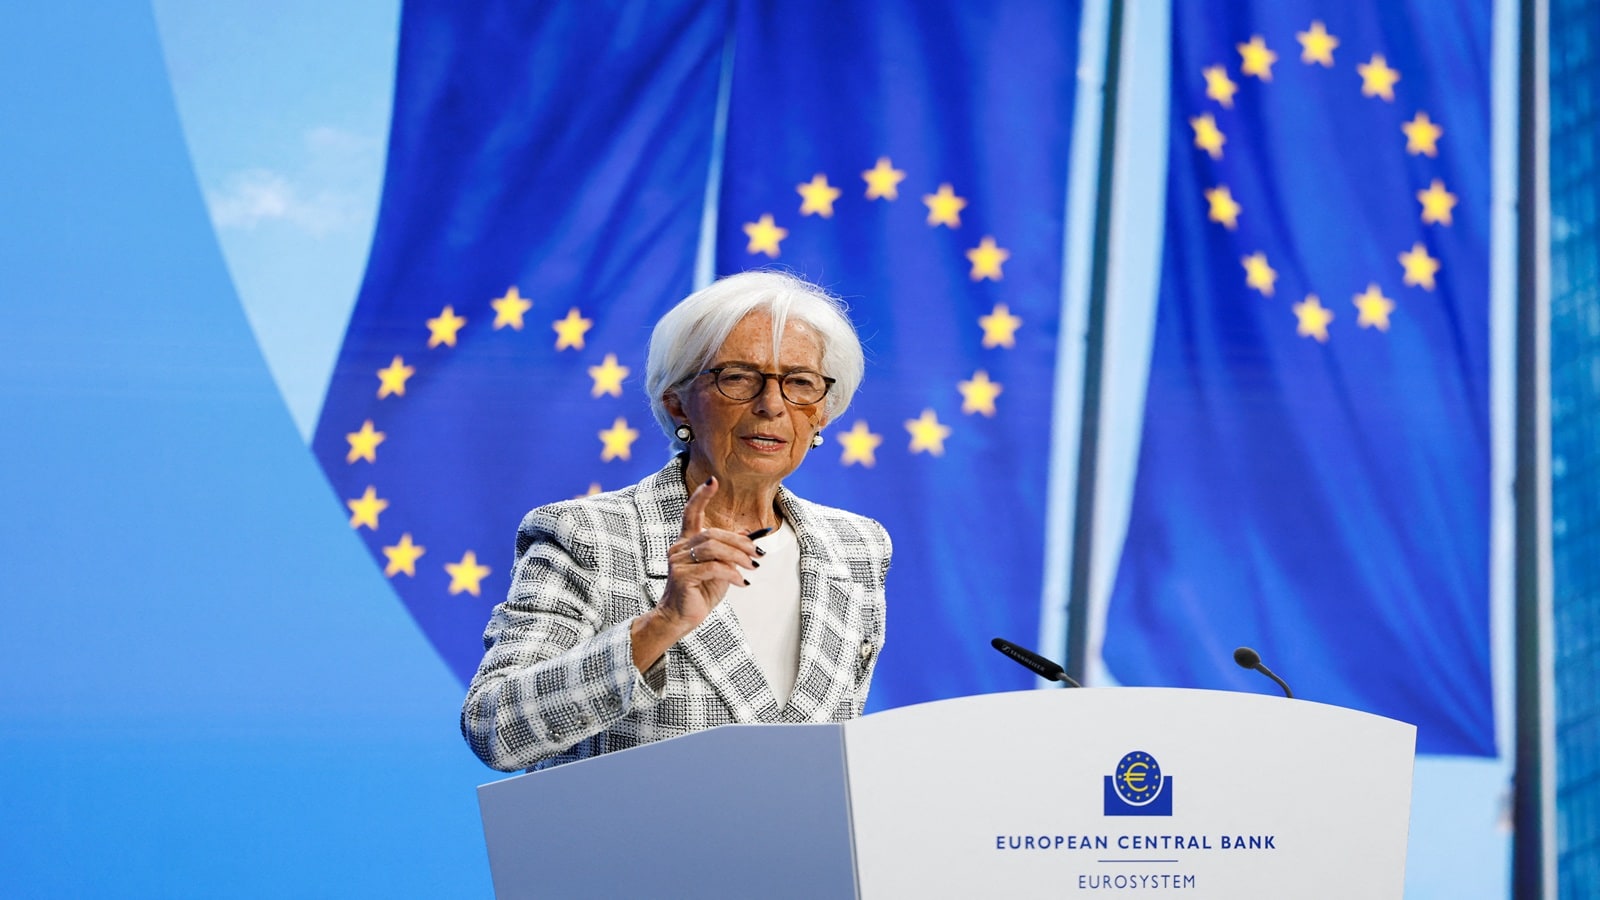
According to standard financial press narratives—exemplified by headlines claiming Christine Lagarde resigned early so she could speak freely on topics beyond monetary policy—her departure from the European Central Bank is being framed as a noble quest for intellectual liberation.
That reading of Frankfurt politics is remarkably naive.
The consensus story treats central banking like a monastic vow of silence that a restless leader simply outgrew. It paints a picture of a former IMF chief and French finance minister suddenly realizing, years into an eight-year non-renewable term, that the strictures of price stability prevent her from opining on climate change, European fiscal integration, or geopolitical fragmentation. Anyone who has spent more than ten minutes watching the Governing Council operate knows that narrative gets the causality completely backward.
Lagarde never struggled to speak about topics beyond monetary policy while sitting in the Eurotower. In fact, her critics—ranging from Bundesbank traditionalists to former ECB chief economist Otmar Issing—spent years arguing she talked about too much outside the narrow mandate of Article 127 of the Treaty on the Functioning of the European Union. She championed greening the ECB's balance sheet, weighed in on European defense spending, and routinely acted as a political diplomat for the Eurozone.
When a central bank president steps down early, it is rarely because they ran out of things they were allowed to say. It is almost always because the institutional friction between what the job demands and what European politics will tolerate has reached a breaking point.
The Myth of the Muzzled Central Banker
To understand why the "free speech" angle falls apart, look at the actual mechanics of ECB communication.
Unlike the Federal Reserve, which operates under a dual mandate of maximum employment and stable prices within a single sovereign fiscal union, the ECB presides over twenty distinct national treasuries. Every word uttered by the ECB President is instantly parsed by bond vigilantes in London, fiscal hawks in Berlin, and populist coalitions in Rome.
If you have ever watched a sovereign debt desk react in real time to an unscripted remark during a Frankfurt press conference, you know how fragile that equilibrium is. In March 2020, a single off-the-cuff sentence from Lagarde—"we are not here to close spreads"—sent Italian 10-year BTP yields surging by over 60 basis points in a single afternoon. That was not a failure of free speech; it was a live demonstration that when you hold the printing press for the world's second-largest reserve currency, your personal opinions cease to exist. Every syllable becomes a pricing input.
The idea that Lagarde suddenly decided to trade the most powerful monetary megaphone on earth for the ability to give unfiltered speeches on the think-tank circuit misunderstands how power works in Brussels and Frankfurt. You do not gain influence by leaving the Governing Council; you surrender leverage.
Why Analysts Misread Early Exits
Financial journalists love personality-driven explanations because structural monetary plumbing is boring to sell. It is much easier to write a profile about a leader yearning for political autonomy than to explain the exhausting reality of managing an asymmetric currency union when fiscal dominance starts creeping back into the system.
Consider the structural traps facing any ECB head in the mid-2020s:
- The Transmission Protection Instrument (TPI) Paradox: The ECB invented tools to cap borrowing costs for indebted member states without triggering outright bailout clauses. Defending those tools requires constant political tightrope walking.
- Quantitative Tightening vs. Sovereign Debt Loads: Shrinking a multi-trillion-euro balance sheet while European governments demand massive capital for energy transition and defense creates an irreconcilable clash between monetary discipline and political survival.
- Governing Council Fragmentation: Balancing the hawks of the northern core against the doves of the southern periphery turns every six-week rate decision into a trench war.
By framing an early exit around a desire to "speak freely," commentators sanitize what is actually an institutional exhaustion. It lets European leaders avoid asking why the presidency of the European Central Bank has become a meat grinder of competing political mandates.
What People Actually Get Wrong About Central Bank Independence
Whenever a high-profile central banker steps aside or pivots toward broader political commentary, the same predictable questions flood financial forums and op-ed pages. Most of them rest on a broken premise.
"Did Lagarde politicize the ECB too much?"
This question assumes there is a clean, apolitical version of central banking waiting to be recovered. There isn't. The moment central banks moved from setting overnight interbank rates to buying trillions in sovereign and corporate bonds, the line between monetary policy and fiscal allocation vanished. Buying green bonds or weighting corporate purchases toward lower-carbon issuers is a political choice. Refusing to do so and implicitly subsidizing legacy fossil fuel conglomerates is also a political choice. Lagarde didn't invent the politicization of the ECB; she inherited a balance sheet that made neutrality mathematically impossible.
"Does an early resignation weaken the Euro?"
Currency markets do not price sentiment; they price interest rate differentials, capital flows, and institutional continuity. A leadership transition at the ECB only rattles the Euro if the successor signals a sharp deviation in the reaction function—specifically, a willingness to tolerate above-target inflation to accommodate national deficits. What weakens the currency over the long haul is not who sits in the chair, but whether the European Union can build a genuine capital markets union to match its monetary union.
"Can a former ECB President ever truly speak freely?"
No. Even out of office, former central bank chiefs carry the implicit weight of institutional signaling. Look at Mario Draghi. Even after leaving Frankfurt and later the Italian premiership, his reports on European competitiveness are treated as quasi-official policy blueprints. You do not escape the gravitational pull of the Eurotower simply by handing back your security badge.
The Real Incentive Behind Stepping Aside Early
If the desire for unscripted commentary isn't the real driver, what actually motivates a calculated early departure from an eight-year term?
Look at the European political calendar and the mechanics of succession horse-trading.
Top jobs in the European Union—President of the European Commission, President of the European Council, High Representative for Foreign Affairs, and President of the ECB—are never filled in isolation. They are distributed as part of a massive, multi-year geopolitical puzzle balancing geography, party affiliation, and gender across member states.
When an ECB President serves out every single day of an eight-year term, their departure is locked into a rigid calendar that may not align with broader European political shifts or national election cycles in France and Germany. By controlling the timing of an exit, an outgoing leader achieves two things simultaneously:
- Succession Leverage: Stepping down on a chosen timeline forces European capitals to negotiate a replacement under current political realities rather than waiting for a potentially more fragmented or populist European Parliament.
- Reputational Preservation: Leaving while inflation has been wrestled back toward target—before the next sovereign debt flare-up or industrial recession forces another round of painful emergency interventions—allows a leader to exit at the top of the cycle rather than taking the blame for structural stagnation that monetary policy cannot fix.
I have watched senior executives and institutional leaders across European finance make this exact calculation for twenty years. The ones who stay until the final bell almost always end up absorbing the blame for macro forces outside their control. The ones who leave early control the narrative—and if they can convince the press they left to pursue "broader intellectual freedom," all the better.
The Downside of the Contrarian View
Let's be fair about where this institutional-cynicism lens can overshoot.
Arguing that Lagarde's exit is purely about political positioning and institutional fatigue risks underestimating the genuine frustration a trained politician feels inside a technocratic straitjacket. Lagarde is not an academic economist in the mold of Ben Bernanke or Mervyn King. She is a lawyer, a former corporate chair at Baker McKenzie, and a career crisis manager who spent decades in the arena of elective and diplomatic politics.
For someone wired for direct political persuasion, having to communicate exclusively through coded central-bank boilerplate—where changing "persistent" to "moderating" in a monetary policy statement triggers algorithmic sell-offs—is genuinely suffocating. There is real friction between a political temperament and a technocratic office.
Even accounting for that personal friction, however, treating the desire to speak freely as the primary cause mistakes a symptom for the disease. The disease is a European governance model that keeps dumping fiscal, industrial, and climate problems onto the lap of an unelected central bank because elected parliaments lack the political courage to pass unified budgets.
How Investors and Observers Should Read the Signal
Stop reading central bank departures like celebrity memoirs. If you manage capital, run a European business, or simply want to understand where the Eurozone is headed, ignore the press-release poetry about new chapters and broader horizons.
Watch three concrete indicators instead:
- The Nationality and Background of the Frontrunner: If Berlin and Paris push for a strict monetary hawk from a core northern country, expect tighter financial conditions and less tolerance for peripheral bond spread widening. If a consensus technocrat emerges, expect continuity of the current reaction function.
- Fiscal Rules Enforcement in Brussels: Pay less attention to who speaks at Jackson Hole or Sintra, and watch how the European Commission enforces the revamped Stability and Growth Pact. Monetary policy is now the passenger; national deficit spending is driving the car.
- The Pace of Balance Sheet Runoff: Track the monthly reduction in the ECB's Asset Purchase Programme (APP) and Pandemic Emergency Purchase Programme (PEPP) portfolios. Actions on the balance sheet reveal the Governing Council's true risk tolerance far more honestly than any speech ever will.
Christine Lagarde did not walk away from Frankfurt because she suddenly realized she had opinions on geopolitics and climate finance. She walked away because she recognized a truth that European politicians still refuse to admit: you cannot fix a broken fiscal architecture with better speeches from a central bank.