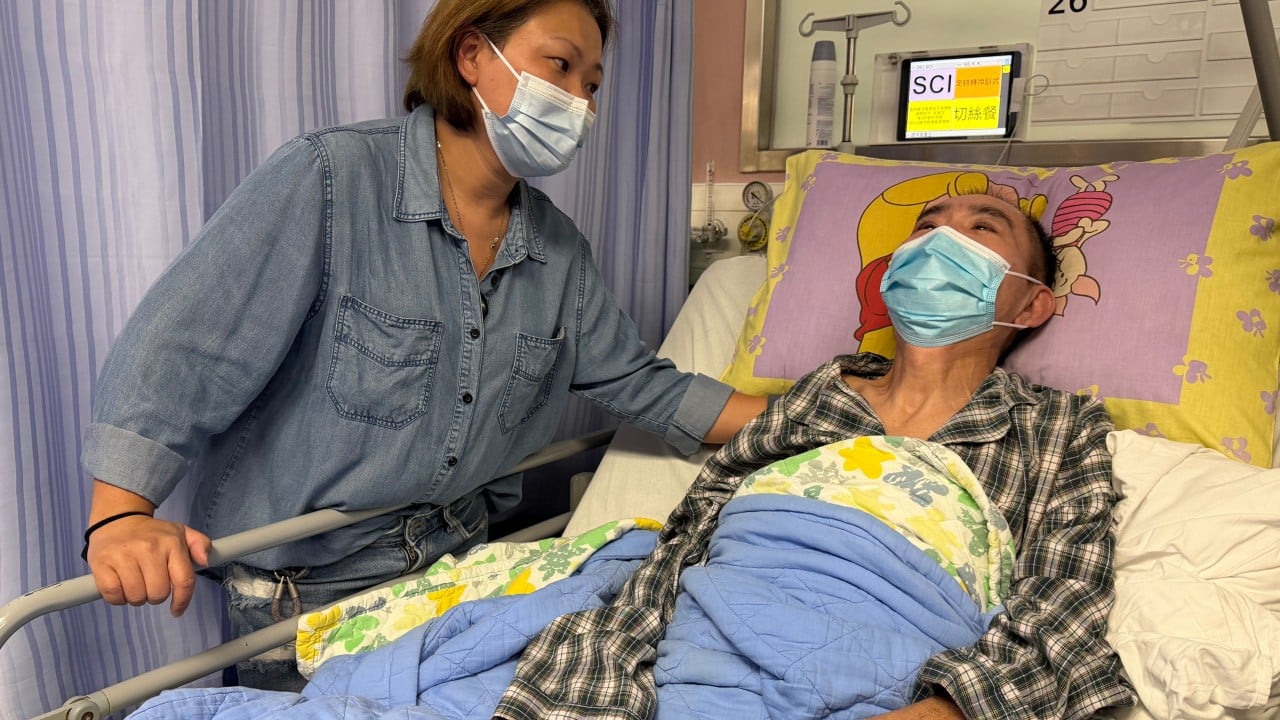
The lazy consensus writes itself. A delivery courier crashes while checking an order alert, ends up paralysed, and waits months for an insurer to pay out. Out comes the familiar headline: caught in insurance limbo. Out come the predictable villains—heartless platforms, slow insurers, and a legal system lagging behind the gig economy.
That framing is comforting because it gives you a simple villain and a tidy fix. Pass a new law. Force a faster payout. Demand more empathy.
It is also dangerously shallow.
When a Hong Kong Keeta rider is left paralysed after a crash and stuck waiting on compensation, calling it mere "insurance limbo" treats a structural fault line like a clerical delay. The real trap is not just that an insurer is dragging its feet. The real trap is that voluntary commercial accident cover is being asked to do the job of statutory workers' compensation, while the platform economy operates inside a classification grey zone where risk, control, and liability are split down the middle.
The Lazy Consensus Everyone Repeats
Standard coverage of stories like this follows a well-worn script. First comes the human tragedy: a rider's life upended on the road, a family chasing paperwork while medical bills and lost earning capacity mount. Second comes the indignation: how can a major app platform leave someone waiting so long? Third comes the call for a quick legislative patch.
I have worked around risk transfer, claims operations, and commercial liability long enough to recognise when people are arguing with the wrong stopwatch. I have seen companies blow millions on shiny compliance initiatives and PR-friendly safety pledges while ignoring how a catastrophic injury claim actually behaves in the real world. When someone suffers paralysis, a minor fender-bender claim does not just stretch out—it mutates. Permanent disability triggers medical re-evaluations, liability scrutiny, third-party motor and fault questions, policy sub-limits, and documentation hurdles that have nothing to do with "evil adjusters twirling their mustaches."
Blaming "insurance limbo" makes claims sound like a vending machine where money should drop out the moment a form is uploaded. Catastrophic injury claims are not vending machines. They are adversarial, high-severity events governed by policy wording, causation proof, and legal standing.
Why "Waiting for Law" Is Only Half the Story
A common reflex is to assume that without a bespoke gig-worker statute already sitting on the books, riders have zero legal hooks and platforms face zero exposure. That is wrong in both directions.
Under Hong Kong's Employees' Compensation Ordinance (Cap. 282), statutory employees' compensation insurance is mandatory for employers over employees working under a contract of service. Yet gig delivery riders have historically been structured or contested as self-employed independent contractors rather than traditional employees. That distinction changes everything. A voluntary personal accident or group policy bought by a platform is not identical to statutory employees' compensation. Voluntary policies have their own definitions, exclusions, caps, and evidentiary requirements—and because they are contractual rather than statutory in the traditional employment sense, dispute resolution and payout timing can feel like a maze to a family in crisis.
At the same time, calling the status quo a total legal vacuum ignores how courts actually test reality over labels. Legal commentary from firms like Stephenson Harwood and Lewis Silkin, along with Hong Kong court rulings involving delivery platforms, shows that labels in a contract do not end the inquiry if the practical reality points elsewhere—though courts have also examined factors like freedom to log on or reject orders, equipment ownership, financial risk, and delegation when assessing contractor versus employee status. Meanwhile, Hong Kong's common law duty of care and government proposals around job-related injury compensation for gig delivery workers highlight just how contested the boundary between "gig flexibility" and "workplace protection" has become.
Imagine a scenario where a rider logs onto an app for two hours a week between full-time jobs, gets pinged while riding, and crashes. Now contrast that with a rider who treats the app as a primary livelihood, follows algorithmic incentives, and depends on constant availability to earn a livable income. Applying a single one-size-fits-all assumption to both—either pretending both are pure independent micro-enterprises or pretending both behave identically to salaried office staff—is where policy and public debate keep tripping over their own shoelaces.
The Uncomfortable Trade-Off Nobody Wants to Price In
Here is the part that makes advocates wince and executives squirm: every extra layer of protection, every broader definition of "on-duty" time, and every higher payout ceiling has to be funded somewhere.
If you expand injury coverage to include waiting periods, order-acceptance alerts, and multi-app grey zones—a major point of friction raised by labour groups and riders when discussing compensation gaps—insurers will price for higher frequency and higher severity. Either platforms absorb that cost through thinner margins, pass it on via higher fees and lower per-order payouts, or tighten rider onboarding, zone caps, and safety rules.
Let me be candid about the downside of taking this contrarian view. If you focus too heavily on policy mechanics, actuarial pricing, and legal classification tests, you risk sounding detached from the human reality of a paralysed rider lying in a hospital bed. No one living through a spinal injury cares about academic debates over control tests or loss ratios; they care about survival, care, and solvency. That is a real tension, and pretending it does not exist is dishonest.
Yet ignoring the economics does not help the rider either. Unfunded promises and vague policies are the worst of all worlds: they look generous on paper and stall when a catastrophic claim hits.
| Framing | What It Gets Right | Where It Falls Short | Real-World Consequence |
|---|---|---|---|
| "Insurance limbo" | Captures the agonising delay and helplessness families face after a severe crash | Treats a structural coverage and classification gap like a routine admin delay | Focuses anger on slow paperwork instead of policy gaps and risk allocation |
| Pure "independent contractor" model | Preserves scheduling flexibility and low barriers to entry | Leaves severe injuries exposed when voluntary cover is narrower or slower than statutory schemes | Shifts catastrophic downside onto individuals least able to self-insure |
| Full traditional employee model | Brings clear statutory workers' comp and employer duties | Can collide with true gig flexibility, multi-apping, and zero-hour habits | Risks higher costs, stricter scheduling/control, or fewer flexible slots |
People Also Ask: Dismantling the Flawed Questions
Does a delivery app automatically owe statutory employees' compensation just because a rider was using its app?
No—and assuming it does is the fastest way to misunderstand the dispute. In Hong Kong, statutory employees' compensation under the Employees' Compensation Ordinance ties directly to whether an employer-employee relationship exists in substance, not merely whether a digital tool mediated the task. Courts look at multiple indicators—such as degree of control, equipment ownership, financial risk, ability to decline work or work elsewhere, and integration into the business. When platforms rely on voluntary insurance instead of statutory employees' comp, riders are navigating a different legal and contractual mechanism altogether.
Why do claims involving order alerts or waiting time get so messy?
Because work in the gig economy is fragmented into micro-states: offline, online waiting, travelling to a restaurant, en route to a customer, or glancing at a notification. Traditional workplace injury rules were built around clear shifts and clear premises, not push notifications on a moving two-wheeler. When coverage triggers are ambiguous around pre-acceptance or waiting states, disputes over whether an injury "arose out of and in the course of" work become inevitable.
What actually works if you are a rider, policymaker, or operator trying to fix this?
Stop treating safety and insurance as an afterthought bolted onto growth.
- For riders and couriers: Never assume a platform's group or personal accident policy covers every scenario or pays out quickly enough to cover catastrophic care. Read the actual policy triggers—especially around waiting vs. active delivery, motor licensing/third-party liability, and permanent disablement definitions—and maintain independent personal accident and income protection where affordable.
- For policymakers and regulators: Define coverage triggers by activity states (logged-in waiting, accepted order, active transit) rather than fighting endless proxy wars over 20th-century job labels, while spelling out clear payout timelines and dispute rules for severe injuries.
- For platform operators: If an alert system or incentive structure nudges riders to check screens or move fast in traffic, own the risk design. Build UI guardrails that discourage mid-ride screen glances, underwrite transparent high-severity coverage with clear service levels, and stop hiding behind ambiguous fine print when the worst happens.
A paralysed rider waiting on compensation is not just an insurance delay. It is the bill coming due on an industry that wanted all the speed of on-demand labour without settling who pays when the road breaks a body.