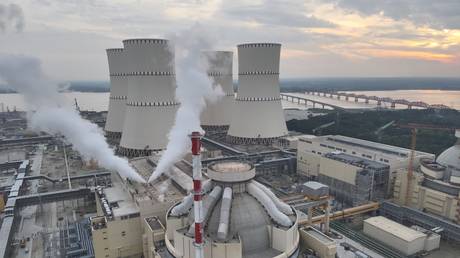
Everybody loves a shiny megaproject. Walk into any energy ministry in developing Asia, and you will find technocrats drooling over baseload capacity, glowing reactor diagrams, and grand ribbon-cutting ceremonies. The lazy consensus in global trade is that the Rooppur Nuclear Power Plant in Bangladesh is a triumph of geopolitical maneuvering. Moscow builds it, Dhaka gets clean energy, and everybody sings Kumbaya while Rosatom collects the checks.
The media treats Rooppur as a milestone of industrial progress. Headlines cheer every concrete pour and announcement of a start date as if the reactor core itself is the finish line.
They are missing the entire point.
The plant is not a monument to energy independence. It is a masterclass in financial entanglement, wrapped in radioactive concrete and financed by a creditor who holds all the cards. While officials pop champagne over commissioning timelines, the real crisis is waiting in the amortization schedules and foreign exchange reserve drains.
Let us look at the mechanics of how this deal was actually constructed, why the traditional cheerleading is dangerous, and what happens when the grace period expires.
The Financing Illusion That Nobody Wants to Talk About
Rosatom does not build nuclear plants out of the goodness of the Kremlin's heart. They export Russian state capital disguised as turnkey infrastructure.
When Bangladesh signed the deal to build the 2,400-megawatt plant at Rooppur, the Russian Federation extended a state export credit of 11.38 billion dollars, covering 90 percent of the construction cost. Sounds generous on paper. Free money to jumpstart a modern grid, right?
Wrong.
Loans of this magnitude carry grace periods that eventually end. The repayment terms kick in right as the plant transitions from construction to commercial operation. Dhaka has to service this debt in hard currency, predominantly US dollars or Russian rubles, depending on shifting bilateral settlement mechanisms, while earning revenue in weakening Bangladeshi Taka.
I have watched sovereign borrowers walk straight into this exact currency mismatch trap across three continents. You borrow in hard currency for capital-intensive heavy industry, but your domestic revenue stream is local currency subject to steady depreciation against the greenback. Every time the Taka slips a few percentage points against the dollar, the real debt burden of Rooppur balloons.
The conventional narrative focuses entirely on kilowatt-hours and reactor safety. It completely ignores the macroeconomic gravity of servicing an eleven-billion-dollar sovereign debt obligation during a period of global foreign exchange tightening.
The Nuclear Technocrat Fallacy
There is a pervasive myth in energy planning that baseload nuclear power is a plug-and-play solution for developing economies. The argument goes that solar and wind are intermittent, coal is dirty, so splitting the atom is the only way to power a booming manufacturing sector like Bangladesh's garment industry.
This view assumes a grid topology and institutional maturity that simply does not exist in most emerging markets.
Nuclear plants are
Stop Cheering Rosatoms Rooppur Timeline Because Bangladesh is Walking Into a Financial Trap
business, news, technology
Everyone in energy journalism is popping champagne over Rosatom penciling in a launch date for the Rooppur nuclear power plant in Bangladesh. The headlines read like a geopolitical fairy tale. Moscow exports high-tech progress to Dhaka, South Asia gets clean baseload megawatts, and VVER-1200 reactors prove Russian engineering remains export-proof despite western sanctions.
It is a fairy tale. And like most fairy tales, it ignores the brutal arithmetic of sovereign debt and grid reality.
I have watched emerging markets swallow the turnkey nuclear pill for two decades, and the morning after is always agonizing. Dhaka is not buying a clean energy future; they are signing up for a forty-year financial anchor wrapped in a radioactive bow. The conventional wisdom tells you that getting your first atomic kilowatt-hour is a triumph of national development. The contrarian truth is that Rooppur might become the most expensive electricity experiment in South Asia, locking Bangladesh into a fixed-price sovereign debt obligation while domestic gas reserves deplete and renewable costs plummet.
Let us look at the structure of this deal. The $12.65 billion price tag is ninety percent financed by a Russian state credit line. On paper, that sounds generous. In practice, it means Bangladesh is borrowing billions in foreign currency to pay Russian contractors, using state guarantees, while generating revenue in local currency that faces steady depreciation against the US dollar. When currency mismatch meets a multi-decade repayment schedule, central bank governors do not sleep.
The lazy consensus treats Rosatom as a benevolent infrastructure provider overcoming supply chain hurdles. They are not. They are aggressive geopolitical vendors managing a captive buyer. Rosatom builds the plant, supplies the fuel for its entire lifecycle, and takes back the spent fuel under proprietary lease arrangements. Bangladesh has zero domestic uranium enrichment capability and zero indigenous waste management infrastructure. They have outsourced the cradle-to-grave lifecycle of their most critical national asset to a foreign power currently isolated from western financial clearing systems.
To understand why this is a trap, you have to look at the grid math that energy ministers refuse to publish. Rooppur consists of two VVER-1200 units totaling roughly 2,400 megawatts. Pumping 2,400 megawatts of baseload power into a national grid that suffers from frequent transmission bottlenecks and localized demand spikes is like trying to force a firehose into a garden sprinkler.
Grid stability requires flexibility. Nuclear power plants are notoriously stubborn beasts. They hate ramping up and down to match diurnal load curves. They want to run at one hundred percent capacity all the time, or they lose money. When industrial demand in Dhaka drops or transmission lines trip during monsoon storms, what happens to all those nuclear electrons? Without massive, expensive pumped-storage hydro or battery installations—which Bangladesh has neither funded nor built at scale—baseload oversupply becomes a system hazard.
Proponents love to point out that nuclear power is carbon-free. True. But carbon emissions are not the only metric of economic survival for a developing nation. The levelized cost of electricity from new nuclear builds routinely underestimates construction overruns and financing costs. By the time inflation, currency depreciation, and interest during construction are factored into the tariff structure, the Bangladesh Power Development Board will be forced to buy power from Rooppur at rates that far exceed modern utility-scale solar paired with storage.
Think about the opportunity cost. Twelve billion dollars deployed across decentralized solar, industrial rooftop installations, grid-scale battery storage, and transmission loss reduction would have modernized the entire distribution network of Bangladesh three times over. Instead, that capital is buried in two giant concrete domes on the banks of the Padma River, benefiting Russian state conglomerates and a narrow slice of technocratic elite who measure national prestige in gigawatts rather than grid resilience.
The defenders of the project argue that nuclear is the only way to escape fossil fuel dependence. This is a false dichotomy. Bangladesh is not choosing between coal and the atom; they are choosing between financial sovereignty and technological vanity. Natural gas fields in the Bay of Bengal are under-explored due to bureaucratic paralysis, yet the state finds billions to finance imported nuclear fuel and Russian technical oversight for sixty years.
When the first unit finally starts commercial operation, expect a round of self-congratulatory speeches in Dhaka and Moscow. Politicians will cut ribbons. Press releases will flow. But three years later, when the principal repayments kick in while the local currency struggles against global inflation, and the grid operators sweat over how to absorb base-load inflexibility during low-demand windows, the reality will set in.
You do not modernize an economy by importing white elephants on credit. You modernize it by matching generation to demand, preserving fiscal health, and refusing to let geopolitical vanity dictate national balance sheets.
Bangladesh did not buy energy independence. They bought a Russian mortgage with a nuclear warranty.