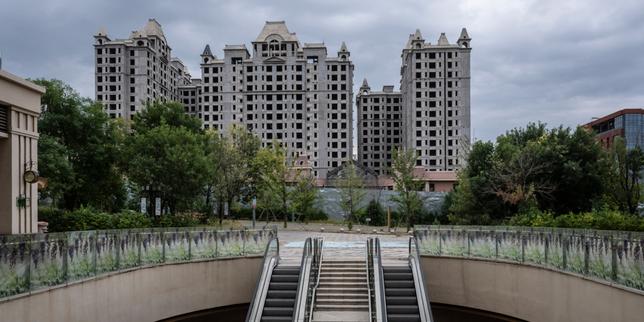
The physical manifestation of China's real estate crisis is not found in complex balance sheets or offshore bond yields, but in concrete shells standing vacant across regional peripheries. Huailai, positioned geographically as a spillover corridor for Beijing yet economically isolated by structural deceleration, serves as a masterclass in regional overextension. When developers like Evergrande acquired vast tracts of land on the assumption of perpetual urban expansion, they operated under a flawed assumption of infinite demand elasticity. Understanding the Huailai phenomenon requires dismantling the macroeconomic incentives that fueled it, identifying the transmission mechanisms of systemic contagion, and analyzing the capital allocation failures that transform municipal ambitions into dormant infrastructure.
At the core of the regional crisis lies a misalignment of fiscal incentives between local governments and developers. Municipal authorities in peripheral zones relied heavily on land conveyance fees to fund local budgets and infrastructure projects. This created an institutional imperative to convert agricultural and industrial land into residential zoning, regardless of actual demographic absorption capacity. Developers, incentivized by high leverage and rapid turnover models, acquired land banks far exceeding near-term market clearing volumes. Recently making news in related news: Nationalizing Thames Water Is A Taxpayer Trap That Bails Out Wall Street.
The financial engineering underpinning this expansion relied on a continuous cycle of presales. Developers used capital from early-stage residential unit sales to fund land acquisitions and construction commitments for subsequent projects. This structure functions effectively during an expansionary cycle where asset prices appreciate and liquidity remains abundant. However, the model exhibits extreme fragility when monetary conditions tighten or buyer confidence contracts. Once presales stall, cash flow velocity approaches zero, exposing the underlying asset liability mismatch.
Huailai exemplifies the consequences of this liquidity freeze. Projects initiated during peak speculative periods lack the completion funding necessary to deliver habitable units, leaving buyers with mortgages on unbuilt or abandoned properties. The regional economy, having specialized entirely around construction and real estate services, experiences a concurrent contraction across ancillary sectors. Retail, hospitality, and local services face sudden demand destruction as construction labor departs and regional income expectations adjust downward. Further details on this are explored by Investopedia.
The contagion mechanism operates through both financial channels and confidence channels. Financial institutions holding developer debt face rising non-performing loan ratios, prompting a contraction in credit extension across the broader economy. Simultaneously, households witness the impairment of their primary asset class. Real estate has historically captured the vast majority of Chinese household wealth, functioning as the primary vehicle for private capital accumulation. When projects fail to deliver, the wealth effect turns negative, depressing consumer discretionary spending and reinforcing deflationary pressures.
Addressing the structural overhang in markets like Huailai requires a shift from liquidity management to asset restructuring. Traditional monetary easing tools fail to address the fundamental mismatch between housing supply and genuine demographic demand in peripheral locations. Insoluble projects must be written down, and capital structures reorganized to establish realistic valuations. Municipalities forced to transition away from land-sale-dependent fiscal models must develop sustainable recurring revenue streams, such as local property taxation or regional productivity enhancements.
The long-term trajectory of regions caught in this cycle depends on the state's capacity to absorb stranded assets without exacerbating moral hazard. Centralized asset management vehicles can theoretically step in to complete unfinished developments or convert vacant housing stock into subsidized rental housing or public infrastructure. Yet, each intervention carries an opportunity cost, tying up capital that might otherwise support technological upgrading or productivity-driven growth.
The Huailai ghost city is not an isolated anomaly of poor municipal planning, but the logical endpoint of a growth model predicated on debt-financed physical expansion. Sustainable stabilization in China's property sector requires accepting permanent valuation adjustments in non-core geographies and reallocating capital toward regions exhibiting genuine organic economic agglomeration.