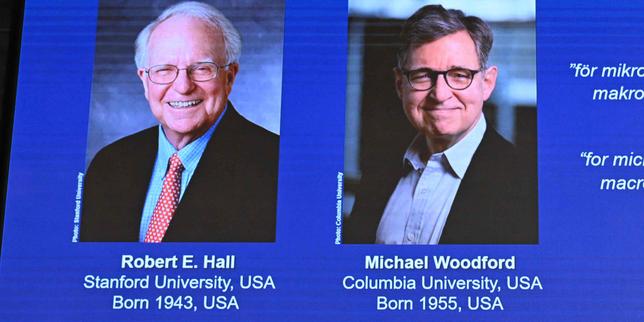
The Swedish Academy made a calculated choice when it awarded the 2026 Sveriges Riksbank Prize in Economic Sciences in Memory of Alfred Nobel to Robert E. Hall and Michael Woodford. For decades, the discipline rewarded architects of abstract equilibrium—models where markets clear instantly and prices adjust with frictionless grace. Hall and Woodford spent their careers tearing down those pristine assumptions. They mapped the actual friction points where monetary policy stalls, labor markets freeze, and institutional inertia breaks the grand equations of classical theory.
The choice of these two American economists signals a profound institutional pivot. Central banks spent the post-pandemic years fighting inflation spikes with blunt interest rate hikes, often misreading how labor hoarding and sticky wage dynamics would alter the transmission mechanism of monetary policy. Hall and Woodford spent decades explaining precisely why those traditional levers fail to behave according to textbook design. Their work is the intellectual backbone of modern macroeconomics, even if the general public only encounters it through the downstream turbulence of mortgage rates and employment reports.
Robert E. Hall spent his career at Stanford University investigating the microfoundations of macroeconomic instability. He did not look at the economy from a satellite view. He drilled down into the friction of individual choices, specifically why unemployment persists long after a recession theoretically bottoms out. Traditional neoclassical theory viewed unemployment as voluntary leisure or a simple mismatch of skills. Hall looked at the data and saw something entirely different. He identified how labor markets suffer from massive structural friction, where wages do not adjust downward during downturns because firms and workers operate under implicit contracts and fairness norms.
When a shock hits, employers do not slash wages across the board. They freeze hiring or lay workers off. This creates prolonged joblessness not because workers refuse lower pay, but because the cost of adjusting wages openly destroys workplace morale and productivity. Hall formalized this reality, proving that labor market fluctuations are driven largely by changes in the surplus value of matches between workers and firms rather than simple labor supply shifts. His work on the efficiency wage hypothesis and the zero lower bound of interest rates provided central bankers with the analytical tools to understand what happens when monetary policy loses its grip.
Michael Woodford, working from Columbia University, attacked a different pillar of neoclassical orthodoxy: the separation of monetary policy from consumer expectations. His 2003 masterpiece, Interest and Prices, fundamentally altered how the Federal Reserve, the European Central Bank, and global monetary authorities communicate. Woodford demonstrated that monetary policy works primarily through its influence on expectations about the future path of interest rates and inflation, rather than just the immediate mechanical effect of the current overnight rate.
Before Woodford, central banking was largely treated as an exercise in mechanical management, akin to adjusting a thermostat. Woodford introduced the New Keynesian framework that placed nominal rigidities—sticky prices and wages—at the center of economic analysis. He proved that if a central bank can credibly commit to a future path of policy, it can steer the economy effectively even when short-term rates hit rock bottom. This insight became the theoretical foundation for forward guidance, the communication strategy that defined central bank policy during the quantitative easing era.
The convergence of Hall and Woodford in this year's Nobel prize creates a cohesive narrative about modern economic reality. Markets do not clear instantly. Information is asymmetric. Nominal rigidities are not temporary annoyances to be smoothed away in a dynamic stochastic general equilibrium model; they are the core mechanisms that amplify economic shocks.
To understand why their contributions matter right now, look at the recent history of global inflation. When supply chains fractured and energy markets experienced structural shocks, orthodox models predicted rapid wage-price spirals or immediate cooling depending on the monetary response. Instead, labor markets exhibited extraordinary resilience through what analysts termed the Great Resignation and subsequent labor hoarding. Companies kept workers on their payrolls despite declining margins because the replacement cost of talent after the pandemic shock was too high.
Hall's models predicted this behavior decades in advance. He understood that firms view workers as investments rather than interchangeable variables. When demand dips, businesses hoard labor to avoid the catastrophic productivity losses associated with retraining new hires when the cycle turns. This explains why unemployment figures remained historically low even as central banks engineered the most aggressive tightening cycle in forty years.
Simultaneously, Woodford's framework explains why central bank credibility became the central battleground of the post-pandemic era. When inflation surged, the Federal Reserve had to convince markets that the price spikes were transitory or, when proven wrong, that future tightening would be swift and absolute. Central banking became an exercise in narrative management. If financial markets and wage-setters believe the central bank will tolerate higher inflation, nominal rigidities lock that expectation into place, creating self-fulfilling price spirals. Woodford's mathematics provided the proof that central bank communication is monetary policy.
The academic lineage connecting Hall and Woodford runs through the halls of the Hoover Institution, the National Bureau of Economic Research, and elite graduate seminars where the mathematical machinery of modern macroeconomics was forged. Yet their legacy is deeply practical. They took the messy, imperfect reality of human behavior—contracts, psychological anchors, search costs, and bounded rationality—and integrated it into rigorous quantitative models.
Consider the challenge of modern financial stability. As central banks navigate quantitative tightening and the unwinding of decades of artificial liquidity, they operate in an environment of structural friction. Asset prices do not adjust smoothly. Credit markets freeze when counterparty risk spikes because information is never complete. Hall's work on asset pricing and labor market frictions demonstrates that financial shocks propagate through the real economy via balance sheet constraints and labor market adjustments.
Critics often argue that academic economics remains divorced from reality, lost in a haze of calculus and assumptions. Hall and Woodford defied that critique by building theories that directly address why reality refuses to match the textbook. They did not invent a frictionless world. They measured the friction and showed us how the machine actually breaks down.
The 2026 Nobel prize recognizes that understanding economic crises requires looking past the aggregate numbers into the microeconomic friction points where human decisions collide with institutional constraints. As the global economy faces structural fragmentation, demographic decline, and rapid technological disruption, the frameworks built by Robert E. Hall and Michael Woodford remain the essential lens through which policymakers must navigate the turbulence ahead. The markets will continue to generate friction, and central banks will continue to grope for leverage in the dark, but the map we use to find our way was drawn by these two economists.