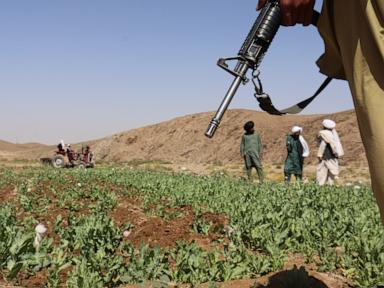
Afghanistan poppy cultivation increased by 19 percent in 2024, reaching 12,800 hectares according to the United Nations Office on Drugs and Crime (UNODC). This rebound happened despite the strict Taliban opium ban enacted in April 2022. While overall production remains a fraction of the 232,000 hectares recorded before the prohibition, the geographic shift of the harvest and skyrocketing farm-gate prices reveal a rural economy pushed past its breaking point. Farmers are returning to illicit crops not out of ideological defiance, but because starvation leaves them no alternative.
The narrative pushed by Kabul over the last two years was simple. The Islamic Emirate claimed it had achieved what a twenty-year Western military coalition and billions of dollars in counternarcotics funding could not. For one growing season, the numbers backed them up. In 2023, opium cultivation plummeted by 95 percent. For a deeper dive into this area, we suggest: this related article.
That initial drop was never sustainable. The 2022 decree relied entirely on fear, sudden enforcement, and the fact that major traders and wealthy landowners were sitting on massive stockpiles of raw opium harvested in previous years. When supply dried up, prices exploded.
The Economics of Desperation
In rural Afghanistan, economics always outlasts ideology. By mid-2024, the price of dry opium hovered around $730 per kilogram, roughly ten times higher than pre-ban averages. For a subsistence farmer facing severe drought, international sanctions, and the collapse of foreign aid, the math is straightforward. For broader context on this issue, comprehensive reporting is available at The Guardian.
Wheat cannot feed a family on small plots of irrigated land. A farmer planting wheat on a single jerib (roughly one-fifth of a hectare) might generate a few hundred dollars in gross revenue, barely enough to cover fertilizer, seed, and irrigation costs. That same plot planted with opium poppy yields a high-value, non-perishable cash crop that acts as both currency and collateral in an economy without a functioning banking system.
To understand the mechanics of this trap, consider a hypothetical example of a smallholder farmer in a remote valley. Facing a $1,000 debt from the previous winter, he receives an advance from a local trafficker. The trafficker provides seeds and cash upfront in exchange for a guaranteed portion of the spring harvest at a fixed, below-market rate. If the farmer plants wheat, he defaults on his loan and loses his land. If he plants poppy, he survives another year, even if he risks having his fields destroyed by local authorities.
This credit system, known locally as salaam, underpins the entire agrarian sector. When the Taliban banned poppy without replacing the credit mechanisms that poppy funded, they triggered a liquidity crisis across the countryside.
A Geographic Shift to the Northeast
The UNODC data highlights a critical structural change in how and where the drug trade operates. Historically, the southern provinces of Helmand and Kandahar were the undisputed engines of global heroin production, accounting for more than half of Afghanistan's total output. Those southern heartlands are also the traditional political base of the Taliban leadership.
Enforcement in the south has remained relatively strict. Because the regime's core commanders hail from Helmand and Kandahar, compliance there is tied directly to internal political legitimacy and tribal loyalty.
The 2024 surge occurred elsewhere. Roughly 59 percent of all cultivation shifted to the northeastern provinces, led by Badakhshan.
Badakhshan is mountainous, isolated, and chronically impoverished. Its terrain makes mechanized eradication difficult, and its population has historically maintained an uneasy, often adversarial relationship with the Pashtun-dominated leadership in Kandahar. In May 2024, violent protests erupted in Badakhshan's Argo and Darayim districts after Taliban eradication teams attempted to destroy poppy fields, resulting in multiple civilian deaths. The clashes forced local commanders to pause eradication efforts to prevent a broader regional uprising.
| Metric | 2022 (Pre-Ban) | 2023 (Year 1 of Ban) | 2024 (Rebound) |
|---|---|---|---|
| Total Area Cultivated | 232,000 hectares | 10,800 hectares | 12,800 hectares |
| Primary Cultivation Hub | Southwest (Helmand) | Southwest / Northeast | Northeast (Badakhshan) |
| Average Dry Opium Price | ~$75 / kg | ~$400 / kg | ~$730 / kg |
| Estimated Farmer Income | $1.36 Billion | $110 Million | $260 Million |
The numbers tell a story of consolidation rather than total collapse. While total acreage is down by roughly 94 percent compared to 2022, total farmer income from opium more than doubled between 2023 and 2024, rising from $110 million to $260 million. Fewer farmers are growing the crop, yet those who take the risk are capturing windfall profits.
The Stockpile Cushion Is Gone
For the first eighteen months of the ban, the Taliban benefited from an economic buffer they did not create. Between 2017 and 2022, Afghanistan produced bumper crops of opium far exceeding global demand. Wealthy traders, mid-level commanders, and well-connected landowners warehoused thousands of metric tons of raw opium gum.
When the 2022 ban took effect, these stockpile holders saw the value of their inventory multiply overnight. They quietly supported the prohibition because it eliminated competition and maximized their profit margins. Throughout 2023, heroin continued to flow out of Afghanistan along traditional smuggling routes through Iran, Pakistan, and Central Asia, drawn entirely from existing reserves.
Those reserves are now depleting. As older inventories shrink, the financial incentive to resume cultivation intensifies across every level of the supply chain. Traffickers need fresh product to maintain their networks, and local officials—many of whom are poorly paid and operate with minimal oversight from Kabul—face mounting pressure to look the other way in exchange for informal taxes.
The Synthetic Drug Wildcard
Western policymakers often view a reduction in Afghan poppy as an automatic victory for global public health. That assumption ignores how modern illicit drug markets adapt to supply shocks.
When heroin becomes scarce and expensive, trafficking networks do not shut down. They pivot. Over the past decade, Afghanistan has quietly become one of the world's fastest-growing producers of methamphetamine. Unlike opium, which requires arable land, predictable rainfall, and months of visible agricultural labor, methamphetamine can be cooked in small, mobile labs hidden inside residential compounds.
Producers initially relied on the wild ephedra plant, which grows abundantly in Afghanistan's central highlands, to extract ephedrine. Even after the Taliban banned ephedra harvesting, traffickers shifted toward using imported chemical precursors and over-the-counter medications diverted from neighboring countries.
A prolonged opium shortage risks accelerating the transition from plant-based narcotics to synthetic opioids like nitazenes or illicitly manufactured fentanyl along Eurasian trafficking corridors. For law enforcement agencies in Europe and Asia, a market dominated by compact, hyper-potent synthetics is vastly harder to police than bulky shipments of Afghan heroin.
Why International Aid Has Failed to Fill the Gap
The Taliban have repeatedly argued that if the international community wants the poppy ban to hold, foreign governments must fund alternative livelihoods for Afghan farmers. On paper, the argument makes sense. In practice, international engagement is paralyzed by political reality.
Donor nations are unwilling to channel large-scale development aid directly through a regime that enforces systemic gender apartheid, bars girls from secondary and university education, and refuses to form an inclusive government. Without formal recognition, Afghanistan remains cut off from the global financial system, and major multilateral development projects remain frozen.
Even when alternative development programs were heavily funded during the twenty years of the Western-backed republic, they rarely succeeded at scale. Past initiatives frequently failed because they focused on crop substitution—handing out saffron bulbs, pomegranate saplings, or improved wheat seeds—without addressing the underlying structural deficits.
A farmer cannot grow pomegranates if there are no cold-storage facilities to keep the fruit from rotting, no paved roads to get it to market, and no export agreements to sell it abroad. Opium thrives precisely because it requires none of that infrastructure. The buyer comes directly to the farm gate, pays in cash, and assumes all the risk of transportation.
The Fragility of Authoritarian Enforcement
History offers a clear warning about how this ends. In July 2000, Taliban founder Mullah Omar issued a similar ban on opium cultivation. In 2001, production dropped by more than 90 percent, mirroring the 2023 collapse.
That first ban lasted barely a year before the regime fell, yet even before the US invasion in October 2001, cracks were showing. Rural resentment was boiling over, debt defaults were multiplying, and commanders in the provinces were struggling to contain economic unrest.
Today, the Taliban face the same structural trap, compounded by a population that has nearly doubled since 2001 and a climate crisis that has made water scarcity acute. UNODC satellite imagery confirms that farmers are already adapting by moving cultivation away from major highways and into hidden, high-altitude valleys where eradication teams rarely venture.
Kabul can maintain the appearance of control in the southern provinces where its political grip is tightest, and it can continue to stage public burnings of seized narcotics for international cameras. Down in the dirt of Badakhshan and the remote districts of the northeast, however, the rules are written by hunger and debt, and the 2024 harvest proves that no decree from Kandahar can outlast an empty stomach.