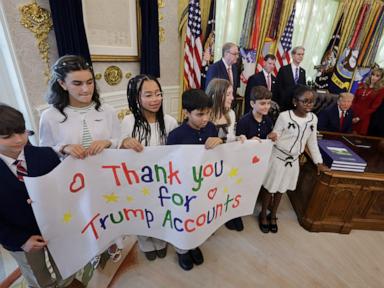
Seventy million kids now have investment accounts tied to their names. That's the headline coming out of Washington right now, and honestly, the reaction is split right down the middle between people calling it a financial miracle and people wondering what the catch is.
When Donald Trump announced that 70 million children had been enrolled in Trump Accounts, the number alone made people stop scrolling. Seventy million isn't a small pilot program or a localized test run. It's practically every child in the United States.
If you're a parent, a grandparent, or just someone who pays attention to where federal tax policy and personal finance collide, you probably have questions. You want to know if this is real money, whether you have to do anything to claim it, and how it stacks up against the college and savings accounts you're already paying into. Let's break down what's actually happening behind the press conferences and political victory laps.
How Trump Accounts Actually Work
Strip away the political branding for a second. At its core, a Trump Account is a federally backed, tax-advantaged investment account designed for minors. The whole idea is built on a math concept that Wall Street has used for centuries but everyday families often miss out on because they don't have the upfront cash.
Compounding time. That's the secret sauce here.
When money sits in a broad market index fund from the day a kid is born until they hit 18 or 25, you don't need millions of dollars on day one to end up with a serious nest egg. Even a modest seed deposit from the government—combined with optional contributions from parents, grandparents, or employers—snowballs over two decades.
Here is how the mechanics usually play out in practice:
- Automatic or streamlined enrollment. Instead of forcing low-income or busy families to fill out a 20-page IRS packet, the program uses birth records and tax filings to get kids into the system automatically. That's how the enrollment figure shot up to 70 million so fast.
- Tax-deferred growth. While the money is inside the account, you aren't getting hit with annual capital gains taxes every time dividends get reinvested.
- Restricted early access. You can't raid this account to pay for a family vacation or a new transmission on your minivan. The funds stay locked until the child reaches adulthood, at which point they can use the cash for specific milestones like higher education, vocational training, buying a first home, or starting a small business.
I've watched families struggle for years just to open a basic 529 plan because the paperwork feels intimidating and the minimums seem out of reach. By flipping the script to mass enrollment, the policy bypasses the biggest hurdle in personal finance. Inertia. Most people don't fail to invest because they hate money; they fail because getting started feels like a chore.
Why the 70 Million Number Is Raising Eyebrows
Whenever a government program hits a round, massive number like 70 million, you have to look closely at what "enrolled" actually means. Does it mean 70 million kids have active, funded portfolios with thousands of dollars sitting in index funds right this second? Not necessarily.
In the world of federal policy, enrollment often means an account shell has been generated and linked to a Social Security number. There is a massive difference between having an open account on a government ledger and having real capital compounding in the stock market.
Critics and independent budget analysts have pointed out a few friction points that don't always make it into the victory speeches:
- Seed funding gaps. Depending on household income tiers and birth years, the initial federal deposit varies. Some children receive a direct government seed contribution, while others simply get the tax-sheltered account structure without free taxpayer cash dropped in on day one.
- Investment menu limits. To keep fees low and prevent parents from gambling their kids' futures on speculative meme stocks or crypto tokens, these accounts typically restrict investments to broad, low-cost index funds or Treasury-backed options. For 99% of families, that's actually a blessing in disguise. Still, active investors often chafe at the lack of control.
- Administrative bottlenecks. Moving data between the Social Security Administration, the Treasury Department, and private financial custodians isn't smooth. Millions of families are technically "in" the program right now, yet they haven't received their login credentials or account statements in the mail.
Don't fall into the trap of assuming the government just handed your kid a guaranteed golden ticket. Think of it more like the federal government built the highway and handed you the keys to a basic sedan. You still have to put gas in the tank if you want to get anywhere impressive.
Trump Accounts vs 529 Plans and Custodial Accounts
If you're already saving for your kids, your immediate thought is probably about overlap. You might already have a 529 college savings plan or a Uniform Transfers to Minors Act (UTMA) account set up at Vanguard, Fidelity, or Schwab. Should you stop funding those and dump everything into a Trump Account?
Slow down. Each of these accounts plays a completely different role in your financial playbook.
A 529 plan is still the undisputed heavyweight champion if your primary goal is paying for college or private K-12 tuition. Contributions grow tax-free, and withdrawals are 100% tax-free as long as the money goes toward qualified education expenses. Plus, recent rule changes allow you to roll unused 529 funds into a Roth IRA for your child, which eliminates the old fear of getting penalized if your kid skips college to become an electrician or launch a startup.
A custodial UTMA or UGMA account gives you maximum flexibility. Your kid can use that money for literally anything once they hit the age of majority in your state—usually 18 or 21. Want to buy a car? Fine. Want to travel across Europe? Legal. The catch is that custodial accounts count heavily against your child when they apply for federal financial aid (FAFSA), and the tax breaks are much smaller.
Trump Accounts sit right in the middle of those two extremes. They offer broader usage rules than a traditional 529—covering first-time home purchases and business startups alongside education—without giving an 18-year-old unrestricted cash to blow on a sports car.
If you have extra cash to save each month, you don't have to pick just one. Keep funding your 529 up to whatever level gets you a state income tax deduction. Use the Trump Account to capture any federal matching dollars, employer contributions, or family gifts.
The Political Battle Over Baby Bonds and Child Wealth
It's kinda fascinating to watch how this idea evolved. For years, progressive economists like Darrick Hamilton and William Darity Jr. pushed for "baby bonds"—publicly funded trust accounts designed to close the racial and generational wealth gap. Conservatives largely hated that version because it relied on heavy wealth redistribution and massive federal spending.
Then Republicans took the core mechanism—giving every kid an asset-building account at birth—and rebranded it around free-market ownership, private capital markets, and parental contributions. Trump leaned hard into the idea that turning every American child into a literal shareholder from day one builds loyalty to the free enterprise system.
Both sides actually agree on the underlying diagnosis. Too many Americans reach age 25 with zero assets, mountains of student debt, and no realistic path to buying a home or starting a business. Where they fight is over who pays for it and how much the government controls the strings.
Economists at institutions like the Tax Foundation and the Urban-Brookings Tax Policy Center have noted that universal child accounts can dramatically boost financial literacy. When a teenager logs into an app and watches their own balance rise and fall with the S&P 500, compounding stops being a boring vocabulary word in a high school economics textbook. It becomes personal.
At the same time, budget hawks warn that if federal matching contributions expand without corresponding spending cuts elsewhere, the program adds billions to the national debt. You can't ignore the macro math. Giving 70 million accounts even a modest federal boost costs real money—money that taxpayers eventually have to cover.
What Parents Should Actually Do Right Now
Announcements from the White House move fast, while IRS guidance and brokerage rollouts move at a snail's pace. If you have children under 18, sitting around waiting for a magical check to show up in your mailbox is the wrong move.
First, verify your tax filing status and dependent records. Because mass enrollment relies heavily on recent IRS returns and Social Security records, any mismatch in your child's name, birth date, or SSN can delay account creation. Make sure your latest tax return is processed and accurate.
Second, watch for official Treasury or custodian notices—and ignore scams. Whenever a headline like "70 million children enrolled" hits the news cycle, scammers immediately spin up fake websites and phishing texts claiming you need to "pay a $29 processing fee to unlock your child's Trump Account." The federal government will never text you asking for your bank login or a fee to claim a statutory account. Only trust correspondence coming directly from .gov domains or verified financial custodians officially contracted to hold the funds.
Third, talk to grandparents and relatives before the next birthday or holiday. One of the cleanest features of these accounts is how easy they make third-party gifting. Instead of buying another plastic toy that breaks in three weeks, aunts, uncles, and grandparents can drop $50 or $100 directly into the kid's investment account. Over 18 years at an average historical stock market return, a few hundred dollars in birthday money turns into thousands.
Fourth, check your workplace benefits. A growing number of corporations are looking at child savings matches the same way they look at 401(k) matches. Ask your HR department if your company plans to offer payroll deductions or employer matching contributions for dependent investment accounts in the upcoming benefits cycle.
The headline number of 70 million enrolled kids makes for a great soundbite, yet the real impact comes down to what happens at your kitchen table. A government-created account won't make your child wealthy on its own, so treat this rollout as an open door—claim your family's credentials as soon as the custodian notices arrive, automate whatever small monthly contribution fits your budget, and let two decades of market compounding do the heavy lifting.


